Speak with a licensed insurance agent

1-888-891-0229

Can You Switch From a Medicare Supplement (Medigap) Plan to Medicare Advantage for 2027? Timing, Steps and the Way Back

Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated October 27, 2026

Key Takeaway

Yes, you can switch from a Medicare Supplement (Medigap) plan to Medicare Advantage, most often during Annual Enrollment, October 15 to December 7, 2026, for coverage starting January 1, 2027. Joining the new plan won’t cancel your Medigap policy, so you have to cancel it yourself, and getting Medigap back later isn’t guaranteed in most states.

2027 by the Numbers

$12.00

Avg. monthly Medicare Advantage premium for 2027 (CMS, Sept. 2026)

Dec. 7

Last day to switch for Jan. 1, 2027 coverage (Medicare.gov)

12 months

Trial right to return after your first Medicare Advantage plan (Medicare.gov)

4 states

CT, ME, MA and NY require yearly or year-round Medigap sales (KFF)

A low Medicare Advantage premium can look tempting next to a Medigap bill that climbs every year. Annual Enrollment for 2027 is open right now, so this is the window most people use to make the move.

The switch itself is simple. What trips people up is the order of the steps, a Medigap policy that keeps billing after the new plan starts and the question nobody asks until later: can I get my Medicare Supplement back if Medicare Advantage doesn’t work out? This guide answers all three.

Talk through the switch before you cancel anything

Speak with a licensed insurance agent

1-888-891-0229

When You Can Make the Switch

Medicare Advantage has set enrollment windows. Your Medigap policy can be dropped any time, but the Medicare Advantage plan can only be joined during one of these:

✔
Annual Enrollment Period, October 15 to December 7. Anyone with Original Medicare can join a Medicare Advantage plan. The plan must get your request by December 7, and coverage begins January 1.
✔
Special Enrollment Periods. Life events such as moving to a new address, losing other coverage, qualifying for Medicaid or getting Extra Help can open a window.
✔
Not the January to March window. The Medicare Advantage Open Enrollment Period, January 1 to March 31, is only for people who are already in a Medicare Advantage plan. You can’t use it to leave Medigap and join one.

For most people with a Medicare Supplement, that means the decision has to be made by December 7, 2026.

Switching During AEP 2027: A Dated Example

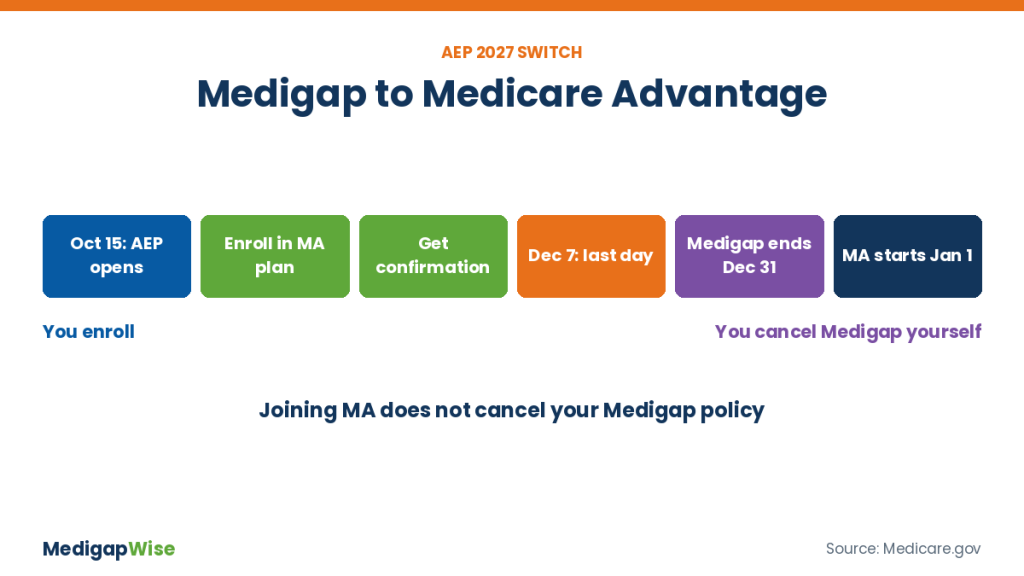
AEP 2027 timeline for switching from a Medicare Supplement plan to Medicare Advantage: enroll by December 7, 2026, end Medigap December 31, Medicare Advantage starts January 1, 2027

Here’s how the order of steps works for a January 1, 2027 start.

1
By December 7, 2026: enroll in the Medicare Advantage plan. Check that your doctors are in its network and your drugs are on its list first. If you change your mind before December 7, the last plan you choose is the one that takes effect.
2
Wait for the confirmation. The plan sends a letter or notice with your start date. Don’t cancel Medigap until you have it in hand.
3
Call your Medigap company and ask for an end date of December 31, 2026. Cancel by phone or in writing, following the company’s instructions, and ask for written confirmation of the termination date.
4
Stop the automatic payment. If your premium is drafted from a bank account, confirm the last draft date. If you prepaid quarterly or yearly, ask whether any unused premium is refunded; that depends on the policy and your state.
5
January 1, 2027: show your new card. Use your Medicare Advantage ID card at the doctor and pharmacy.

Keep paying Part B: Medicare Advantage doesn’t replace your Part B premium. You still pay it, usually from your Social Security check.

Why Joining Medicare Advantage Won't Cancel Your Medigap Policy

When you switch Part D drug plans, Medicare ends the old drug coverage automatically when the new one begins. Medigap doesn’t work that way. Medicare.gov says most Medigap policies don’t automatically cancel when you join a Medicare Advantage plan. Only you can end it.

Keeping both doesn’t buy you extra protection. A Medigap policy can’t pay Medicare Advantage deductibles, copays, coinsurance or premiums, so it would sit unused while you keep paying for it.

The rule runs the other way, too: It’s illegal for a company to sell you a Medigap policy if it knows you’re in a Medicare Advantage plan, unless your Medicare Advantage coverage will end before the Medigap policy starts.

Compare your Medigap premium with keeping it

Speak with a licensed insurance agent

1-888-891-0229

The Cost of Getting the Timing Wrong

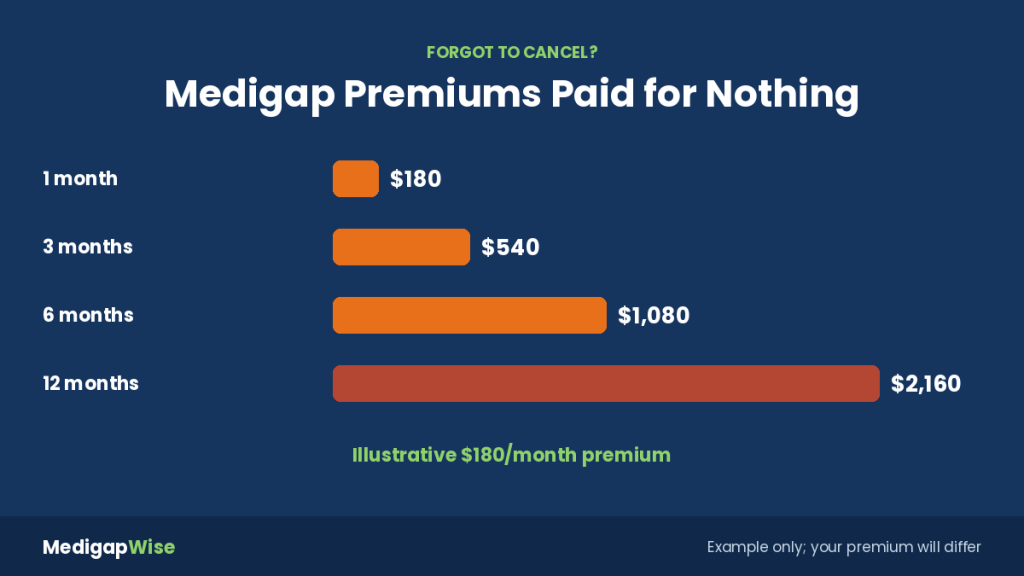
Illustrative cost of forgetting to cancel Medigap after switching to Medicare Advantage: $180 a month adds up to $1,080 after six months with no benefits paid

Two timing mistakes cost real money, and they point in opposite directions:

Cancel too late

✔Medigap keeps billing after January 1
✔It pays nothing toward Medicare Advantage costs
✔Every month is a premium with no benefit

Cancel too early

✔Medigap ends before Medicare Advantage starts
✔You’re on Original Medicare alone for those days
✔You’d owe the 20% Part B coinsurance yourself

Illustrative overlap math: say your Plan G premium is $180 a month. Forget to cancel and you pay $180 for January, $540 by the end of March and $1,080 by the end of June, all for coverage that can’t pay a single Medicare Advantage claim. Multiply your own premium by the months you overlap.

Questions? Talk to a Licensed Agent

We compare Plan G, Plan N and more from several insurance companies at no cost to you.

☎ 1-888-891-0229

No cost, no obligation to enroll

Can You Get Back Into Medigap Later?

This is the real cost of switching. Once you drop Medigap, buying it again usually means answering health questions, and the company can turn you down. Here’s how your way back depends on your situation and your state:

Your situation Can you get Medigap back? Health questions?
First time in Medicare Advantage, leave within 12 months Yes, under the federal trial right: your old policy if the company still sells it No
You live in New York or Connecticut Yes, insurers must sell Medigap year-round No
You live in Massachusetts Yes; the law sets a Feb. 1 to March 31 window and insurers offer continuous enrollment in practice No
You live in Maine One month a year chosen by each insurer, Plan A only No, during that month
Your Medicare Advantage plan leaves your area or Medicare Yes, a federal guaranteed issue right with a deadline No
Birthday or anniversary rule state (such as CA, ID, IL, KY, LA, MD, NV, OK, OR, MO) No help: these rules only let current Medigap holders change policies Usually yes
Any other case, most states Only if a company accepts your application Yes

The birthday-rule row surprises people. KFF notes they don’t let anyone without a Medigap policy buy a new one, so they won’t help after a year or more in Medicare Advantage.

Using the Medicare Advantage Open Enrollment Period, January 1 to March 31, can move you back to Original Medicare, but it doesn’t make a Medigap company take you. See our full guide to the Medigap trial right before you rely on it, and review the Medigap underwriting questions you’d face without it.

Check your state: State rules change. Confirm with your State Health Insurance Assistance Program or insurance department before you drop a policy.

Ask a licensed agent about your way back

Speak with a licensed insurance agent

1-888-891-0229

What You Give Up and What You Gain

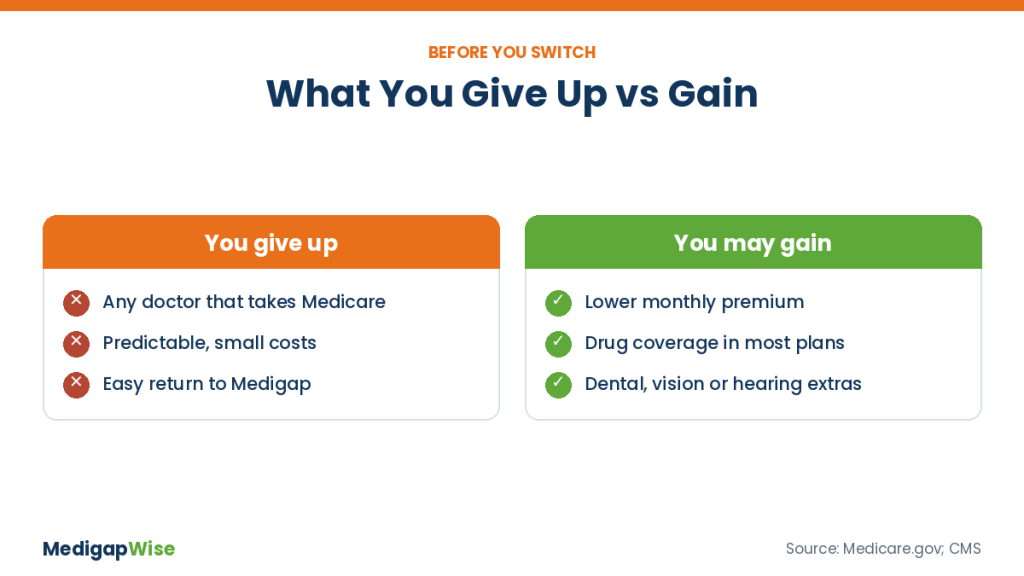
What you give up and what you gain when you switch from a Medicare Supplement plan to Medicare Advantage

Here’s what changes on January 1 if you leave a plan you already have:

What you give up

✔Seeing any provider that accepts Medicare, with no network
✔Small, predictable bills; with Plan G, mostly just the Part B deductible
✔An easy way back if your health changes

What you may gain

✔A lower premium; CMS projects $12.00 a month on average for 2027
✔Drug coverage built into most plans
✔Extras such as dental, vision or hearing, depending on the plan

Every Medicare Advantage plan has a yearly in-network out-of-pocket limit. The federal cap was $9,250 for 2026, and plans can set lower limits, so look up the exact figure for any 2027 plan you’re considering.

If You and Your Spouse Share a Household Discount

Couples don’t always switch together. Before one of you cancels, check what happens to the premium of the spouse who keeps a Medicare Supplement plan.

Many companies give a household discount when two people in the home are covered, and some require both to keep a policy. If yours does, the spouse who stays could lose the discount and see a higher bill. Ask for a quote without the discount and count that increase as part of the cost of switching.

Learn how discounts work by company in our guide to the Medicare Supplement household discount.

Your Checklist Before You Switch

✔
Confirm your doctors, hospitals and specialists are in the Medicare Advantage plan’s 2027 network.
✔
Check your prescriptions on the plan’s drug list.
✔
Find the plan’s 2027 out-of-pocket limit and price a bad year, not just a healthy one.
✔
Ask whether you’re eligible for a trial right, and note the date 12 months after your start.
✔
If you live in New York or Connecticut, confirm you can buy Medigap again later. Everywhere else, assume health questions.
✔
Get your spouse’s Medigap premium without a household discount, if one applies.
✔
Enroll by December 7, wait for the confirmation, then cancel Medigap effective December 31.

Our guide to Medicare Supplement open enrollment explains how you got your Medigap policy without health questions, and Medicare Supplement open enrollment vs. guaranteed issue shows which rights could bring you back.

Keep Reading

California Medicare Supplement Birthday Rule 2027: how the 60-day window after your birthday lets California Medigap holders change companies or plans without health questions.

Switching From Medigap to Medicare Advantage — Frequently Asked Questions

➤ Can I switch from Medigap to Medicare Advantage at any time?

No. You can drop Medigap any time, but you can only join a Medicare Advantage plan during Annual Enrollment, October 15 to December 7, or a special enrollment period, such as after a move.

➤ Does enrolling in Medicare Advantage cancel my Medigap policy?

No. Most Medigap policies don’t cancel automatically when you join Medicare Advantage. Call your Medigap company and ask for an end date that matches the day before your Medicare Advantage coverage starts.

➤ Can I keep my Medigap policy as a backup while I try Medicare Advantage?

You can keep paying for it, but it won’t pay any Medicare Advantage copays, deductibles or premiums. Most people would pay premiums for nothing, so the trial right is the real safety net if it’s your first Medicare Advantage plan.

➤ When should I cancel my Medicare Supplement plan?

After your Medicare Advantage enrollment is confirmed. For a January 1, 2027 start, ask the Medigap company to end your policy on December 31, 2026, so there’s no gap and no overlap.

➤ Can I use the January to March Open Enrollment Period to switch from Medigap?

No. The Medicare Advantage Open Enrollment Period, January 1 to March 31, is only for people already in a Medicare Advantage plan. It lets them change plans or go back to Original Medicare.

➤ If I don’t like Medicare Advantage, can I get my Medigap plan back?

If this is your first Medicare Advantage plan and you leave within 12 months, the trial right lets you get your old policy back if the company still sells it. After that, most states let companies ask health questions and decline you.

➤ Does the birthday rule help me return to Medigap?

Usually not. Birthday and anniversary rules in states like California, Oregon, Illinois and Missouri only let people who already have Medigap change policies. They don’t let you buy one after leaving.

➤ Will my spouse’s Medigap premium go up if I switch?

It might. If the company’s household discount requires two covered people, your spouse could lose it when you cancel. Ask for a quote on your spouse’s policy without the discount before you switch.

Free Medigap Price Comparison

Call a Licensed Agent Now

Compare Plan G, Plan N and more from several insurance companies in one call.

☎ 1-888-891-0229

No cost, no obligation to enroll