Speak with a licensed insurance agent

1-888-891-0229

Medicare Supplement Open Enrollment vs Guaranteed Issue 2027: Key Differences and When Each Applies

Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated October 27, 2026

Key Takeaway

Medicare Supplement open enrollment is a one-time, 6-month window at 65+ with Part B when you can buy any plan sold in your state with no health questions. Guaranteed issue rights apply only after certain events, such as losing employer coverage, and usually last 63 days.

Both terms promise the same thing: a Medicare Supplement (Medigap) company has to sell you a policy, no matter your health. But one is a window everyone gets once, and the other only opens when something happens to your coverage.

Here’s how Medicare Supplement open enrollment and guaranteed issue rights compare for 2027, and what happens if you miss both.

Check which window you're in

Speak with a licensed insurance agent

1-888-891-0229

Open Enrollment vs Guaranteed Issue: The Short Answer

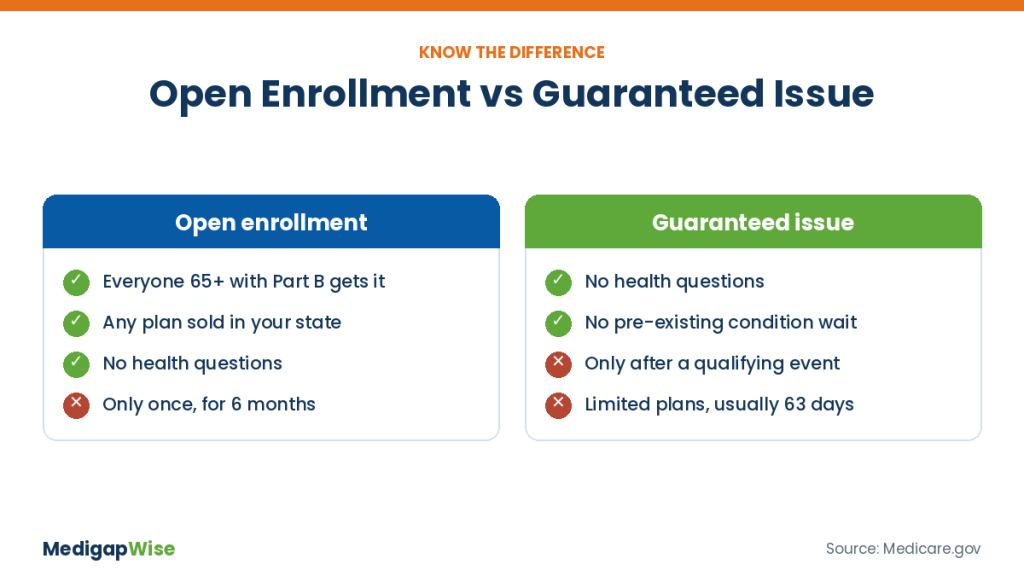
Medicare Supplement open enrollment vs guaranteed issue compared: open enrollment lets you buy any plan once at 65, guaranteed issue limits you to certain plans after a qualifying event

Both protections stop a company from turning you down or charging you more because of your health. The difference is who gets them, when and what you can buy.

✔
Open enrollment is automatic. Everyone gets one 6-month window when they’re 65 or older and enrolled in Part B, and you can choose any Medigap policy sold in your state.
✔
Guaranteed issue rights are triggered by an event, like losing employer coverage or your Medicare Advantage plan leaving your area. They usually last only 63 days and limit you to certain plan letters.
✔
Outside both, there’s no federal guarantee. In most states, companies can ask health questions and decline you.

If you’re still deciding when to apply, start with our main guide to Medicare Supplement open enrollment.

What Is Medicare Supplement Open Enrollment?

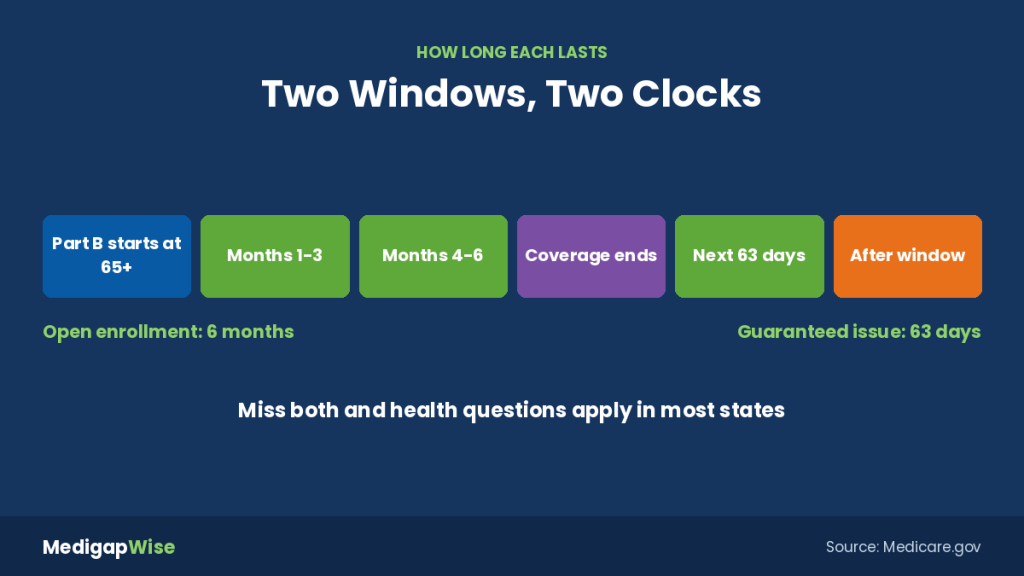
Timeline of the 6-month Medicare Supplement open enrollment period compared with the 63-day guaranteed issue window after coverage ends

Your Medigap open enrollment period lasts 6 months. It starts the first day of the month you’re both 65 or older and enrolled in Medicare Part B. It happens once and can’t be repeated.

During those 6 months, you can buy any Medigap policy sold in your state. The company can’t use medical underwriting to deny you, and it generally can’t charge you more because of past or present health problems.

One catch: A company can make you wait up to 6 months before it covers a pre-existing condition. If you had at least 6 months of continuous creditable coverage, such as an employer plan, right before applying, the company can’t make you wait.

Working past 65? If you delay Part B because you have job-based coverage, your open enrollment period doesn’t start until you sign up for Part B.

What Are Guaranteed Issue Rights?

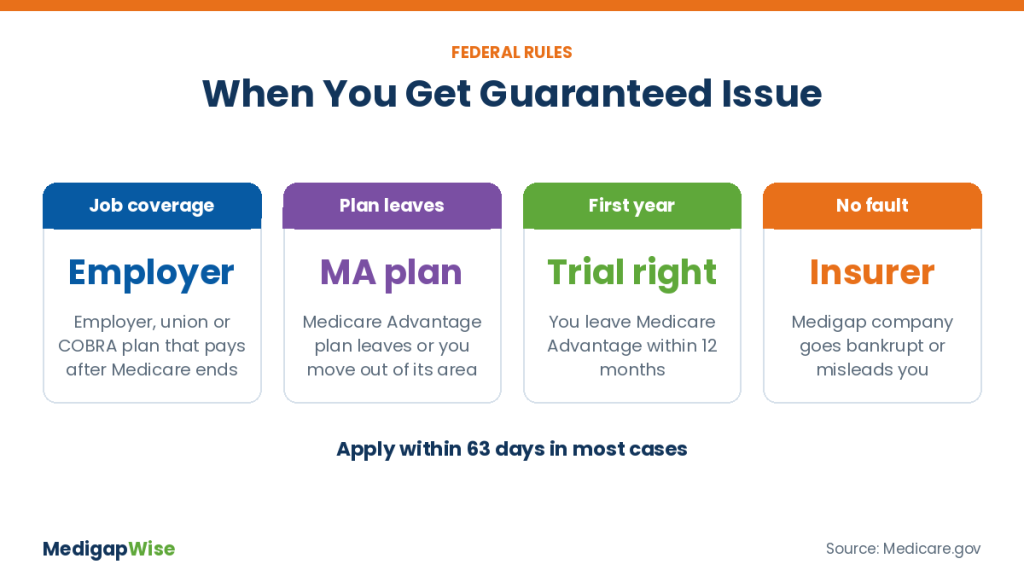
Federal Medicare Supplement guaranteed issue situations: employer coverage ends, Medicare Advantage plan leaves your area, trial right, and insurer bankruptcy or misconduct

Guaranteed issue rights, also called Medigap protections, apply only in limited situations. When one applies, the company must sell you a policy, must cover all your pre-existing conditions and can’t charge you more because of your health.

Under federal law, you generally have a guaranteed issue right when:

1
Your employer or union coverage ends. You have Original Medicare plus an employer, retiree, COBRA or union plan that pays after Medicare, and that plan is ending.
2
Your Medicare Advantage plan leaves. The plan leaves Medicare, stops serving your area, or you move out of its service area, and you switch to Original Medicare.
3
You use your trial right. You joined Medicare Advantage or PACE for the first time and leave within the first year.
4
Your Medigap company fails. The insurer goes bankrupt or your coverage ends through no fault of your own.
5
A company broke the rules. You leave a Medicare Advantage plan or drop a Medigap policy because the company didn’t follow the rules or misled you.

Moving out of a Medicare SELECT policy’s service area also counts. For the first-year rules, see our guide to the Medigap trial right.

Side-by-Side: Open Enrollment vs Guaranteed Issue

Open enrollment period Guaranteed issue right
Who gets it Everyone 65+ enrolled in Part B Only people with a qualifying event
When 6 months from your Part B start at 65+ Usually up to 63 days after coverage ends
How often Once in your lifetime Each time a qualifying event happens
Plans you can buy Any Medigap plan sold in your state Plans A, B, C, D, F, G, K or L
Plans C and F Only if eligible for Medicare before 2020 Only if eligible for Medicare before 2020
Pre-existing condition wait Up to 6 months without prior creditable coverage None
Health questions No No

The biggest difference is plan choice. Open enrollment lets you buy Plan N or any plan sold in your state; guaranteed issue limits you to Medicare’s list, though Plan G is on it. Compare every plan letter in our guide to Medicare Supplement plans.

Compare Medicare Supplement plans in your area

Speak with a licensed insurance agent

1-888-891-0229

The 63-Day Window and Other Deadlines

For most guaranteed issue rights, you must apply no later than 63 days after your old coverage ends. When employer coverage ends or your Medigap company fails, Medicare counts from the latest of:

✔
The date your coverage ends
✔
The date on the notice telling you your coverage is ending
✔
The date on a claim denial, if that’s how you learned your coverage ended

If you’re leaving Medicare Advantage, you can apply as early as 60 days before that coverage ends.

Keep your paperwork: Save letters, notices, claim denials and their envelopes as proof. With COBRA, you can buy right away or wait until COBRA ends.

Questions? Talk to a Licensed Agent

We compare Plan G, Plan N and more from several insurance companies at no cost to you.

☎ 1-888-891-0229

No cost, no obligation to enroll

If You're Under 65 or Live in a State With Extra Rules

Federal law doesn’t require companies to sell Medigap to people under 65 who have Medicare because of a disability or End-Stage Renal Disease. KFF counts 38 states that do require at least one policy for people under 65 with disabilities (October 2026). At 65, you still get your own open enrollment period.

Some states also go further than federal law for people 65 and older:

Year-round guaranteed issue

✔New York and Connecticut let you buy Medigap any time of year
✔Massachusetts insurers offer continuous open enrollment in practice

Birthday rules

✔About 16 states, including California, Illinois, Oregon and Nevada
✔Let current Medigap holders switch around their birthday

Anniversary rules

✔Missouri lets you switch near your policy anniversary
✔Other states have their own switching rules

State rules change, so check with your State Insurance Department before you drop a policy.

What Happens If You Miss Both? An Example

Outside both, most companies use medical underwriting and can decline you or charge more. See our guide to Medigap underwriting questions.

Illustrative example: Tom turned 65 in 2025, joined Part B and skipped Medigap because he felt healthy. In 2027, at 67, he’s diagnosed with cancer and wants Plan G. With no qualifying event, a company can decline him.

Applied during open enrollment

✔Plan G at the standard rate for his age
✔No health questions
✔Part B coinsurance covered

Applying in 2027, outside both

✔Health questions on the application
✔Could be declined for his diagnosis
✔Left paying 20% of Part B costs himself

If Tom is declined and stays on Original Medicare alone, he pays 20% of most Part B costs, with no yearly limit. On a hypothetical $60,000 in outpatient treatment, that’s about $12,000 out of his pocket. Figures are illustrative only. Learn more about Medicare Supplement and pre-existing conditions.

Talk to a licensed agent about your options

Speak with a licensed insurance agent

1-888-891-0229

How to Use Each One, Step by Step

1
Find your open enrollment dates. Count 6 months from the first day of the month you’re 65 and in Part B.
2
Check for a qualifying event. If your employer plan, Medicare Advantage plan or Medigap company is ending, you may have a guaranteed issue right.
3
Mark your deadline. Most guaranteed issue rights end 63 days after your coverage ends.
4
Compare prices for the same plan letter. Benefits are identical by letter, so compare premiums and rate history.
5
Don’t cancel old coverage too soon. Wait until your new policy is approved, unless you’re using a right that requires the old plan to end first.

Ready to apply? Our guide on how to sign up for Medigap walks through the application.

Keep Reading

Switching From Medicare Supplement to Medicare Advantage: when you can make the move for 2027, how to cancel Medigap without a gap or double premiums, and whether you can get it back.

Medicare Supplement Open Enrollment vs Guaranteed Issue — Frequently Asked Questions

➤ What is the difference between Medicare Supplement open enrollment and guaranteed issue?

Open enrollment is a one-time, 6-month window everyone gets when they’re 65 or older and enrolled in Part B. Guaranteed issue rights apply only after certain events, such as losing employer coverage, and limit your plan choices.

➤ How long is Medicare Supplement open enrollment?

It lasts 6 months and starts the first day of the month you’re 65 or older and enrolled in Part B. It happens only once and can’t be repeated.

➤ How long do guaranteed issue rights last?

Most guaranteed issue rights last until 63 days after your old coverage ends. If you’re leaving a Medicare Advantage plan, you can apply as early as 60 days before that coverage ends.

➤ Which plans can I buy with a guaranteed issue right?

Under federal rules, you can buy Plan A, B, C, D, F, G, K or L sold in your state. Plans C and F are only available if you were eligible for Medicare before January 1, 2020.

➤ Is there a waiting period for pre-existing conditions?

During open enrollment, a company can make you wait up to 6 months for pre-existing condition coverage if you didn’t have at least 6 months of creditable coverage before applying. With a guaranteed issue right, there’s no waiting period.

➤ Can I use open enrollment and guaranteed issue more than once?

Open enrollment happens only once. Guaranteed issue rights can apply each time you have a qualifying event, such as an employer plan ending or a Medicare Advantage plan leaving your area.

➤ Which states have year-round guaranteed issue for Medicare Supplement plans?

New York and Connecticut let people 65 and older buy Medigap any time of year without health questions. In Massachusetts, insurers offer continuous open enrollment in practice.

➤ What if I missed my open enrollment period and have no guaranteed issue right?

You can still apply, but in most states the company can ask health questions and decline you or charge more. Some states have birthday or anniversary rules that let current Medigap holders switch plans.

Free Medigap Price Comparison

Call a Licensed Agent Now

Compare Plan G, Plan N and more from several insurance companies in one call.

☎ 1-888-891-0229

No cost, no obligation to enroll