Speak with a licensed insurance agent

1-888-891-0229

Medicare Supplement Plans 2027: Compare Plan G, Plan N and All 10 Plans


Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated October 20, 2026

Key Takeaway

There are 10 standardized Medicare Supplement plans, and each letter covers the same benefits with every insurance company. For most people new to Medicare in 2027, the choice comes down to Plan G, Plan N or High-Deductible Plan G.

Medicare Supplement plans, also called Medigap, help pay the costs Original Medicare leaves behind, like the Part A deductible and the 20% you owe on most doctor bills. This guide compares all 10 plans for 2027, shows the new CMS figures for Plans K, L and High-Deductible G, and explains how to pick the right letter before you compare prices.

Compare Medicare Supplement plans and prices online

Speak with a licensed insurance agent

1-888-891-0229

How Medicare Supplement Plans Work

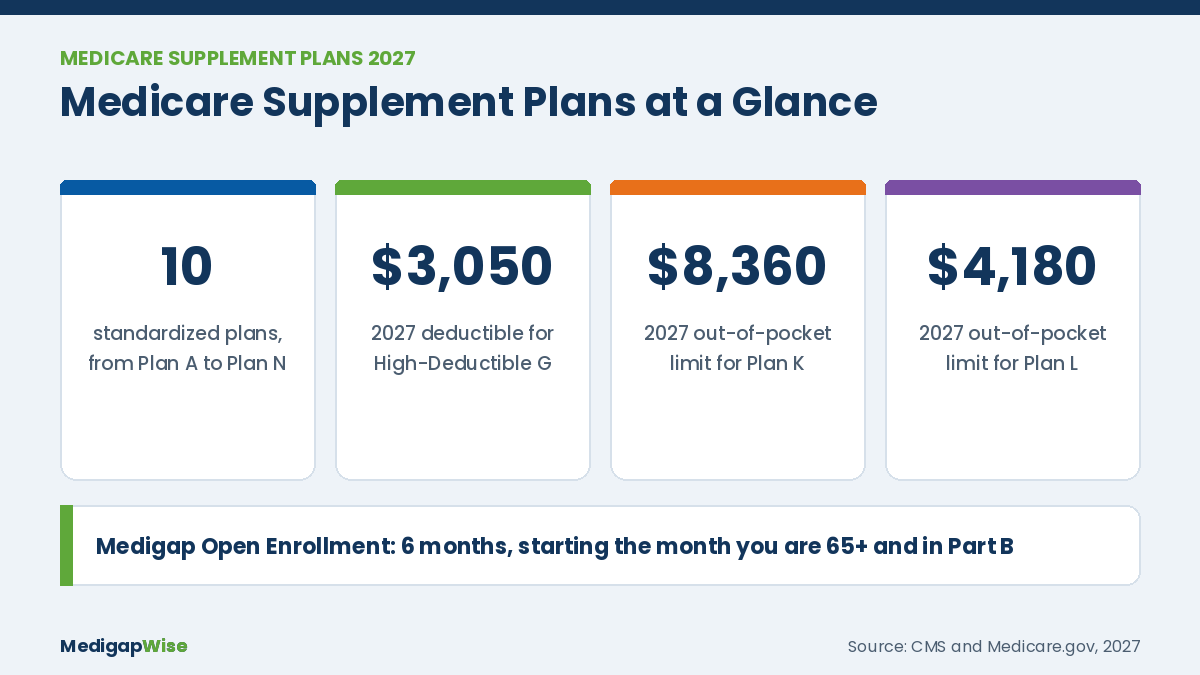
Medicare Supplement plans 2027 at a glance: 10 standardized plans, $3,050 High-Deductible G deductible, $8,360 Plan K and $4,180 Plan L out-of-pocket limits

Original Medicare (Part A and Part B) pays most of your hospital and medical costs, but not all of them. You still owe deductibles, coinsurance and copayments, and there is no yearly limit on what you can spend. A Medicare Supplement plan steps in after Medicare pays its share and covers some or all of what is left.

✔

You must have Medicare Part A and Part B to buy a Medicare Supplement plan
✔

Plans are standardized by letter, so Plan G covers the same benefits with every insurance company
✔

You can see any doctor or hospital in the U.S. that accepts Medicare, with no network and no referrals
✔

Your plan is guaranteed renewable as long as you pay the premium
✔

Each person needs their own policy, since Medicare Supplement plans do not cover spouses

The best time to buy is your Medigap Open Enrollment Period, the 6 months that start the first month you are 65 or older and enrolled in Part B. During that window, insurance companies cannot deny you or charge more because of your health. Learn more at Medicare.gov.

Plan G, Plan N and High-Deductible Plan G

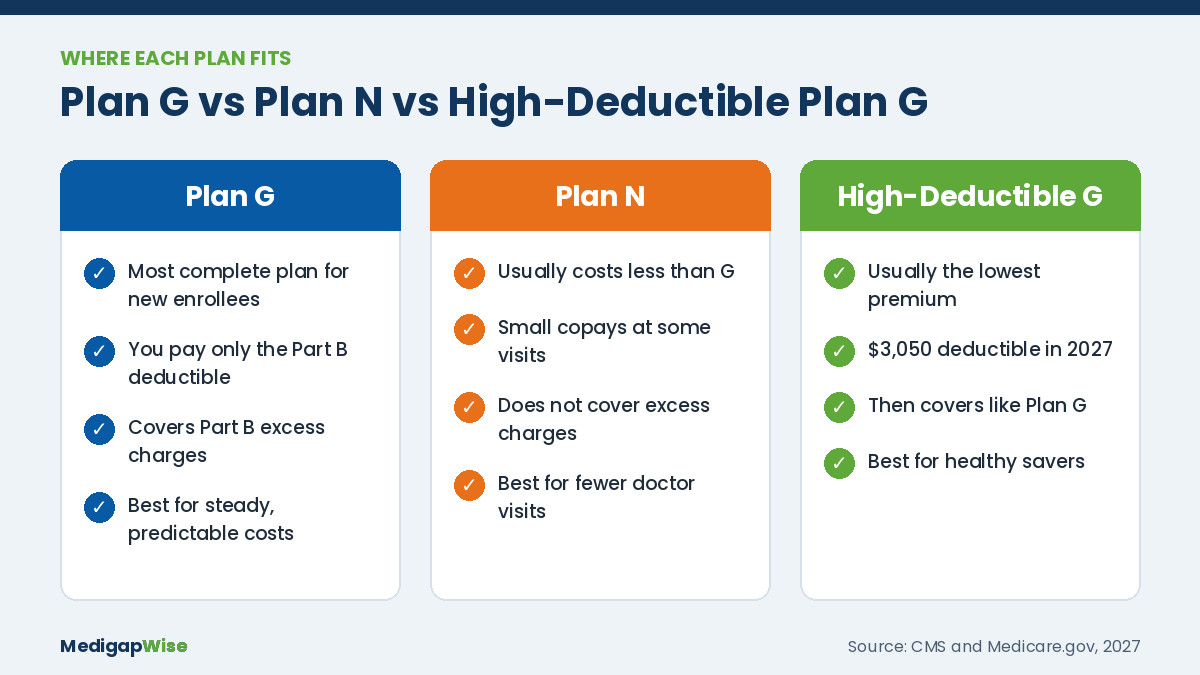
Medicare Supplement Plan G vs Plan N vs High-Deductible Plan G comparison showing who each plan fits best in 2027

If you became eligible for Medicare on or after January 1, 2020, these three plans are where most comparisons start. They cover the same hospital benefits. The differences are how much you pay upfront in premium versus how much you pay when you get care.

Plan G

✔Most complete plan for new enrollees
✔You pay only the Part B deductible
✔Covers Part B excess charges
✔Best for predictable yearly costs

Plan N

✔Usually costs less than Plan G
✔Up to $20 office and $50 ER copays
✔Does not cover excess charges
✔Best if you see doctors less often

High-Deductible G

✔Usually the lowest premium
✔$3,050 deductible in 2027
✔Then pays like regular Plan G
✔Best for healthy people who can save

Plan G usually costs about $40 to $50 a month more than Plan N at the same age. See average premiums by age in our guide to Medicare Supplement plans cost.

Good to know: The High-Deductible Plan G deductible rises to $3,050 in 2027, up from $2,950 in 2026. Until you meet it, you pay Medicare-approved costs yourself.

Watch for excess charges: Doctors who do not accept Medicare assignment can bill up to 15% above the Medicare-approved amount. Plan G covers these charges and Plan N does not. Most doctors accept assignment, so this rarely matters, but it is worth checking if you see specialists often.

Compare Medicare Supplement plan prices in your ZIP code

Or speak with a licensed insurance agent

1-888-891-0229

All 10 Medicare Supplement Plans Compared for 2027

Here is what each Medicare Supplement plan pays once Original Medicare has paid its share. Plans G and N are highlighted because they are the most common choices for new enrollees.

Plan Part A deductible Part B coinsurance Skilled nursing coinsurance Part B deductible Part B excess charges Foreign travel emergency Out-of-pocket limit
Plan A — ✔ — — — — None
Plan B ✔ ✔ — — — — None
Plan C* ✔ ✔ ✔ ✔ — 80% None
Plan D ✔ ✔ ✔ — — 80% None
Plan F* ✔ ✔ ✔ ✔ ✔ 80% None
Plan G ✔ ✔ ✔ — ✔ 80% None
Plan K 50% 50% 50% — — — $8,360
Plan L 75% 75% 75% — — — $4,180
Plan M 50% ✔ ✔ — — 80% None
Plan N ✔ ✔ (copays) ✔ — — 80% None

✔ = 100% covered. All 10 plans cover Part A coinsurance and hospital costs for 365 extra days, plus the first 3 pints of blood and Part A hospice coinsurance (Plan K at 50%, Plan L at 75%). *Plans C and F are only available to people eligible for Medicare before January 1, 2020. Plan N copays: up to $20 for some office visits and up to $50 for ER visits that do not lead to an admission.

Plans K and L work differently from the others. They pay part of your costs, and once you reach the yearly out-of-pocket limit, they pay 100% for the rest of the year. Those limits are $8,360 for Plan K and $4,180 for Plan L in 2027, up from $8,000 and $4,000 in 2026.

Plan F and Plan C: Who Can Still Buy Them

Since January 1, 2020, Medicare Supplement plans sold to new Medicare enrollees cannot cover the Part B deductible. That rule closed Plan F, High-Deductible Plan F and Plan C to anyone who became eligible for Medicare on or after that date.

✔

Eligible before January 1, 2020: you can still buy or keep Plan F, High-Deductible Plan F or Plan C, even if you did not enroll in Medicare at the time
✔

Eligible on or after January 1, 2020: Plan G is the closest option, and the only difference from Plan F is that you pay the Part B deductible
✔

Already have Plan F: you can keep it as long as you pay your premium

Because Plan F no longer takes new enrollees under 65, its pool of members is getting older. Many people already on Plan F compare its premium to Plan G, since the yearly savings can be more than the Part B deductible.

What Medicare Supplement Plans Do Not Cover

Medicare Supplement plans only pay for services Original Medicare covers. If Medicare does not pay for something, your Medicare Supplement plan will not either. That includes routine checkups, so see whether Medicare Supplement plans cover annual physicals before your next visit.

✘ Prescription drugs✘ Routine dental✘ Routine vision and eyeglasses✘ Hearing aids✘ Long-term custodial care✘ Private-duty nursing

For prescriptions, most people add a separate Medicare Part D plan. In 2027, Part D out-of-pocket drug costs are capped at $2,400 for the year, and the Part D deductible can be no higher than $700. For dental, vision and hearing, a standalone policy can fill the gap.

Medicare Supplement vs Medicare Advantage

Medigap and Medicare Advantage are two different ways to get Medicare coverage, and you cannot have both at the same time.

Medicare Supplement + Part D

✔Any doctor that accepts Medicare
✔Low or no costs when you get care
✔Monthly premium for each plan
✔No referrals or networks

Medicare Advantage

✔Usually a network of doctors
✔Copays as you use care
✔Often low or $0 premium
✔Yearly out-of-pocket limit

Medigap usually costs more each month but makes your costs predictable and lets you see any provider that takes Medicare. If you are weighing both, a licensed insurance agent at MedigapWise can compare your options side by side at no cost.

Timing matters: If you start with Medicare Advantage and later want Medigap, you may have to answer health questions, and you could be turned down. Your first Medigap Open Enrollment Period is the safest time to buy.

How to Choose a Medicare Supplement Plan

1
Check your eligibility date. If you were eligible for Medicare before 2020, Plan F and Plan C are still options. If not, start with Plan G.
2
Think about how often you see doctors. Frequent visits and specialists usually point to Plan G. Fewer visits can make Plan N a better value.
3
Decide how much risk you can take. If you could cover a $3,050 deductible in a bad year, High-Deductible Plan G can lower your premium. Many people pair it with hospital indemnity insurance for seniors to help cover the deductible.
4
Compare insurance companies, not just plans. The same plan letter can vary a lot in price, and rate increase history matters over time. See our guide to the best Medicare Supplement companies.
5
Buy during your open enrollment window. Your 6-month Medigap Open Enrollment Period guarantees you can buy any plan without health questions.

The Bottom Line

Pick the plan letter that matches your health and budget, then compare insurance companies on price. A licensed insurance agent can show you Plan G, Plan N and High-Deductible Plan G prices from several companies at no cost.

See Medicare Supplement prices in your area

Speak with a licensed insurance agent

1-888-891-0229

Medicare Supplement Plans 2027 — Frequently Asked Questions

➤ What are Medicare Supplement plans?

Medicare Supplement plans, also called Medigap plans, are private insurance policies that help pay costs Original Medicare leaves behind, such as deductibles, coinsurance and copayments. They only work with Original Medicare, not Medicare Advantage.

➤ How many Medicare Supplement plans are there in 2027?

There are 10 standardized Medicare Supplement plans in most states, labeled A, B, C, D, F, G, K, L, M and N. Plan F and Plan G also come in high-deductible versions. Massachusetts, Minnesota and Wisconsin standardize their plans differently.

➤ What is the most popular Medicare Supplement plan?

Plan G is the most popular choice for people new to Medicare. After you pay the Part B deductible, it covers your share of Medicare-approved costs for the rest of the year, including Part B excess charges.

➤ What is the difference between Plan G and Plan N?

Plan G covers Part B excess charges and has no copays after the Part B deductible. Plan N usually costs less, but you may pay up to $20 for some office visits, up to $50 for emergency room visits that do not lead to an admission, and any Part B excess charges.

➤ What is the High-Deductible Plan G deductible for 2027?

The High-Deductible Plan G deductible is $3,050 in 2027, up from $2,950 in 2026. Once you meet it, the plan pays like regular Plan G for the rest of the calendar year.

➤ Can I still buy Medicare Supplement Plan F in 2027?

Only if you were eligible for Medicare before January 1, 2020. If you turned 65 or first qualified for Medicare on or after that date, you cannot buy Plan F, Plan C or High-Deductible Plan F.

➤ Are Medicare Supplement plans the same from every insurance company?

Yes. Every plan with the same letter covers the same benefits, no matter which insurance company sells it. Premiums, customer service and rate increase history are what differ between companies.

➤ When is the best time to buy a Medicare Supplement plan?

During your Medigap Open Enrollment Period, the 6 months that start the first month you are 65 or older and enrolled in Part B. Insurance companies cannot turn you down or charge you more for health conditions during that window.

➤ Do Medicare Supplement plans cover prescription drugs?

No. Medicare Supplement plans sold today do not include drug coverage. Most people pair their Medicare Supplement plan with a separate Medicare Part D plan, and Part D out-of-pocket costs are capped at $2,400 in 2027.

➤ Can I have a Medicare Supplement plan and Medicare Advantage at the same time?

No. Medigap only works with Original Medicare. If you join a Medicare Advantage plan, a Medigap policy cannot pay any of your costs, and it is illegal for anyone to sell you one while you are enrolled in Medicare Advantage.
Free Medigap Price Comparison

Call a Licensed Agent Now

Compare Plan G, Plan N and more from several insurance companies in one call.

☎ 1-888-891-0229

No cost, no obligation to enroll

Compare plans & benefits in your area

Or speak with a licensed insurance agent

1-888-891-0229