Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated November 11, 2026
Key Takeaway
Medicare vs Medigap isn’t an either-or choice: Original Medicare (Parts A and B) is the federal program that pays your claims first, and a Medigap policy, also called a Medicare Supplement, is private insurance you add on top to pay the deductibles, daily hospital charges and 20% coinsurance Medicare leaves behind. You can’t buy Medigap without both Part A and Part B, and it never covers prescription drugs.
2027 by the Numbers
$1,736
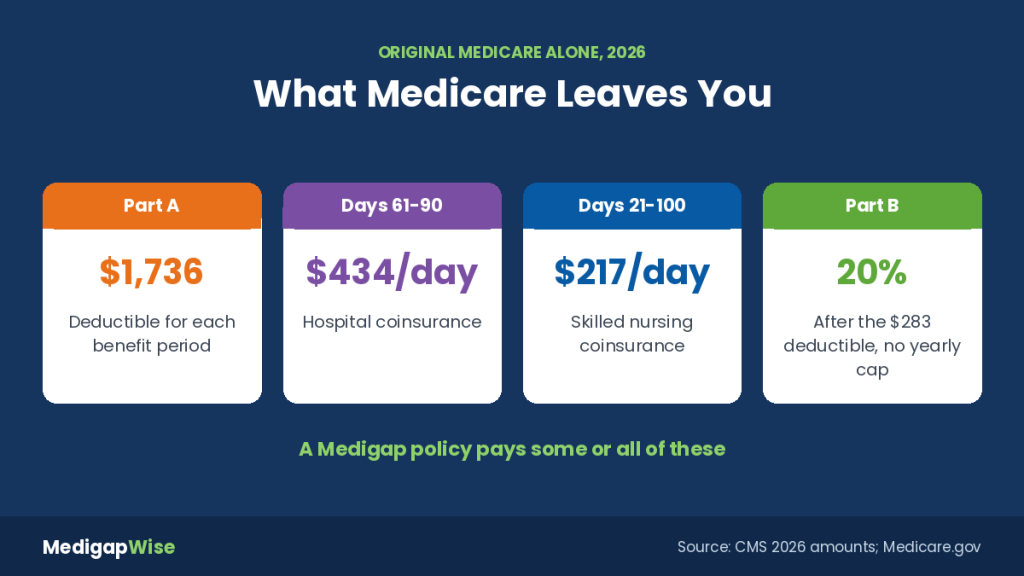
2026 Part A deductible, owed again with each new benefit period (CMS)
No cap
Yearly out-of-pocket limit in Original Medicare without supplemental coverage (Medicare.gov)
$66,836
Our total of Part A cost sharing for a 150-day hospital stay at 2026 CMS rates
$3,050
2027 deductible for High-Deductible Plan G (CMS)
People type “Medicare vs Medigap” expecting two products to weigh against each other. That framing trips up a lot of new enrollees. Original Medicare is the coverage itself. Medigap is a secondary policy that only works when Original Medicare is already in place, and it pays nothing on its own.
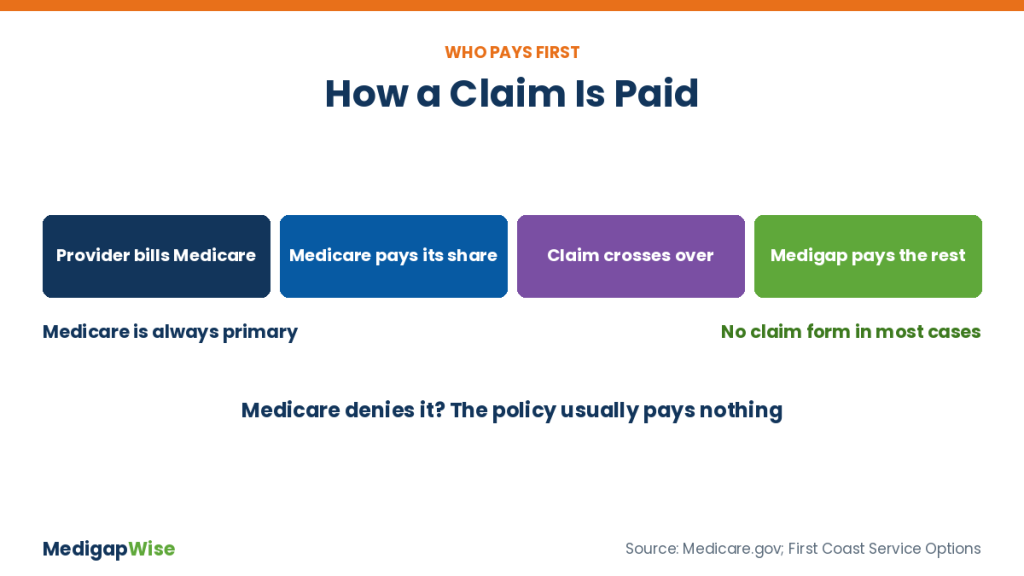
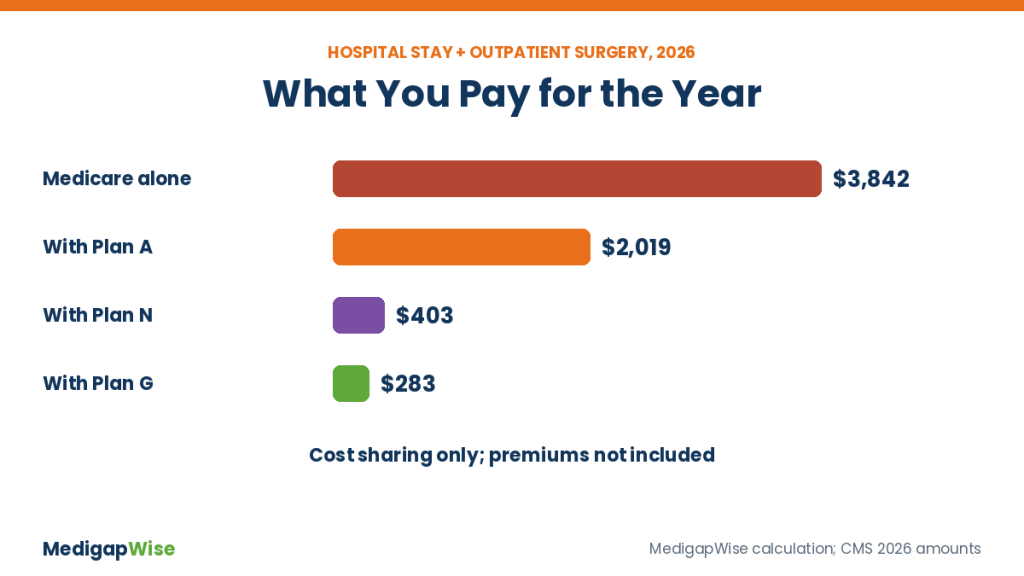
So the useful comparison is Original Medicare alone versus Original Medicare with a supplement. Below we list every cost Medicare leaves you with, show which plan letters pay each one, explain how a bill moves from Medicare to the insurer, and price one realistic year both ways. CMS hadn’t published 2027 Part A and Part B amounts when this page went live on November 11, 2026, so dollar figures are 2026 amounts, labeled as such.