Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated November 6, 2026
Key Takeaway
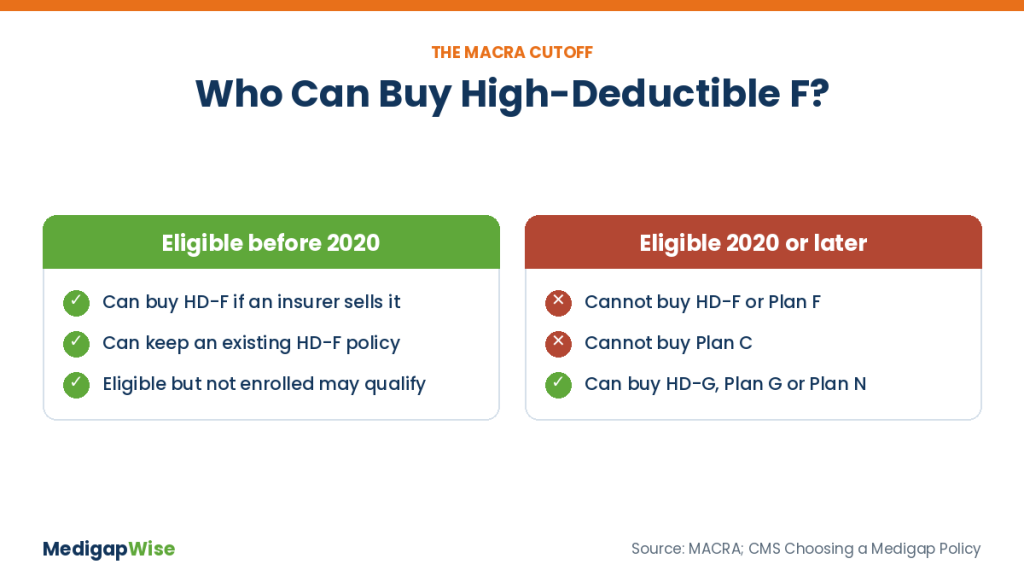
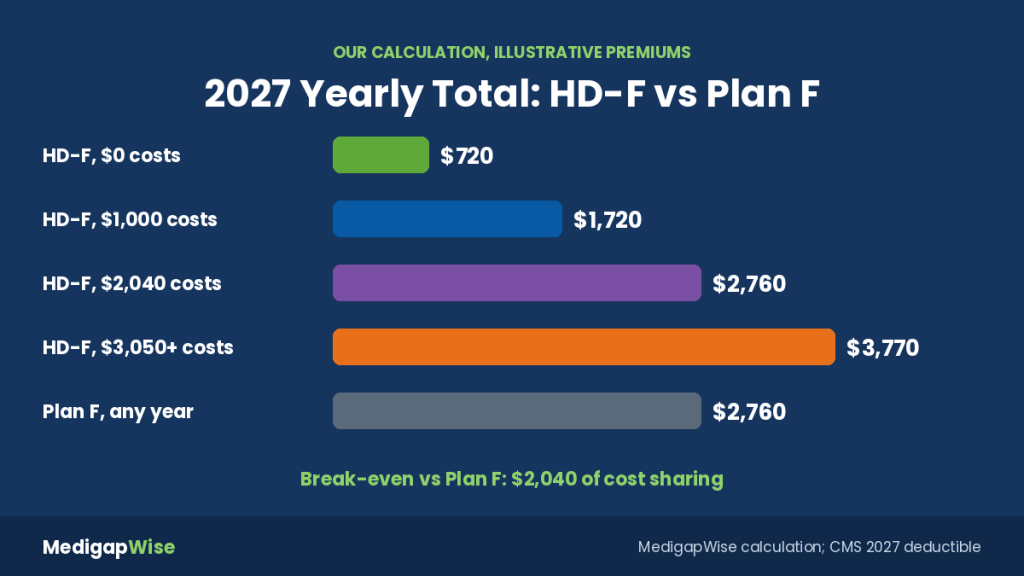
High-Deductible Plan F is a Medicare Supplement plan that only people eligible for Medicare before January 1, 2020 can buy; in 2027 it pays nothing until you’ve paid $3,050 in Medicare-covered costs, then covers 100% of them, including the Part B deductible, for the rest of the year.
2027 by the Numbers
$3,050
2027 High-Deductible F, G and J deductible, effective Jan. 1, 2027 (CMS, Oct. 2026)
3.40%
CPI-U rise that moved the amount up from $2,950 in 2026 (CMS)
$283
2026 Part B deductible, which counts toward the HD-F amount; 2027 figure not yet released (CMS)
1/1/2020
Medicare eligibility cutoff for buying any version of Plan F (MACRA)
Before anything else, High-Deductible Plan F comes down to a date. If your Medicare eligibility started on or after January 1, 2020, no insurer can sell it to you, no matter your age, health or state. If your eligibility started earlier, it’s still on the table, and for some people it’s one of the cheapest ways to cap a bad medical year.
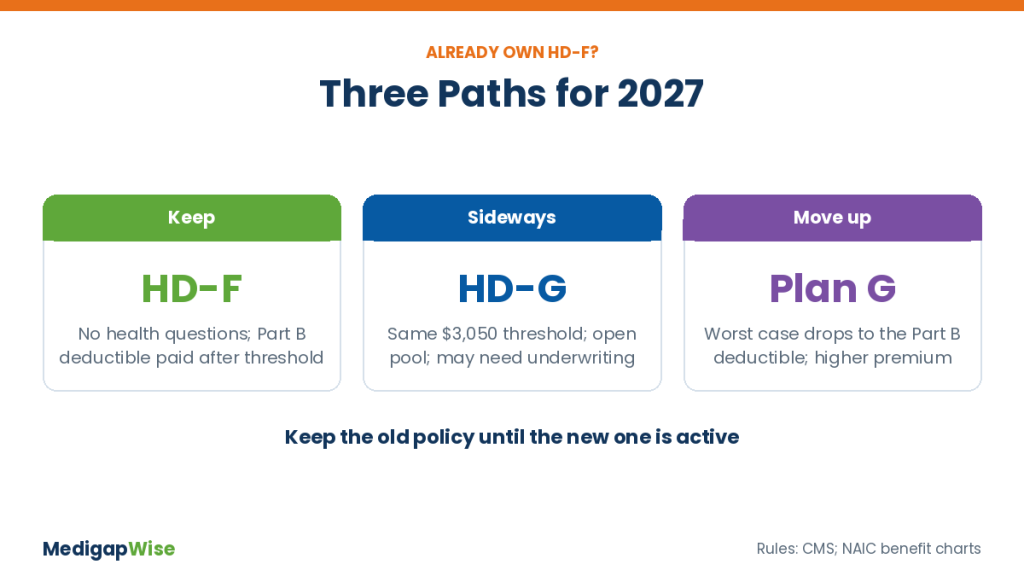
This guide is for that second group: people deciding whether to buy HD-F, and people who already own it and wonder whether to keep it. It covers eligibility, the 2027 amount, a small difference from High-Deductible Plan G, our break-even table and closed-pool pricing.