Speak with a licensed insurance agent

1-888-891-0229

High-Deductible Plan G 2027: The $3,050 Deductible, Costs and Break-Even Math

Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated October 27, 2026

Key Takeaway

High-Deductible Plan G is a Medicare Supplement plan that pays nothing until you’ve paid $3,050 in Medicare-covered costs in 2027, then pays the same benefits as regular Plan G for the rest of the year. In exchange, its monthly premium is usually far lower than regular Plan G.

2027 by the Numbers

$3,050

2027 deductible for High-Deductible Plans G and F (CMS)

$2,950

2026 deductible; 2027 rose 3.40% with the CPI-U (CMS)

$283

2026 Part B deductible, which counts toward the $3,050; 2027 amount due in November (CMS)

2020

First year High-Deductible G was sold to people new to Medicare (CMS)

High-Deductible Plan G trades a big yearly deductible for a small monthly premium. In a bad year, your costs stop at a fixed ceiling.

CMS set the 2027 deductible at $3,050 in its October 2026 announcement. Below: how that number is set, what counts toward it, premiums and our own break-even scenarios.

Get High-Deductible Plan G quotes in your area

Speak with a licensed insurance agent

1-888-891-0229

What Is High-Deductible Plan G?

High-Deductible Plan G is the high-deductible version of standardized Medigap Plan G. After the deductible is met, it pays exactly what regular Plan G pays: the Part A deductible and coinsurance, Part B coinsurance, Part B excess charges, skilled nursing and hospice coinsurance, blood and 80% of foreign travel emergencies. Before the deductible is met, it pays nothing.

CMS confirms that High-Deductible G has been available to people new to Medicare on or after January 1, 2020. It replaced High-Deductible Plan F for that group, because federal law stopped the sale of Plans C and F to anyone newly eligible from 2020 on. High-Deductible F still exists, but only for people eligible for Medicare before 2020.

For every plan letter side by side, see our guide to Medicare Supplement plans.

The 2027 Deductible: $3,050, and How CMS Sets It

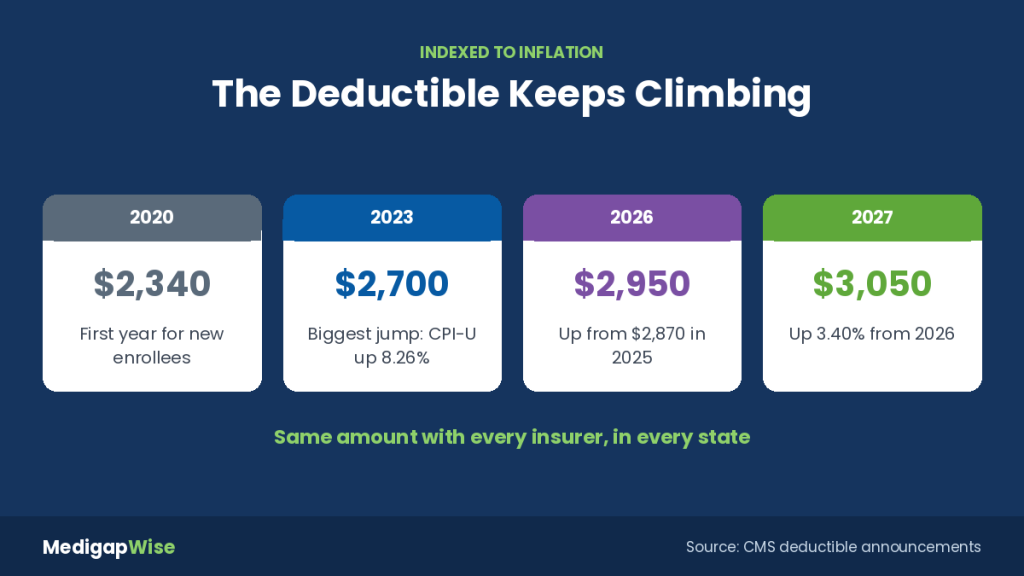
High-Deductible Plan G deductible by year: $2,340 in 2020, $2,700 in 2023, $2,950 in 2026 and $3,050 in 2027

The deductible is set by federal law and is the same with every insurer and in every state. The starting point was $1,500 for 1998 and 1999. Each year since, CMS raises it by the change in the Consumer Price Index for all urban consumers (CPI-U) and rounds to the nearest $10.

For 2027, the CPI-U rose 3.40%, which took the deductible from $2,950 in 2026 to $3,050. The same amount applies to High-Deductible Plan F and the old High-Deductible Plan J. Here’s how it has climbed since High-Deductible G opened to new enrollees:

✔
2020: $2,340  ·  2021: $2,370  ·  2022: $2,490
✔
2023: $2,700, the biggest jump, after an 8.26% CPI-U increase
✔
2024: $2,800  ·  2025: $2,870  ·  2026: $2,950
✔
2027: $3,050, up $710 (about 30%) from 2020

Plan for it to rise: Because the deductible is tied to inflation, your worst-case year gets a little more expensive every January even if your premium doesn’t change.

What Counts Toward the $3,050 Deductible

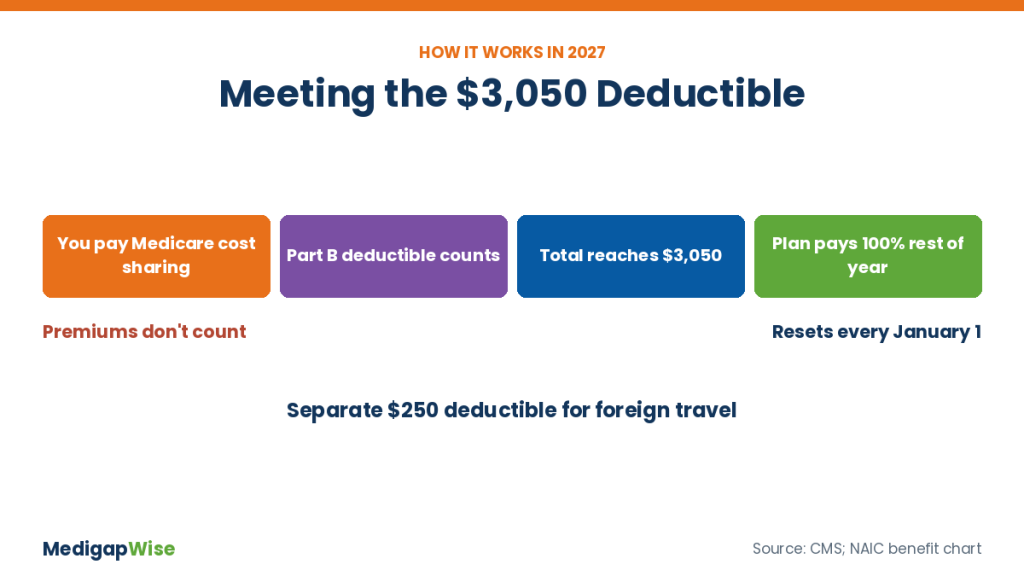
How the High-Deductible Plan G deductible works in 2027: Medicare cost sharing and the Part B deductible count toward $3,050, then the plan pays 100%

CMS describes the deductible as your yearly out-of-pocket expenses, not counting premiums. The NAIC’s standardized benefit chart adds that it includes the Part B deductible and the expenses the policy would ordinarily pay. In practice that means:

Counts

✔The Part B deductible ($283 in 2026)
✔The Part A hospital deductible ($1,736 per benefit period in 2026)
✔Your 20% Part B coinsurance
✔Skilled nursing coinsurance

Doesn’t count

✔Your Medigap and Part B premiums
✔Services Medicare doesn’t cover, like routine dental
✔The separate $250 foreign travel deductible
✔Part D drug costs

Excess charges: Plan G pays Part B excess charges, the up-to-15% that doctors who don’t accept Medicare assignment can add. Since that’s a cost the policy would ordinarily pay, excess charges you pay before the deductible is met generally count toward it. Insurers process claims differently, so confirm with yours if you see a doctor who doesn’t take assignment.

Your ceiling: Once you’ve paid $3,050 in counted costs in 2027, the plan pays 100% of Medicare-approved costs for the rest of the calendar year. The count resets every January 1.

Questions? Talk to a Licensed Agent

We compare Plan G, Plan N and more from several insurance companies at no cost to you.

☎ 1-888-891-0229

No cost, no obligation to enroll

High-Deductible Plan G Cost: Premiums vs Regular Plan G

Because the insurer pays nothing until you reach $3,050, High-Deductible G premiums are usually much lower than regular Plan G from the same company, often a fraction of the price. The exact gap depends on the same things that set any Medigap premium:

✔
Your age and how the company prices: attained-age, issue-age or community-rated, depending on the insurer and state
✔
Your ZIP code, gender and tobacco use
✔
Discounts: many companies offer a household discount that also applies to High-Deductible G
✔
Which companies sell it: not every insurer files a High-Deductible G in every state, so your choices can be narrower than for regular Plan G

Check a company’s rate record in our guide to Medicare Supplement rate increases and pricing basics in Medicare Supplement plans cost.

Compare High-Deductible G and Plan G prices

Speak with a licensed insurance agent

1-888-891-0229

Break-Even Math: Three 2027 Scenarios (Our Calculation)

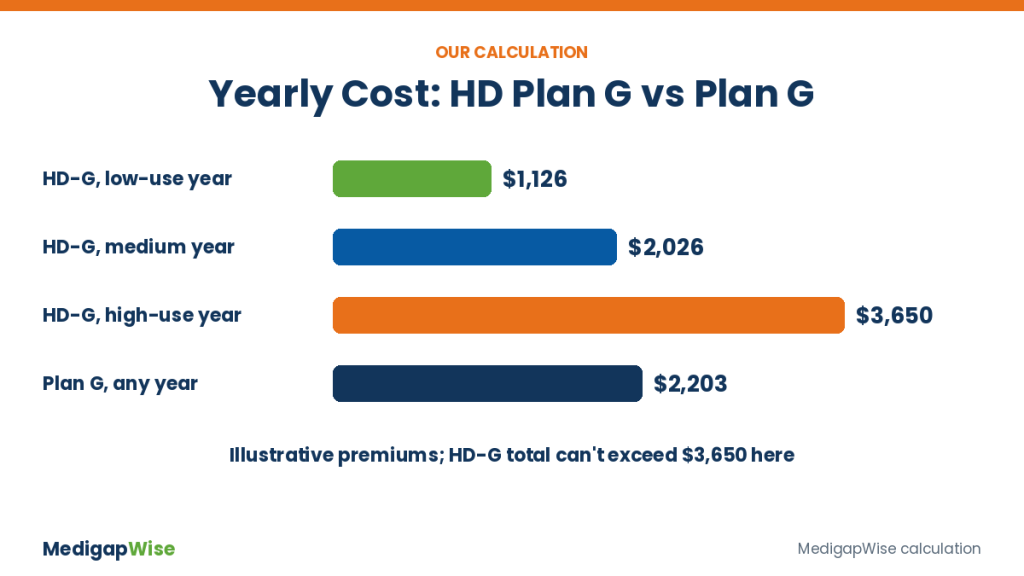
Our calculation of yearly High-Deductible Plan G costs in low, medium and high-use years compared with regular Plan G

To see where High-Deductible G wins and loses, we ran three yearly scenarios. Our assumptions: illustrative premiums of $50 a month for High-Deductible G, $160 for Plan G and $125 for Plan N; the $3,050 2027 deductible; and CMS’s 2026 Part A ($1,736) and Part B ($283) deductibles, since the 2027 amounts aren’t out yet. Totals are premiums plus your share of Medicare-covered costs. For Plan N we counted $20 office copays: 4 in the light year, 10 plus a $50 ER copay in the medium year, and 12 in the high year, where the ER copay is waived because you’re admitted.

Yearly total (our calculation) High-Deductible G Plan G Plan N
Premiums only $600 $1,920 $1,500
Low use: $1,500 of Part B care $1,126 $2,203 $1,863
Medium use: $6,000 of Part B care, 1 ER visit $2,026 $2,203 $2,033
High use: hospital stay + $15,000 of Part B care $3,650 $2,203 $2,023

With these premiums, High-Deductible G saves up to $1,320 a year over Plan G and costs at most $1,447 more in a bad year ($3,050 + $600, minus $2,203). It stays ahead of Plan G as long as your counted costs stay under about $1,603, which is the Part B deductible plus the $1,320 premium savings.

Run your own numbers: take the yearly premium difference from your quotes, add the Part B deductible, and compare that with how much Medicare cost sharing you expect. A smaller premium gap moves the break-even point down fast. Plan N’s copays work differently; see our Medicare Supplement Plan N guide for that math.

Who High-Deductible Plan G Fits, and Who It Doesn't

High-Deductible G works best as protection against a big year rather than as a way to prepay routine care. It tends to fit if you:

✔
Are healthy, take few prescriptions and see the doctor mostly for checkups
✔
Have savings set aside that could cover $3,050 without strain
✔
Want the excess charge coverage and nationwide doctor choice of Plan G at a lower monthly cost
✔
Would rather bank the premium difference each year than pay for coverage you rarely use

Think twice if: you have an ongoing condition, regular specialist visits or planned surgery, or a $3,050 year would strain your budget.

How to Buy or Switch to High-Deductible Plan G

1
Buy during open enrollment if you can. Your 6-month Medigap open enrollment period starts the month you’re 65 or older and enrolled in Part B. During it, companies can’t decline you or charge more for your health.
2
Quote High-Deductible G and Plan G together. Ask each company for both, so you can see the real premium gap and run the break-even math above.
3
Switching from regular Plan G or Plan F? Moving to High-Deductible G means less coverage, but outside a guaranteed issue right most states still let the company ask underwriting questions.
4
Keep your old policy until the new one is active. Cancel only after the High-Deductible G policy is approved and in force.

Weigh the way back, too. Moving up from High-Deductible G to regular Plan G later usually means passing medical underwriting, and a new diagnosis could keep you on the high-deductible version. Timing rules are in our guide to Medicare Supplement open enrollment, and our list of the best Medicare Supplement companies can help narrow insurers.

Talk to an agent about High-Deductible Plan G

Speak with a licensed insurance agent

1-888-891-0229

Keep Reading

Medicare Supplement Plan G 2027: every Plan G benefit with CMS dollar amounts, a full-year cost example and who the standard plan fits.

High-Deductible Plan G — Frequently Asked Questions

➤ What is the High-Deductible Plan G deductible for 2027?

$3,050, effective January 1, 2027, according to CMS. It was $2,950 in 2026 and rises each year with the CPI-U.

➤ Does the Part B deductible count toward the High-Deductible Plan G deductible?

Yes. What you pay toward the Part B deductible counts toward the $3,050, so you aren’t paying it on top of the High-Deductible G deductible.

➤ Do premiums count toward the $3,050?

No. Neither your Medigap premium nor your Part B premium counts. Only your share of Medicare-covered costs does.

➤ What happens after I meet the deductible?

The plan pays 100% of Medicare-approved costs it covers for the rest of that calendar year, just like regular Plan G after the Part B deductible. The deductible starts over on January 1.

➤ Is High-Deductible Plan G worth it?

It can be if you’re healthy and could pay $3,050 in a bad year. In our scenarios, it saved $1,320 in a light year but cost $1,447 more than Plan G in a year with a hospital stay. Your quotes decide the math.

➤ Can I still buy High-Deductible Plan F in 2027?

Only if you were eligible for Medicare before January 1, 2020. Everyone newly eligible since then can choose High-Deductible Plan G instead. Both have the same $3,050 deductible in 2027.

➤ Does High-Deductible Plan G cover foreign travel emergencies?

Yes, at 80% up to plan limits, like regular Plan G. Foreign travel has its own separate $250 yearly deductible, which doesn’t count toward the $3,050.

➤ Can I switch from High-Deductible Plan G to regular Plan G later?

You can apply any time, but outside open enrollment or a guaranteed issue right, most states let the insurer ask health questions and decline you. Keep your current policy until the new one is approved.

Free Medigap Price Comparison

Call a Licensed Agent Now

Compare Plan G, Plan N and more from several insurance companies in one call.

☎ 1-888-891-0229

No cost, no obligation to enroll