Speak with a licensed insurance agent

1-888-891-0229

Hospital Indemnity Insurance for Seniors: How It Works with Medicare in 2027


Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated October 21, 2026

Key Takeaway

Hospital indemnity insurance pays you cash when you are admitted to the hospital. For seniors, it pairs best with High-Deductible Plan G, Plan N or a Medicare Advantage plan, where a hospital stay can still leave you with real out-of-pocket costs.

A hospital stay is one of the most expensive things that can happen on Medicare. Depending on your coverage, you could still owe a Part A deductible, a high plan deductible or daily hospital copays. Hospital indemnity insurance pays a set cash benefit when you are admitted, so you have money to cover those costs. This guide explains how it works with Medicare, who it makes sense for and how to compare policies.

Compare Medicare Supplement and hospital indemnity plans

Speak with a licensed insurance agent

1-888-891-0229

How Hospital Indemnity Insurance Works

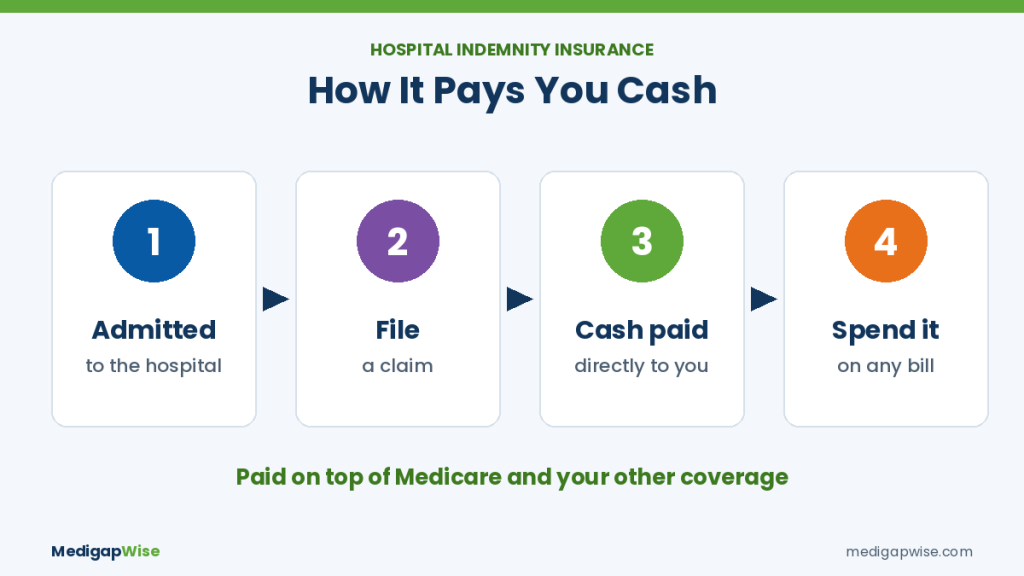
How hospital indemnity insurance for seniors works: admitted to the hospital, file a claim, cash paid directly to you

Hospital indemnity insurance is a supplemental policy from a private insurance company. It does not replace your Medicare coverage. It adds a cash benefit on top of it.

1
You are admitted to the hospital. Most policies pay for an inpatient stay, and some also pay for observation or outpatient care.
2
You file a claim. You send the insurance company proof of the hospital stay.
3
The company pays you directly. You get a fixed amount, such as a set dollar amount per day or per admission.
4
You decide how to spend it. Use it for deductibles, copays, travel or household bills.

Good to know: Benefits are paid on top of what Medicare and your other coverage pay. They do not reduce your Medicare benefits.

What a Hospital Stay Can Cost on Medicare

Original Medicare Part A has its own deductible and daily coinsurance for longer stays. Here is what you could owe without other coverage, using 2026 amounts. CMS has not announced the 2027 Part A amounts yet.

Part A hospital cost 2026 amount
Deductible, each benefit period $1,736
Days 1 to 60 $0 after the deductible
Days 61 to 90 $434 a day
Lifetime reserve days $868 a day

Source: CMS 2026 Medicare Part A amounts. A benefit period starts when you are admitted and ends after 60 days in a row out of the hospital or skilled nursing facility.

Most Medicare Supplement plans cover these Part A costs, which is why the right pairing matters.

Which Seniors Benefit Most

High-Deductible Plan G

✔$3,050 deductible in 2027
✔Lower monthly premium
✔Cash benefit can cover the deductible

Plan N

✔Part B deductible applies
✔Copays for some office and ER visits
✔Extra cash for hospital stays

Medicare Advantage

✔Daily copays for hospital stays
✔Costs add up on longer stays
✔Helps cover copays up to the plan limit

Already have Plan G? Standard Plan G covers almost all hospital costs after the Part B deductible, so most people with Plan G do not need hospital indemnity insurance.

Hospital Indemnity with High-Deductible Plan G

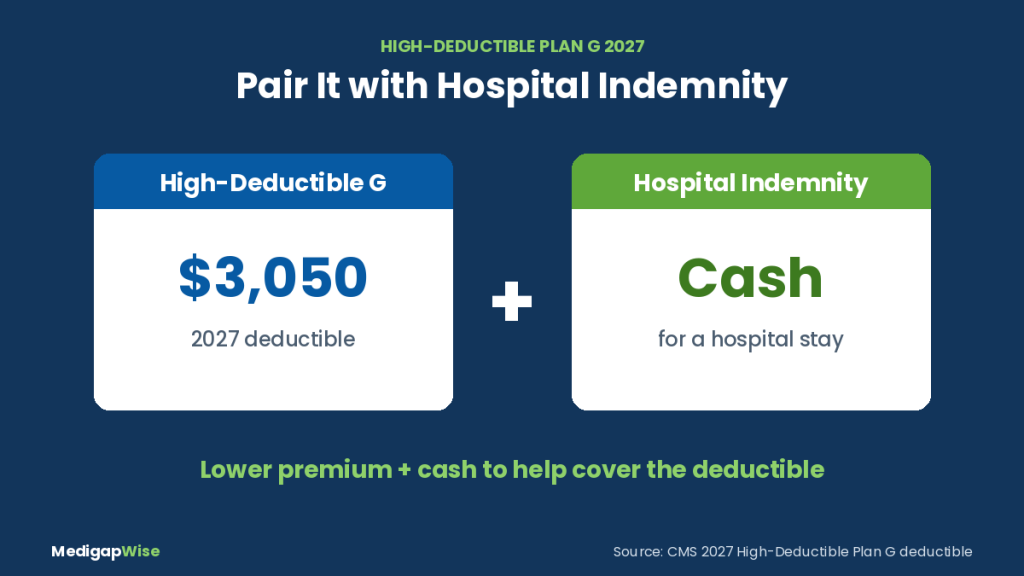
High-Deductible Plan G with a $3,050 2027 deductible paired with hospital indemnity insurance

High-Deductible Plan G has the same benefits as Plan G after you meet a $3,050 deductible in 2027. Its premium is usually much lower. The risk is a big bill in a year with a hospital stay.

A hospital indemnity policy can pay a cash benefit for that stay, which helps cover the deductible. Together, the two can cost less than standard Plan G while keeping your risk in check. Compare premiums on our Medicare Supplement costs page.

The Bottom Line

Compare the yearly premium of High-Deductible Plan G plus a hospital indemnity policy against standard Plan G. If the pair costs less and the cash benefit covers most of the deductible, it can be the smarter buy.

What Hospital Indemnity Policies Can Cover

Benefits vary by insurance company and state. Policies may include:

✔
A daily or per-admission benefit for inpatient hospital stays
✔
Intensive care unit (ICU) benefits
✔
Skilled nursing facility stays after a hospital stay
✔
Outpatient surgery and emergency room visits
✔
Ambulance and observation stays

See hospital indemnity options in your area

Speak with a licensed insurance agent

1-888-891-0229

Things to Check Before You Buy

✔
Health questions: many policies can decline you based on your health
✔
Waiting periods and pre-existing condition limits in the first months
✔
How many days or admissions the policy pays each year
✔
Whether the benefit is per day, per admission or both
✔
Whether the premium can rise as you age

How to Compare Hospital Indemnity Plans

1
Start with your Medicare coverage. Know your hospital deductible or daily copays.
2
Pick a benefit amount. Choose a cash benefit that covers most of what you would owe.
3
Compare insurance companies. Companies such as Mutual of Omaha, Medico, Aetna and Cigna offer hospital indemnity policies in many states. See how Aetna hospital indemnity insurance works for seniors.
4
Check the total yearly cost. Add the hospital indemnity premium to your Medicare Supplement premium.
5
Talk to a licensed insurance agent. An agent can compare several companies at once.

The Bottom Line

Hospital indemnity insurance is a low-cost way to protect yourself from a big hospital bill. A licensed insurance agent at MedigapWise can compare it alongside your Medicare Supplement plan at no cost.

Compare Medicare Supplement and hospital indemnity plans

Speak with a licensed insurance agent

1-888-891-0229

Hospital Indemnity Insurance for Seniors — Frequently Asked Questions

➤ What is hospital indemnity insurance for seniors?

It is a supplemental policy that pays you a set cash amount when you are admitted to the hospital, such as a fixed dollar amount per day. The money goes to you, not the hospital, and you can use it for deductibles, copays or everyday bills while you recover.

➤ Does Medicare cover hospital indemnity insurance?

No. Hospital indemnity insurance is not part of Medicare. It is sold by private insurance companies and works alongside Original Medicare, a Medicare Supplement plan or a Medicare Advantage plan.

➤ Do I need hospital indemnity insurance if I have a Medicare Supplement plan?

Most people with Plan G do not need it, because Plan G covers almost all hospital costs after the Part B deductible. It makes the most sense with High-Deductible Plan G or Plan N, or with a Medicare Advantage plan that charges daily hospital copays.

➤ How does hospital indemnity work with High-Deductible Plan G?

High-Deductible Plan G has a $3,050 deductible in 2027. A hospital indemnity policy can pay a cash benefit for a hospital stay that helps cover that deductible, so you keep the lower premium of the high-deductible plan with less risk.

➤ How much does hospital indemnity insurance cost for seniors?

Premiums depend on your age, state, the benefit amount you choose and the insurance company. Policies with a lower daily benefit cost less. A licensed insurance agent can show you prices from several companies.

➤ Can I be turned down for hospital indemnity insurance?

Yes. Many policies ask health questions, and the company can decline you or limit coverage based on your answers. Some policies have simplified underwriting with only a few questions.

➤ Does hospital indemnity pay for outpatient care?

It depends on the policy. Most pay for inpatient hospital stays. Some add benefits for outpatient surgery, emergency room visits, ambulance rides or skilled nursing stays.

➤ Can I use the money however I want?

Yes. Benefits are paid directly to you, and you can use them for medical bills, travel to the hospital, groceries, rent or anything else.

➤ Is there a waiting period on hospital indemnity insurance?

Some policies have a waiting period or a pre-existing condition limit for the first months of coverage. Check the policy details before you buy.

➤ Does it cost anything to compare hospital indemnity plans with MedigapWise?

No. Our licensed insurance agents can compare hospital indemnity policies alongside your Medicare Supplement plan at no cost, and you are never required to enroll.
Free Medigap Price Comparison

Call a Licensed Agent Now

Compare Plan G, Plan N and more from several insurance companies in one call.

☎ 1-888-891-0229

No cost, no obligation to enroll

Compare plans & benefits in your area

Or speak with a licensed insurance agent

1-888-891-0229