Speak with a licensed insurance agent

1-888-891-0229

Is Hospital Indemnity Insurance Worth It? Costs, Payouts and Who Needs It

Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated October 26, 2026

Key Takeaway

Hospital indemnity insurance is usually worth it if your Medicare plan leaves you with big hospital costs, like Medicare Advantage daily copays or a high deductible. If you have Plan G or Plan F, it is usually not worth much, because your hospital costs are already covered.

Hospital indemnity insurance is one of the most common add-ons sold to people on Medicare, and one of the most debated. Some people swear by it. Others say it is a waste of money. The truth is that it depends on what your Medicare plan already covers. Here is how to tell whether it is worth it for you, with real numbers.

Find out if hospital indemnity is worth it for you

Speak with a licensed insurance agent

1-888-891-0229

How Hospital Indemnity Insurance Works

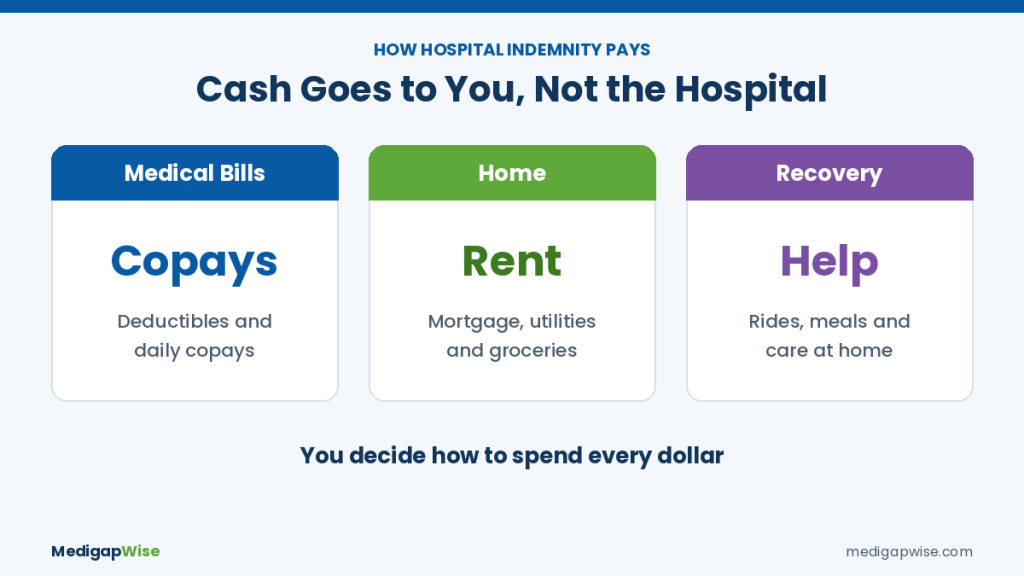
Hospital indemnity insurance pays cash to you for copays, deductibles, rent, groceries and help at home while you recover

Hospital indemnity insurance pays you a fixed amount of cash when you are admitted to the hospital. Most plans pay a daily benefit, such as $200 or $300 for each day you stay, up to a set number of days. Some pay a lump sum for each admission instead.

The cash goes straight to you, not the hospital. You can use it for your Medicare deductible, daily copays, rent, groceries or anything else. It pays on top of whatever Medicare and your other coverage pay.

Good to know: Hospital indemnity insurance is not health insurance and is not a Medicare plan. It does not replace your coverage. It adds cash on top of it.

When Hospital Indemnity Is Worth It

✔
You have Medicare Advantage with daily hospital copays, often a few hundred dollars a day for the first several days
✔
You have High-Deductible Plan G and want cash to cover the $3,050 deductible in 2027
✔
You have Original Medicare alone and face the $1,736 Part A deductible each benefit period in 2026
✔
You have little in savings to cover a surprise hospital bill
✔
You want cash for living costs while you recover, like rent or help at home

In all of these cases, one hospital stay can cost more than several years of premiums.

Free Hospital Indemnity Quote

Call a Licensed Agent Now

Get cash for hospital stays. Compare hospital indemnity plans from several insurance companies in one call.

☎ 1-888-891-0229

No cost, no obligation to enroll

When It May Not Be Worth It

✔
You have Plan G or Plan F. These cover the Part A deductible and hospital coinsurance, so there is little left to fill.
✔
You have plenty of savings and could pay a hospital bill without stress.
✔
The premium is high for your age compared with the benefit it pays.
✔
The policy excludes what you need, such as observation stays or pre-existing conditions.

If your Medicare Supplement plan already covers your hospital costs, a hospital indemnity plan mostly pays you cash for living expenses. That can still be nice to have, but it is a want, not a need.

Hospital Costs by Medicare Plan

Your Medicare coverage What a hospital stay can cost you Is hospital indemnity worth it?
Medicare Advantage Daily copays, often $300 to $400 a day for several days Often yes
High-Deductible Plan G Up to the $3,050 deductible in 2027 Often yes
Original Medicare only $1,736 Part A deductible per benefit period (2026) Often yes
Plan N Part B deductible and small copays Sometimes
Plan G or Plan F Little or nothing for the hospital Usually not

Medicare Advantage copays vary by plan and area. Part A deductible is the 2026 amount; CMS has not announced the 2027 amount yet.

The bigger the hospital cost your plan leaves you, the more a hospital indemnity plan is worth. For a full overview of how these plans fit with Medicare, see our guide to hospital indemnity insurance for seniors.

See hospital indemnity plans that fit your Medicare plan

Speak with a licensed insurance agent

1-888-891-0229

How Much Does Hospital Indemnity Insurance Cost?

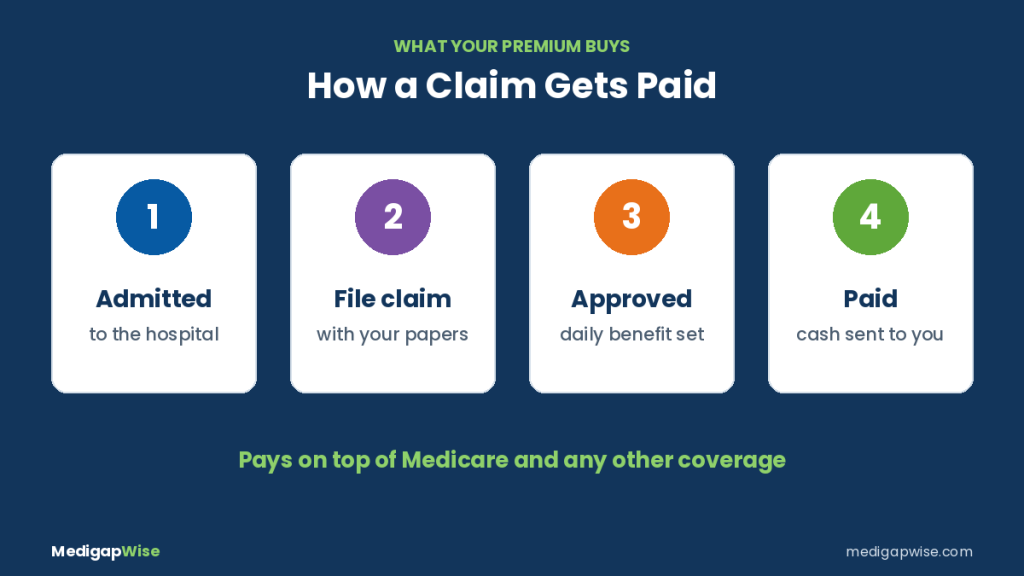
How hospital indemnity insurance claims get paid: admitted to the hospital, file a claim, benefit approved, cash sent to you

For seniors, hospital indemnity premiums often run about $20 to $80 a month. Your price depends on:

1
Your age. Premiums go up at older ages.
2
Your daily benefit. A $300-a-day plan costs more than a $100-a-day plan.
3
Covered days. More covered days per stay means a higher premium.
4
Riders. Add-ons like ambulance, outpatient surgery or cancer benefits raise the price.
5
Your state and company. Prices vary, and some companies offer a household discount.

Break-Even Example: Does It Pay Off?

Say you are 68 with a Medicare Advantage plan that charges $350 a day for days 1 to 5 in the hospital. You buy a hospital indemnity plan that pays $300 a day for $45 a month.

Yearly Cost

✔$45 a month
✔$540 a year
✔About $2,700 over 5 years

One 5-Day Stay

✔You owe $1,750 in copays
✔Plan pays you $1,500
✔You cover about $250

Break-Even

✔2 hospital days pays a full year
✔One 5-day stay covers almost 3 years
✔No stay means no payout

Example only. Premiums and copays vary by age, state, company and plan.

That is the real trade-off. If you never go to the hospital, you paid premiums for peace of mind. If you do, the plan can pay back years of premiums in a single stay.

Hospital Indemnity vs a Medicare Supplement Plan

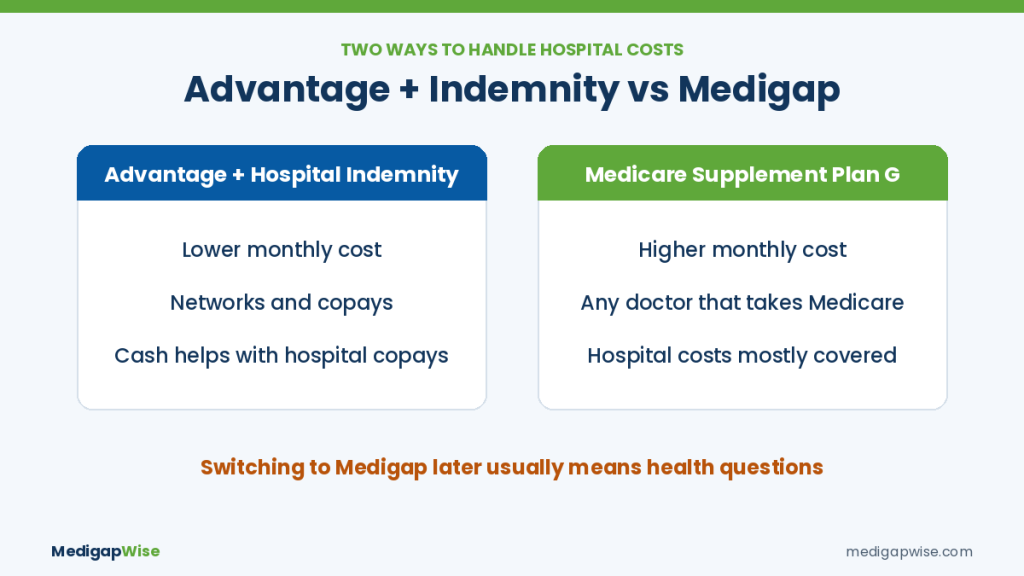
Is hospital indemnity insurance worth it: Medicare Advantage plus hospital indemnity vs Medicare Supplement Plan G compared

If you are choosing between Medicare Advantage plus hospital indemnity and a Medicare Supplement plan, think about the big picture, not just the hospital.

Medicare Advantage with a hospital indemnity plan can keep your monthly costs low, but you still have networks and copays for other care. A Medicare Supplement plan like Plan G costs more each month, but covers almost all of your Medicare-approved costs, in or out of the hospital, with any doctor that accepts Medicare.

Watch the timing: You can add hospital indemnity any time. Switching from Medicare Advantage to a Medicare Supplement plan later usually means answering health questions.

What to Check Before You Buy

1
Observation stays. Make sure the policy pays when you are under observation, not only when admitted.
2
Waiting periods and pre-existing conditions. Some plans limit benefits in the first months.
3
Benefit period. Find out when your covered days reset after a stay.
4
Renewability. Look for a guaranteed renewable policy.
5
Match your plan. Pick a daily benefit and covered days close to your actual hospital copays.

For two popular options, compare Mutual of Omaha hospital indemnity insurance with Aetna hospital indemnity insurance.

The Bottom Line

Hospital indemnity insurance is worth it when your Medicare plan leaves you with real hospital costs, like Medicare Advantage copays or a high deductible. With Plan G or Plan F, it is usually optional. A licensed insurance agent can match a plan to your actual costs at no charge.

Compare hospital indemnity quotes

Speak with a licensed insurance agent

1-888-891-0229

Keep Reading

Cigna Hospital Indemnity Insurance 2027: now sold as HealthSpring, how it works, the plan levels and what it pays.

Is Hospital Indemnity Insurance Worth It — Frequently Asked Questions

➤ Is hospital indemnity insurance worth it for seniors?

It is often worth it for seniors with Medicare Advantage plans that charge daily hospital copays, or with High-Deductible Plan G. It is usually less useful if you already have Medicare Supplement Plan G or Plan F, since those cover most hospital costs.

➤ How much does hospital indemnity insurance cost?

For seniors, premiums often run about $20 to $80 a month, depending on your age, state, daily benefit amount, number of covered days and any riders you add.

➤ What does hospital indemnity insurance pay?

It pays a set cash amount, such as $100 to $500 a day or a lump sum per admission, when you are admitted to the hospital. The money goes to you, and you can use it for anything.

➤ Does hospital indemnity insurance pay for observation stays?

Some policies do and some don’t. Many seniors are placed under observation instead of admitted, so check the policy wording before you buy.

➤ Do I need hospital indemnity insurance if I have a Medicare Supplement plan?

Usually not much. Plan G and Plan F cover the Part A deductible and hospital coinsurance. It can still make sense with High-Deductible Plan G or Plan N, or if you want cash for non-medical bills.

➤ Is there a waiting period for hospital indemnity insurance?

It depends on the company. Some plans have no waiting period, while others limit benefits for pre-existing conditions or sickness for the first months of the policy.

➤ Can I buy hospital indemnity insurance any time of year?

Yes. Hospital indemnity insurance is not a Medicare plan, so there is no enrollment period. You can apply any time, though some companies ask health questions.

➤ Can a licensed agent help me decide if hospital indemnity is worth it?

Yes. A licensed insurance agent can look at your Medicare plan’s hospital costs and quote hospital indemnity plans that match them, at no cost to you.

Free Hospital Indemnity Quote

Call a Licensed Agent Now

Get cash for hospital stays. Compare hospital indemnity plans from several insurance companies in one call.

☎ 1-888-891-0229

No cost, no obligation to enroll