Speak with a licensed insurance agent

1-888-891-0229

Aetna Medicare Supplement Plan F 2027: Who Can Buy It, What It Covers and What Aetna Charges

Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated November 6, 2026

Key Takeaway

Aetna Medicare Supplement Plan F is open only to people first eligible for Medicare before January 1, 2020, and it pays every Medicare-approved gap, including the Part B deductible that Plan G leaves to you. In the Aetna rate tables reviewed here, a 65-year-old woman pays $288 to $926 a year more for Plan F than for Aetna’s Plan G, which is more than the $283 deductible it buys back.

2027 by the Numbers

$285

Aetna Plan F a month, woman 65, preferred (Maryland rate guide, Jan. 1, 2027)

$926

Yearly Aetna Plan F minus Plan G, woman 65, St. Louis/Kansas City ZIPs (our math, Aetna MO outline)

11.8%

Average Plan F request in 2025-26 closed-block rate filings (CSG Actuarial)

A

AM Best rating for Aetna’s Medigap issuers, affirmed June 2026

Plan F was the default Medicare Supplement choice for decades because it left nothing to pay at the doctor or hospital for Medicare-approved care. Federal law stopped its sale to anyone newly eligible for Medicare starting in 2020, yet Aetna still files Plan F rates in many states for the people who qualify.

Searches for Aetna Plan F usually turn up a benefit chart and a vague price range. This guide pulls Aetna’s own outlines of coverage and a state rate guide, prices Plan F next to Aetna’s Plan G for the same person, and runs the keep-or-switch math for an existing policyholder.
Check Aetna Plan F rates for your ZIP code

Speak with a licensed insurance agent

1-888-891-0229

Who Is Still Allowed to Buy Aetna Plan F

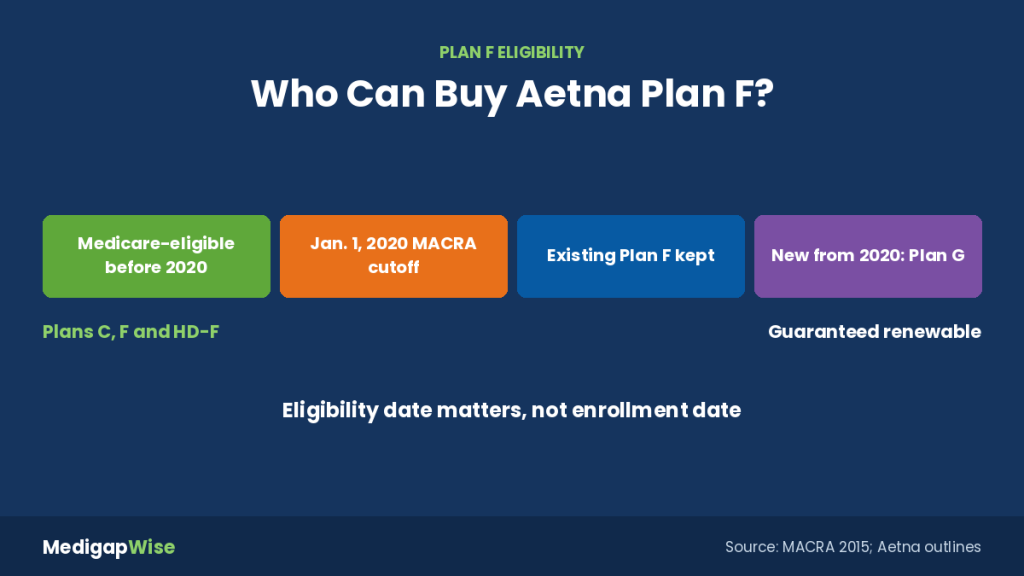
Timeline of Aetna Medicare Supplement Plan F eligibility: eligible for Medicare before 2020 can buy Plan F, the 2020 MACRA cutoff, and people new to Medicare from 2020 on choose Plan G

The Medicare Access and CHIP Reauthorization Act of 2015 (MACRA) barred Medigap plans that pay the Part B deductible from being sold to anyone who became eligible for Medicare on or after January 1, 2020. Aetna’s Missouri, North Carolina and South Carolina outlines print the same limit: only applicants first eligible for Medicare before 2020 may buy them.

Eligibility is the test, not enrollment. Someone who turned 65 in 2019 but delayed Part B while working can still apply for Aetna Plan F today, as can a person who qualified through disability before 2020 and now has reached 65. Current Plan F owners keep their policies.

Before you apply: Outside your six-month Medigap open enrollment window or a guaranteed issue right, Aetna can ask health questions and decline the application or place you in a higher-priced class.

Aetna Plan F Coverage Compared With Aetna Plan G

Aetna Plan F carries the same nine standardized benefits as any insurer’s Plan F, and Aetna Plan G carries eight of them. The difference is the yearly Part B deductible, $283 in 2026, which Plan F pays and Plan G does not.

✔
Part A: the hospital deductible ($1,736 per benefit period in 2026), hospital coinsurance plus 365 extra lifetime days, skilled nursing coinsurance and hospice coinsurance.
✔
Part B: the 20% coinsurance and up to 15% in excess charges from doctors who don’t take assignment.
✔
Part B deductible: paid by Plan F only. CMS sets the 2027 figure in the fall, and the 2026 Medicare Trustees Report estimated $292.
✔
Blood and foreign travel: the first three pints, plus 80% of emergency care abroad after a $250 deductible, on both.

Neither letter covers drugs, dental, vision or hearing. Insurer-wide pricing sits on our Medicare Supplement Plan F cost page.

Aetna Plan F Premiums in Filed Rate Tables

No public source lines up Aetna’s Plan F and Plan G prices across states, so the table below was assembled from four sets of filed or published rates. Every row is a woman at 65 in Aetna’s preferred class, shown as yearly premiums. Maryland publishes monthly rates, which were multiplied by 12.

State and area Aetna issuer Rates dated Plan F / year Plan G / year F minus G HD-F sold?
Maryland Aetna Health Ins. Co. Jan. 1, 2027 guide $3,420 $3,132 $288 No
South Carolina, ZIP 294-295, 298-299 Aetna Health Ins. Co. Apr. 1, 2024 $2,025 $1,674 $351 No
North Carolina Aetna Health Ins. Co. May 1, 2024 $1,880 $1,449 $431 No
Missouri, rest of state Aetna Health and Life July 1, 2024 $2,848 $2,021 $827 Yes, $582
Missouri, ZIP 630-631, 633, 640-641 Aetna Health and Life July 1, 2024 $3,190 $2,264 $926 Yes, $652

Sources: Maryland Insurance Administration Medicare Supplement rate guide (rates as of January 1, 2027); Aetna outlines of coverage AHCMS04875SC, AHCMS04873NC and AHLMS04997MO. The three outlines are the newest Aetna versions posted, so current premiums there are probably higher. Maryland’s lowest Plan F for the same woman is $194 a month, from First Health Life and Health.

Compare Aetna Plan F with Aetna Plan G

Speak with a licensed insurance agent

1-888-891-0229

Plan F Usually Costs More Than the Deductible It Covers

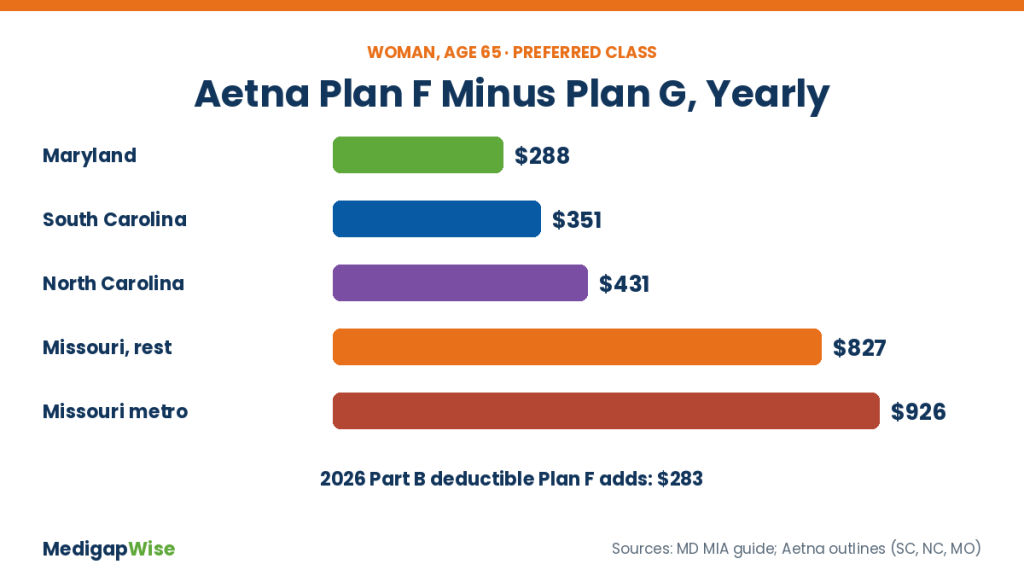
Bar chart of the yearly Aetna Plan F minus Plan G premium for a 65-year-old woman: Maryland $288, South Carolina $351, North Carolina $431, Missouri rest of state $827 and Missouri metro ZIPs $926

Plan F’s extra benefit is worth one Part B deductible a year, $283 in 2026. In every Aetna table above, the extra premium is larger than that. Maryland comes closest, with a $288 gap that nearly equals the deductible. In Missouri the gap runs $827 to $926, roughly three times the deductible.

The spread also widens with age in attained-age states. North Carolina’s preferred table for women shows the Plan F premium $431 above Plan G at 65, $535 above at 75 and $633 above at 80.

Reading the filings: When Aetna’s own Plan F and Plan G prices differ by less than the Part B deductible, Plan F costs nothing extra. None of the five tables reviewed met that test for a 65-year-old woman.

Questions? Talk to a Licensed Agent

We compare Plan G, Plan N and more from several insurance companies at no cost to you.

☎ 1-888-891-0229

No cost, no obligation to enroll

Which Aetna Companies Sell Plan F, and Where High-Deductible F Fits

Several CVS Health subsidiaries issue Aetna Medicare Supplement plans. In the documents reviewed here, Aetna Health Insurance Company issues Plan F in Maryland, North Carolina, South Carolina and Oklahoma, while Aetna Health and Life Insurance Company issues it in Missouri. Continental Life and American Continental issue Aetna policies in other states.

High-Deductible Plan F is spottier. Aetna’s Missouri outline and Oklahoma brochure list it, but the Maryland, North Carolina and South Carolina tables carry only High-Deductible G. It has the same pre-2020 eligibility rule and a federal $3,050 deductible in 2027.

On June 5, 2026, AM Best affirmed an A (Excellent) financial strength rating with a stable outlook for Aetna Health Insurance Company, Aetna Health and Life, Continental Life, American Continental and Accendo. The wider carrier picture is in our Aetna Medicare Supplement review.

Rate Increases on a Plan Nobody New Can Join

Since 2020, no 65-year-olds have entered Plan F, so the people left in it get older each year and tend to file more claims. Many owners fear that aging pool means runaway increases.

The filed data is more mixed. CSG Actuarial reviewed 2,736 closed-block rate filings from 2025 and 2026 and found Plan F requests averaging 11.8%, slightly below the 12.9% average for Plan G in those same blocks. Its 2026 second-quarter update said Aetna’s increases leveled off in 2026 after a large jump from 2024 to 2025.

Your renewal letter is the only reliable figure for your own policy. State-by-state Aetna filings are tracked in our Aetna Medicare Supplement rate increase history, and our guide to Medicare Supplement rate increases explains how states review them.

Worked Example: Keep Aetna Plan F or Move to Plan G at 75

Assumptions: a 75-year-old North Carolina woman holding Aetna Plan F, priced on Aetna’s May 2024 attained-age table against a new Aetna Plan G policy, with the 2026 Part B deductible of $283 and a $20 one-time fee on the new policy.

1
Keep Plan F: $2,342 premium, nothing more for Medicare-approved care = $2,342.
2
Switch and qualify for preferred Plan G: $1,807 + $283 deductible + $20 fee = $2,110, about $232 less in year one and $252 less after that.
3
Switch but land in standard Plan G: $2,008 + $283 + $20 = $2,311, only $31 less in year one.
4
With the household discount: Aetna’s 7% household rate cuts her Plan F to $2,178 and preferred Plan G to $1,681 when a spouse or partner also holds an Aetna policy.

Health answers set the class, and the class decides the case. The full process is in our guide to switching from Plan F to Plan G, and the same steps apply when comparing Aetna’s Medicare Supplement Plan G with other insurers.

Find out if switching from Plan F saves money

Speak with a licensed insurance agent

1-888-891-0229

Should You Hold On to Your Aetna Plan F?

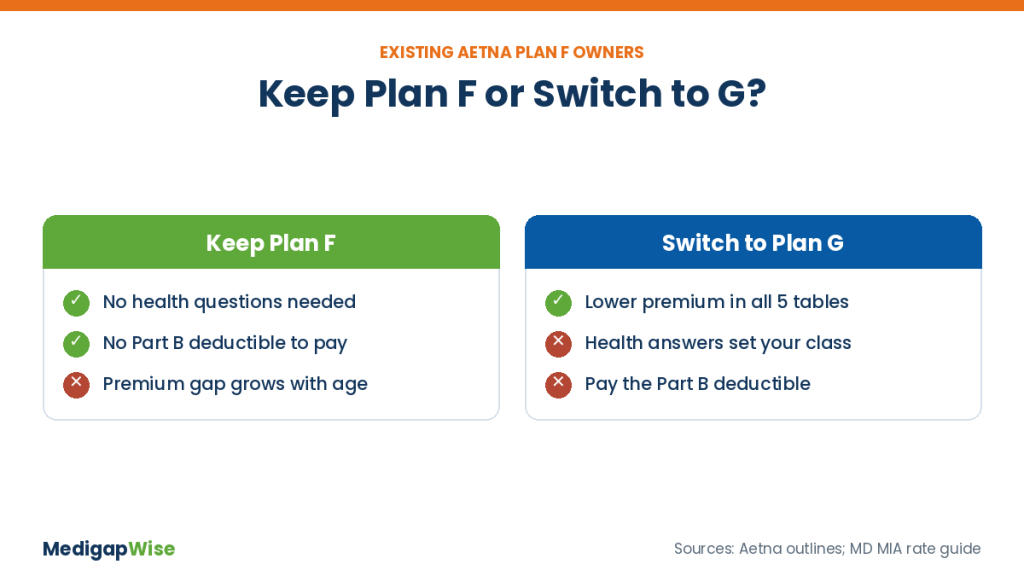
Keeping Aetna Plan F versus switching to Plan G: reasons to keep Plan F such as health changes and no deductible, against reasons to switch such as lower premiums

Keeping Plan F makes sense when health conditions might fail underwriting, when the premium gap in your state is small, or when a fixed, deductible-free budget matters more than a few hundred dollars. Switching pays off when the gap is large and health questions are no obstacle.

Lean toward keeping

✔Recent diagnosis or new medications
✔Plan F to G gap near $283 a year
✔No guaranteed issue right to fall back on

Lean toward switching

✔Gap well above $283 a year
✔Good health for preferred rates
✔Birthday or anniversary rule in your state

Lower-premium options are covered on our Aetna Medicare Supplement Plan N page, and our Medicare Supplement plans cost guide compares premiums across all plan letters. See also our household discount guide.

Keep Reading

Are Medicare Supplement Premiums Tax Deductible?: when a Plan F or Plan G premium lowers your federal tax, the 7.5% of AGI test, the self-employed route and why HSA money can’t pay it.

Aetna Plan F: Your Questions Answered

➤ Can I buy Aetna Plan F if I turned 65 in 2026?

Not if 2026 is when you first became eligible for Medicare. If you qualified earlier, for example through disability before 2020, you can still apply.

➤ What does Aetna Plan F coverage include?

It pays the Part A and Part B deductibles, Part A and Part B coinsurance, Part B excess charges, skilled nursing and hospice coinsurance, the first three pints of blood and 80% of emergency care abroad after a $250 deductible.

➤ How much does Aetna Plan F cost a month?

For a 65-year-old woman at preferred rates, filed figures run from about $157 in North Carolina to $285 in Maryland and $266 in parts of Missouri. Men and older ages generally pay more.

➤ Will Aetna cancel my Plan F because it is no longer sold?

No. Medigap policies are guaranteed renewable, so Aetna must renew your Plan F as long as you pay the premium and answered the application truthfully.

➤ Is Aetna Plan F worth the extra premium over Plan G?

Only when the yearly premium gap is close to the Part B deductible. In the Aetna tables reviewed here, the gap ranged from $288 to $926 a year for a woman at 65.

➤ Does Aetna offer High-Deductible Plan F?

In some states. It appears in Aetna’s Missouri and Oklahoma materials but not in its Maryland, North Carolina or South Carolina rates.

➤ Does Aetna’s household discount apply to Plan F?

Yes, where the state allows it. The North Carolina, South Carolina and Missouri outlines list a 7% household discount for all plan letters, including Plan F.

➤ Who can help me compare Aetna Plan F with other options?

A licensed agent can quote Aetna Plan F, Aetna Plan G and other insurers’ plans for your ZIP code and age at no cost.

Free Medigap Price Comparison

Call a Licensed Agent Now

Compare Plan G, Plan N and more from several insurance companies in one call.

☎ 1-888-891-0229

No cost, no obligation to enroll