Speak with a licensed insurance agent

1-888-891-0229

Does Medicare Supplement Cover the Part B Deductible? 2027 Answer, Plan by Plan

Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated October 27, 2026

Key Takeaway

Only two Medicare Supplement plan letters, C and F, pay the Part B deductible (High-Deductible F counts it toward its own $3,050 deductible), and none of them can be bought by anyone who first became eligible for Medicare on or after January 1, 2020. Every other plan, including Plan G and Plan N, leaves that yearly deductible, $283 in 2026, for you to pay.

2027 by the Numbers

$283

2026 Part B deductible; the 2027 amount was not yet announced on Nov. 3, 2026 (CMS)

$85

Rise in the Part B deductible from $198 in 2020 to $283 in 2026 (CMS fact sheets)

$3,050

2027 deductible for High-Deductible Plans F and G (CMS, Oct. 2026)

$8,360

2027 Plan K out-of-pocket limit; Plan L’s is $4,180 (CMS, Oct. 2026)

The Part B deductible is the first slice of outpatient medical bills you pay each calendar year before Original Medicare starts paying its 80%. It’s small next to a hospital bill, but it’s the single line that separates the most complete Medigap plans from the rest, and it’s the reason Plan F disappeared for people turning 65 today.

Below: which plan letters pay it, the federal rule that closed them, what “first eligible” actually means, the deductible year by year since 2020, and the simple premium math that tells you whether paying it yourself is the better deal.

Compare Plan G and Plan F prices in your area

Speak with a licensed insurance agent

1-888-891-0229

The Direct Answer: Two Letters, One Cutoff Date

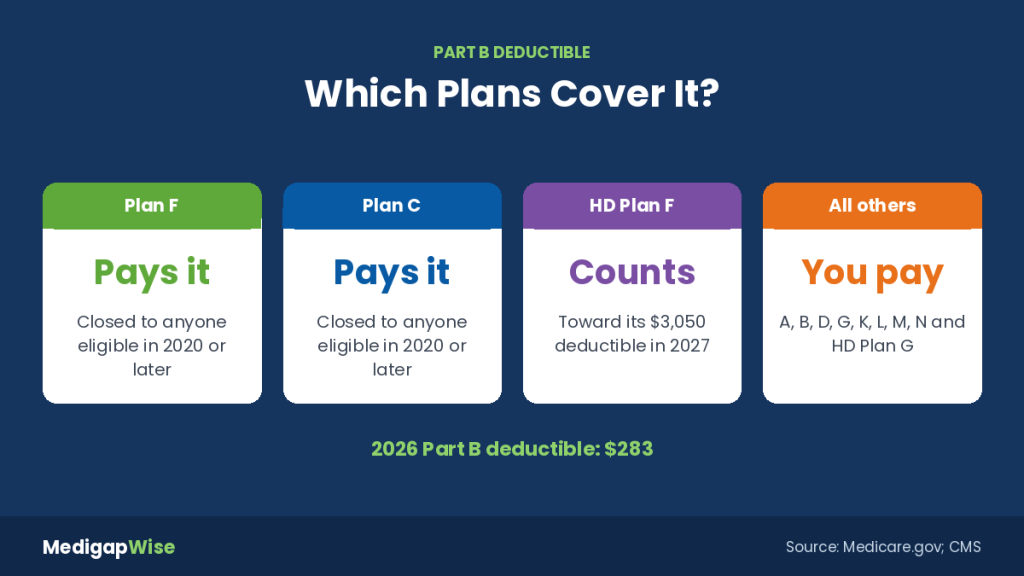
Which Medicare Supplement plans cover the Part B deductible: Plans C and F pay it, High-Deductible F counts it toward $3,050, and Plans A, B, D, G, K, L, M and N leave it to you

Of the ten standardized Medigap plan letters, only Plan C and Plan F pay the Part B deductible in full. High-Deductible Plan F treats it differently: the Part B deductible counts toward that plan’s own $3,050 deductible in 2027.

The catch is eligibility. The Medicare Access and CHIP Reauthorization Act of 2015 (MACRA) barred the sale of any Medigap policy covering the Part B deductible to people newly eligible for Medicare on or after January 1, 2020, which closed exactly those three plans.

Eligible before 2020? You may still buy one. Eligible in 2020 or later? No plan sold to you will pay it. All plan letters are compared in our guide to Medicare Supplement plans.

Who Pays the Part B Deductible Under Each Plan Letter

Benefits are standardized, so this holds for every insurer that sells the plan.

Plan Part B deductible Can a 2020+ enrollee buy it? Detail worth knowing
Plan C Plan pays No Also closed to new enrollees; Plan D is its open counterpart
Plan F Plan pays No Pays every Medicare-covered gap
High-Deductible F Counts toward $3,050 No Plan pays after the 2027 deductible is met
Plan A You pay Yes Core benefits only
Plan B You pay Yes Adds the Part A deductible
Plan D You pay Yes Same as Plan C except the Part B deductible
Plan G You pay Yes Like Plan F minus the Part B deductible
High-Deductible G You pay (counts toward $3,050) Yes Same $3,050 threshold as HD-F
Plan K You pay Yes $8,360 out-of-pocket limit in 2027
Plan L You pay Yes $4,180 out-of-pocket limit in 2027
Plan M You pay Yes Pays 50% of the Part A deductible
Plan N You pay Yes Plus office and ER copays

Massachusetts, Minnesota and Wisconsin use their own plan designs instead of these letters.

Run the break-even math with real quotes

Speak with a licensed insurance agent

1-888-891-0229

What "First Eligible Before 2020" Really Means

The rule turns on when you became eligible for Medicare, not when you enrolled. State regulators define a newly eligible person as someone who turned 65 on or after January 1, 2020, or first became eligible because of age, disability or end-stage renal disease on or after that date. In practice:

✔
Turned 65 in 2019 but delayed Part B for work coverage: you were eligible before 2020, so C and F can generally still be sold to you.
✔
On Medicare through disability since before 2020: you aren’t newly eligible, so at 65 Plans C and F are generally open to you where insurers sell them.
✔
Under 65 and eligible through disability or ESRD in 2020 or later: you’re newly eligible, so C and F are off the table now and at 65.
✔
Turned 65 on January 1, 2020 or later: no plan you can buy will cover the Part B deductible.

A detail in the fine print: For newly eligible people, federal guaranteed issue rights that named Plans C and F now point to Plans D and G, as New Jersey’s insurance department noted in its 2019 bulletin. A guaranteed issue right never reopens Plan F for this group.

If You Already Have Plan F or Plan C

MACRA stopped new sales; it didn’t cancel anyone’s coverage. An existing Plan F or Plan C policy stays guaranteed renewable as long as premiums are paid, and the Part B deductible stays covered.

Keeping it is a pricing question. Plan F’s only extra over Plan G is the deductible, so the test is whether its premium costs more than that each year. See our Medicare Supplement Plan F cost guide; the switching steps are in our guide to switching from Plan F to Plan G.

Plan C holders face the same choice with Plan D, which matches Plan C on every benefit except the deductible.

Questions? Talk to a Licensed Agent

We compare Plan G, Plan N and more from several insurance companies at no cost to you.

☎ 1-888-891-0229

No cost, no obligation to enroll

Break-Even Math: Is Paying the Deductible Yourself Cheaper?

Since the deductible is the only benefit gap between Plan F and Plan G, divide it by 12 to get the monthly premium difference at which the two cost the same.

✔
At the 2026 deductible of $283: break-even is $23.58 a month.
✔
At the 2020 deductible of $198: it was $16.50 a month.
✔
In a year with no Part B claims: Plan G keeps the full premium difference.

Worked example (hypothetical round premiums): Plan F at $240 a month is $2,880 a year. Plan G at $190 a month is $2,280 plus the $283 deductible, or $2,563, so Plan G is $317 ahead. Shrink the gap to $20 a month and Plan F is $43 ahead. Real quotes depend on age, ZIP code, tobacco use and insurer.

Quick rule of thumb: A monthly gap above $23.58 favors Plan G over a full year; below it, Plan F.

Ask a licensed agent which plans you can buy

Speak with a licensed insurance agent

1-888-891-0229

The Part B Deductible Year by Year, 2020 to 2027

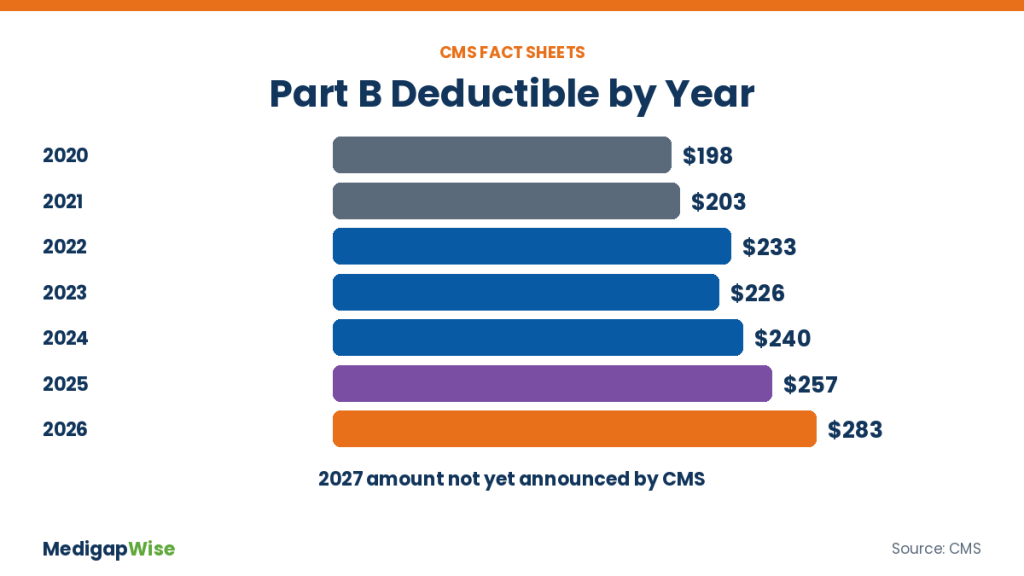
Medicare Part B deductible by year from CMS fact sheets: $198 in 2020, $203 in 2021, $233 in 2022, $226 in 2023, $240 in 2024, $257 in 2025 and $283 in 2026

CMS’s annual fact sheets show the deductible since the 2020 cutoff:

✔
2020: $198  ·  2021: $203  ·  2022: $233, a $30 jump
✔
2023: $226, the only year in this stretch the deductible went down, by $7
✔
2024: $240  ·  2025: $257  ·  2026: $283, up $26
✔
2020 to 2026: up $85, roughly 43%

Still pending for 2027: As of November 3, 2026, CMS had not released the 2027 Part B deductible; it usually does in November. The 2026 Medicare Trustees Report projected about $292, an estimate only, which would move the break-even to about $24.33 a month.

For newer enrollees, each increase raises the one cost Plan G leaves behind; see our Medicare Supplement Plan G guide.

What the Part B Deductible Applies To, and What It Doesn't

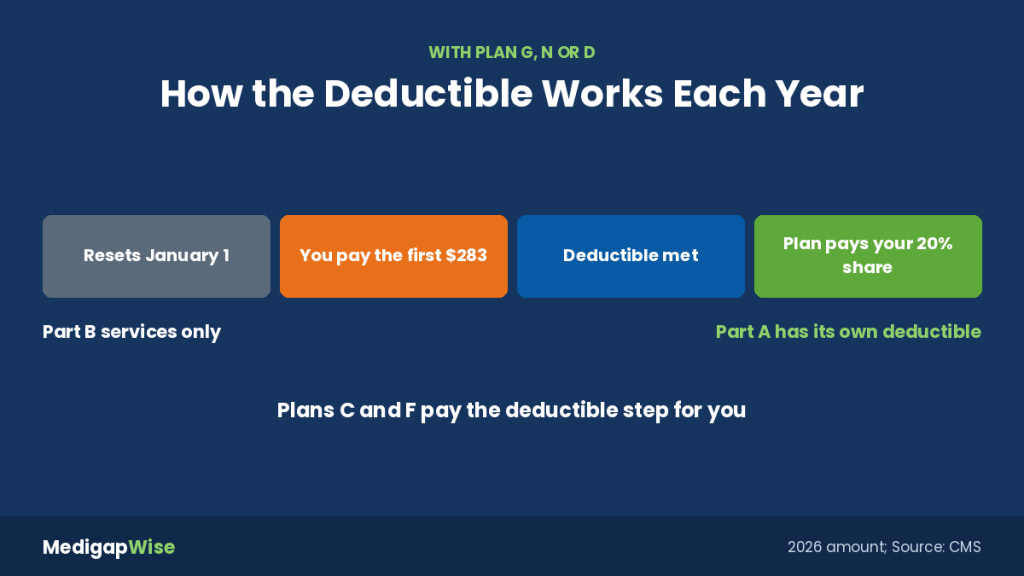
How the Part B deductible works each year with a Medicare Supplement plan that doesn't cover it: it resets January 1, you pay the first $283 of approved Part B charges, then the plan pays your 20%

The deductible applies only to Part B. Medicare pays nothing on Part B claims until your approved Part B charges for the calendar year reach it, and the count restarts each January 1.

Counts toward it

✔Doctor and specialist visits
✔Outpatient surgery and hospital outpatient care
✔Durable medical equipment
✔Outpatient therapy and ambulance rides

Separate from it

✔Inpatient hospital stays (Part A has its own deductible, $1,736 per benefit period in 2026)
✔Most preventive services from providers who accept assignment
✔Your monthly premiums
✔Prescription drugs under Part D

Every plan letter except Plan A pays at least part of the Part A deductible. Only Medicare-approved amounts count toward the Part B deductible, so an excess charge isn’t part of it, though Plans F and G cover excess charges separately.

Picking a Plan When the Deductible Isn't Covered

For anyone newly eligible since 2020, the choice is how to carry the deductible:

1
Plan G: the deductible, then nothing for covered care.
2
Plan N: the deductible plus up to $20 per office visit and $50 per ER visit without admission; see our Medicare Supplement Plan N guide.
3
High-Deductible Plan G: the deductible folds into a $3,050 threshold for 2027 for a lower premium; our High-Deductible Plan G guide runs those scenarios.
4
Compare totals, not premiums: add yearly premium to expected cost sharing; see Medicare Supplement plans cost.

Still weighing a supplement against Medicare Advantage? Read Medigap vs Medicare Advantage.

Keep Reading

Top 5 Medicare Supplement Plans for 2027: the five plan letters with the most enrollees in NAIC data, which ones are still sold, and a G vs N vs HD-G cost example.

Medicare Supplement and the Part B Deductible: Your Questions

➤ Which Medicare Supplement plans pay the Part B deductible in 2027?

Plans C and F pay it in full, and High-Deductible Plan F counts it toward its $3,050 deductible for 2027. None of the three can be sold to someone who first became eligible for Medicare on or after January 1, 2020.

➤ Does Plan G ever pay the Part B deductible?

No. It’s the one gap Plan G leaves. Once you’ve paid it for the year, Plan G picks up your share of approved Part B charges.

➤ I was on Medicare through disability in 2018. Can I buy Plan F at 65?

Generally yes. Your eligibility began before 2020, so Plans C and F can be sold to you at 65 where insurers offer them.

➤ What is the 2027 Part B deductible?

CMS hadn’t announced it as of November 3, 2026. It was $283 for 2026, and the 2026 Medicare Trustees Report projected roughly $292 for 2027. CMS normally releases the official amount in November.

➤ How much cheaper does Plan G need to be than Plan F?

At the 2026 deductible, more than $23.58 a month, which is $283 divided by 12. Above that gap, Plan G costs less over a full year even if you pay the whole deductible.

➤ Does the Part B deductible apply to hospital stays?

No. Inpatient hospital care falls under Part A, which has its own deductible of $1,736 per benefit period in 2026. Most Medicare Supplement plans pay all or part of that Part A deductible.

➤ Do Plans K and L count the Part B deductible?

Neither plan pays it. Each has a yearly out-of-pocket limit instead, $8,360 for Plan K and $4,180 for Plan L in 2027, after which the plan pays 100% of covered services for the rest of the year.

➤ Will I lose Plan F’s deductible coverage if I keep my policy?

No. Plan F is guaranteed renewable, so the deductible stays covered while you keep paying the premium.

Free Medigap Price Comparison

Call a Licensed Agent Now

Compare Plan G, Plan N and more from several insurance companies in one call.

☎ 1-888-891-0229

No cost, no obligation to enroll