Speak with a licensed insurance agent

1-888-891-0229

High-Deductible Plan F 2027: Medicare Supplement Eligibility, Deductible and Keep-or-Switch Math

Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated November 6, 2026

Key Takeaway

High-Deductible Plan F is a Medicare Supplement plan that only people eligible for Medicare before January 1, 2020 can buy; in 2027 it pays nothing until you’ve paid $3,050 in Medicare-covered costs, then covers 100% of them, including the Part B deductible, for the rest of the year.

2027 by the Numbers

$3,050

2027 High-Deductible F, G and J deductible, effective Jan. 1, 2027 (CMS, Oct. 2026)

3.40%

CPI-U rise that moved the amount up from $2,950 in 2026 (CMS)

$283

2026 Part B deductible, which counts toward the HD-F amount; 2027 figure not yet released (CMS)

1/1/2020

Medicare eligibility cutoff for buying any version of Plan F (MACRA)

Before anything else, High-Deductible Plan F comes down to a date. If your Medicare eligibility started on or after January 1, 2020, no insurer can sell it to you, no matter your age, health or state. If your eligibility started earlier, it’s still on the table, and for some people it’s one of the cheapest ways to cap a bad medical year.

This guide is for that second group: people deciding whether to buy HD-F, and people who already own it and wonder whether to keep it. It covers eligibility, the 2027 amount, a small difference from High-Deductible Plan G, our break-even table and closed-pool pricing.

Check High-Deductible Plan F prices in your ZIP code

Speak with a licensed insurance agent

1-888-891-0229

Can You Still Buy High-Deductible Plan F?

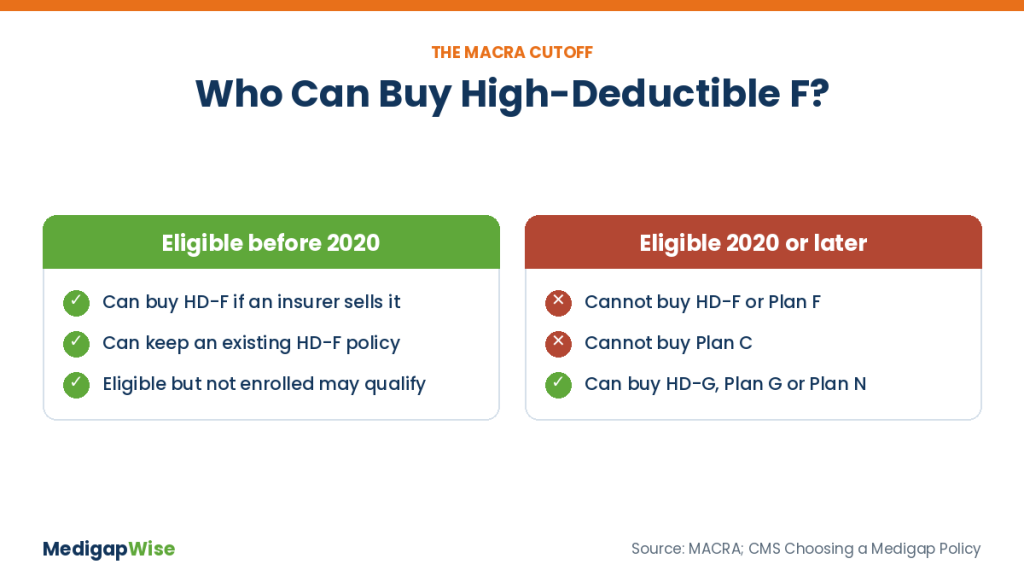
Who can buy High-Deductible Plan F in 2027: people eligible for Medicare before January 1, 2020 can, people newly eligible in 2020 or later cannot

The Medicare Access and CHIP Reauthorization Act of 2015 (MACRA) barred the sale of any Medigap plan that pays the Part B deductible to people newly eligible for Medicare on or after January 1, 2020. That rule closed Plan C, Plan F and the high-deductible version of F to everyone in that group.

The test is eligibility, not enrollment. The federal “Choosing a Medigap Policy” guide says that if you were eligible for Medicare before January 1, 2020 but haven’t enrolled yet, you may still be able to buy Plan C or F. That opens the door for a few groups:

✔
People who turned 65 before 2020, including those who delayed Part B because they had job-based coverage
✔
People under 65 who qualified for Medicare through disability before 2020, where their state requires insurers to sell to them
✔
Current HD-F owners, who can keep the policy as long as they pay the premium

Availability is a separate question: Being eligible doesn’t mean a company in your ZIP code still files HD-F. The menu is often shorter than for standard Plan F.

The 2027 Deductible Amount and Where It Comes From

CMS’s October 2026 notice sets the High-Deductible F, G and J deductible at $3,050 for calendar year 2027, effective January 1. The amount is the same with every insurer in every state that uses the standard letters, because the law fixes the formula: the prior year’s figure, adjusted by the change in the Consumer Price Index for all urban consumers, rounded to the nearest $10.

The 2027 increase is $100, from $2,950 in 2026, based on a 3.40% CPI-U change. Foreign travel emergency care keeps its own separate $250 deductible.

Meanwhile, the 2027 Part A and Part B deductibles weren’t out when this page was published on November 6, 2026. The figures used below are CMS’s 2026 amounts: a $1,736 Part A deductible per benefit period, a $283 Part B deductible and a $202.90 standard Part B premium.

What Counts Toward the HD-F Deductible (and the Part B Detail)

The NAIC’s standardized benefit chart for HD-F says the expenses that count are those the policy would ordinarily pay, and it names both Medicare deductibles, Part A and Part B, as included. Here’s the split:

Counted

✔Part A deductible and hospital coinsurance
✔Part B deductible
✔20% Part B coinsurance
✔Part B excess charges

Not counted

✔Medigap and Part B premiums
✔$250 foreign travel deductible
✔Care Medicare doesn’t approve
✔Drug costs under Part D

The detail most comparisons skip: after its deductible is met, HD-F pays what standard Plan F pays, and standard Plan F pays the Part B deductible. HD-G switches to standard Plan G benefits, which leave the Part B deductible with you. Usually that’s moot, since the Part B deductible is paid early and counts either way. But if Part A costs alone push you past the threshold before you’ve met the Part B deductible, as in a long hospital stay early in the year, HD-F would pick up the Part B deductible afterward and HD-G generally would not. Confirm with the insurer.

For the standard-plan version of that question, see whether Medicare Supplement covers the Part B deductible.

HD-F, HD-G and Standard Plan F Side by Side

Feature (2027) High-Deductible F High-Deductible G Standard Plan F
Who can buy Eligible before 1/1/2020 Anyone eligible, incl. 2020+ Eligible before 1/1/2020
Plan deductible $3,050 $3,050 None
Part B deductible counts toward it Yes Yes Not applicable
Part B deductible paid after threshold Yes No Yes, from day one
Part B excess charges Covered after $3,050 Covered after $3,050 Covered
New 65-year-olds joining the pool No Yes No

The two high-deductible plans share a threshold and nearly all benefits, but not a buyer pool. Full benefit lists for every letter are in our guide to Medicare Supplement plans, and the lower-premium G version has its own page on High-Deductible Plan G.

Questions? Talk to a Licensed Agent

We compare Plan G, Plan N and more from several insurance companies at no cost to you.

☎ 1-888-891-0229

No cost, no obligation to enroll

Break-Even Table: HD-F vs Plan F vs Plan G (Our Calculation)

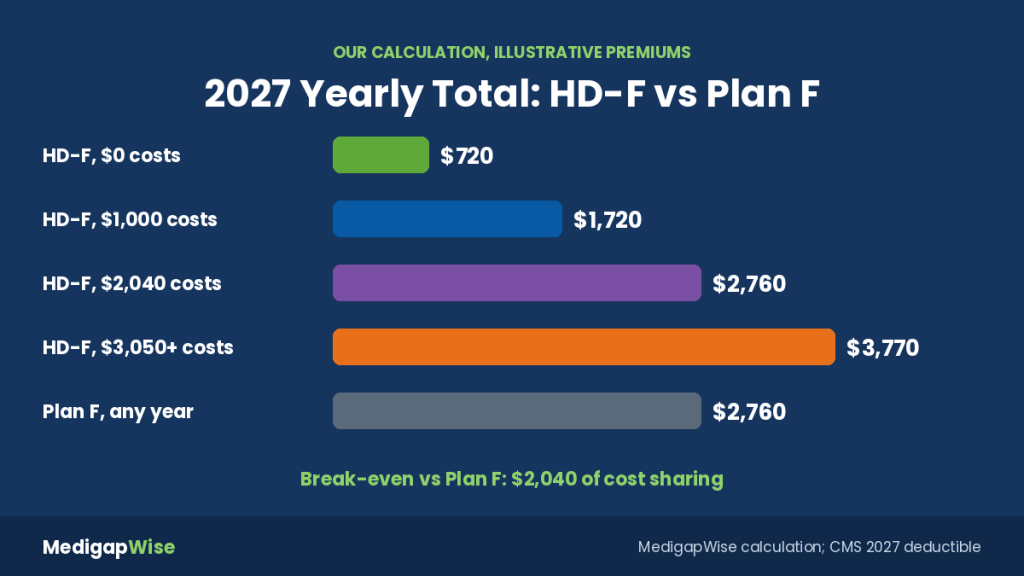
Our calculation of 2027 yearly totals for High-Deductible Plan F at different levels of Medicare cost sharing compared with standard Plan F

Assumptions, all labeled: illustrative monthly premiums of $60 for HD-F, $230 for standard Plan F and $185 for Plan G (not quotes; real prices vary by age, ZIP code and company). “Medicare cost sharing” means the counted costs you’d owe with no supplement in a given year. The 2027 HD deductible of $3,050 and the 2026 Part B deductible of $283 are used.

Your Medicare cost sharing HD-F yearly total Plan F yearly total Plan G yearly total
$0 (no claims) $720 $2,760 $2,220
$283 (Part B deductible only) $1,003 $2,760 $2,503
$1,000 $1,720 $2,760 $2,503
$1,783 $2,503 $2,760 $2,503
$2,040 $2,760 $2,760 $2,503
$3,050 or more $3,770 $2,760 $2,503

With these premiums, HD-F stays cheaper than standard F until your cost sharing reaches $2,040, the yearly premium gap. It ties Plan G at $1,783. Its worst year costs $1,010 more than standard F, while its best year saves $2,040, so a single claim-free year banks about two worst-case years’ worth of difference.

Swap in your own quotes: the break-even point against standard F is simply the yearly premium difference. Pricing basics are on our Medicare Supplement Plan F cost page.

Compare HD-F with Plan F and Plan G quotes

Speak with a licensed insurance agent

1-888-891-0229

Closed-Pool Pricing: Why HD-F Premiums Can Drift

Since 2020, no new 65-year-olds can join any Plan F risk pool. Each year the people insured under F and HD-F are, on average, a year older, and older policyholders file more claims. When a pool gets older and smaller without fresh, healthier members, insurers tend to file larger rate increases for it.

High-deductible pools differ a little: claims start only above $3,050, and the yearly CPI-U increase shifts a bit more cost back to policyholders each January. Your own renewal letters are the real evidence.

Worth tracking: Compare this year’s HD-F premium with last year’s, and with the company’s HD-G price for your age. A widening gap is a signal to price alternatives. Our guide to Medicare Supplement rate increases explains how filings work.

Already on HD-F? Keep, Trade Sideways or Move Up

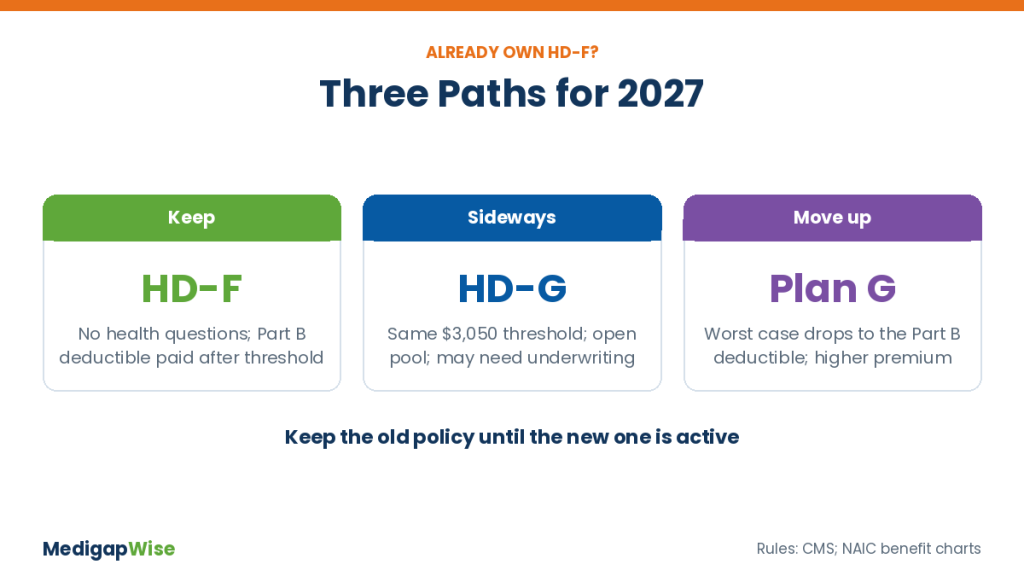
Three options for someone who owns High-Deductible Plan F in 2027: keep it, move to High-Deductible Plan G, or move up to Plan G

An HD-F owner in 2027 has three realistic paths, each with different trade-offs:

1
Keep HD-F. No underwriting, no paperwork, and the after-deductible Part B coverage stays. Makes sense while the premium is low and stable.
2
Trade sideways to HD-G. Same $3,050 threshold, a pool that still takes new members, and possibly a lower price. Outside a guaranteed issue right, most states let the new insurer review your health.
3
Move up to standard Plan G. Higher premium, but your worst case drops from about $3,050 in cost sharing to the Part B deductible. Underwriting is usually stricter for a richer plan.
4
Never cancel first. Keep HD-F in force until the new policy is approved and active.

The step-by-step for leaving F is in switching from Plan F to Plan G, standard G benefits are in Medicare Supplement Plan G, and the health questions to expect are in Medigap underwriting questions.

State Exceptions and Rules That Change the Answer

Three states don’t sell the standard lettered plans. Massachusetts, Minnesota and Wisconsin each standardize Medigap their own way. The federal guide notes that Minnesota sells its own versions of high-deductible F to people eligible before 2020 and that Wisconsin offers a high-deductible plan option; Massachusetts doesn’t list one. If you live in one of these states, ask for the state’s plan names rather than “HD-F.” Elsewhere, state rules mostly affect switching; see Medicare Supplement guaranteed issue rights by state. For the ranking context, the top Medicare Supplement plans shows how many people still hold Plan F overall.

Ask an agent whether to keep or switch your HD-F policy

Speak with a licensed insurance agent

1-888-891-0229

Keep Reading

Who Regulates Medicare Supplement Plans?: the federal law behind the HD-F deductible, what CMS, the NAIC and your state each control, and how a rate increase gets approved.

High-Deductible Plan F: Your Questions Answered

➤ Who is eligible for High-Deductible Plan F in 2027?

Anyone whose Medicare eligibility began before January 1, 2020, even if they enrolled later. People first eligible in 2020 or after can’t buy any form of Plan F.

➤ What is the High-Deductible Plan F deductible for 2027?

$3,050, per CMS’s October 2026 notice, up from $2,950 in 2026. It’s the same amount used for High-Deductible G and J.

➤ Is the Part B deductible part of the $3,050?

Yes. What you pay toward the Part B deductible counts toward the High-Deductible F deductible, as does the Part A deductible.

➤ How is HD-F different from HD-G if the deductible is the same?

Eligibility is the main difference. After the threshold, HD-F also pays the Part B deductible and HD-G doesn’t, which matters only in a year when other costs reach $3,050 before the Part B deductible is met.

➤ Can I still buy HD-F if I delayed Part B?

Possibly. Eligibility before 2020 is what counts, so someone who turned 65 in 2019 and enrolled in Part B later may still qualify, if an insurer in the area sells it.

➤ Will my HD-F premium keep going up?

Premiums can rise with age, inflation and claims. Because no new enrollees have joined since 2020, the pool ages each year, so comparing renewal prices against HD-G is worthwhile.

➤ Should I keep HD-F or switch to standard Plan G?

It depends on your premium gap and health. In our table, HD-F beat Plan G until cost sharing reached $1,783 a year; above that, Plan G cost less.

➤ Is High-Deductible Plan F sold in Massachusetts, Minnesota or Wisconsin?

Not as a lettered plan. Minnesota has its own high-deductible F version for pre-2020 eligibles and Wisconsin has a high-deductible option, so ask for each state’s plan names.

Free Medigap Price Comparison

Call a Licensed Agent Now

Compare Plan G, Plan N and more from several insurance companies in one call.

☎ 1-888-891-0229

No cost, no obligation to enroll