Speak with a licensed insurance agent

1-888-891-0229

Medicare Supplement Plan N 2027: Coverage, Copays, Costs and Who It Fits

Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated October 27, 2026

Key Takeaway

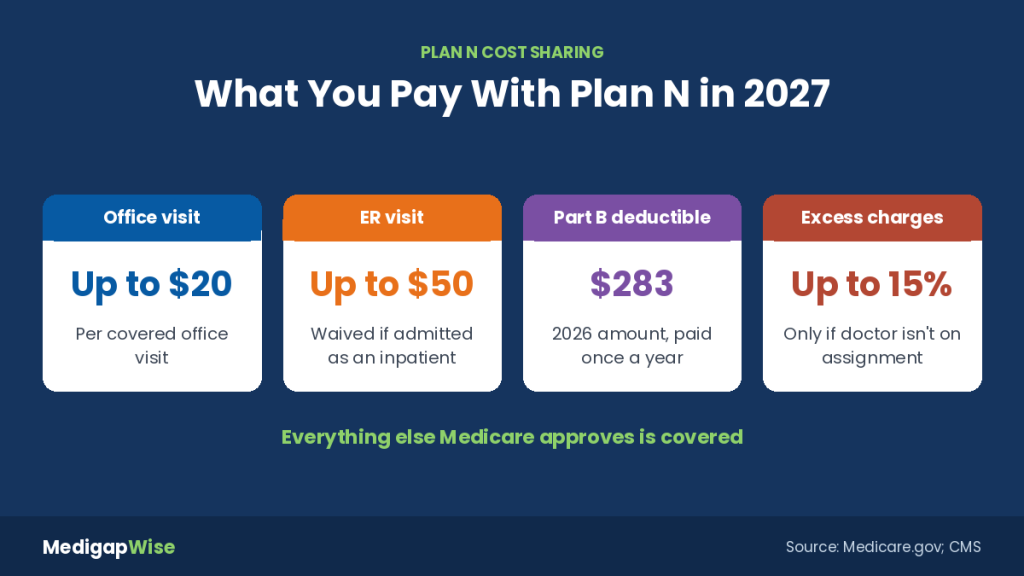
Medicare Supplement Plan N pays most of what Original Medicare leaves behind, including the Part A deductible and Part B coinsurance, in exchange for a lower premium than Plan G. You pay the Part B deductible, up to $20 for some office visits, up to $50 for ER visits that don’t lead to an inpatient admission, and any Part B excess charges.

2027 by the Numbers

$20

Max Plan N copay for a covered office visit (Medicare.gov)

$50

Max Plan N ER copay, waived if admitted as an inpatient (Medicare.gov)

$283

2026 Part B deductible Plan N doesn’t cover; 2027 amount due from CMS in November (CMS)

$1,736

2026 Part A deductible, covered 100% by Plan N (CMS)

Plan N is one of the most common choices for people who want strong Medicare Supplement coverage without paying top dollar. It protects you from the big bills, like hospital stays, while asking you to share small costs at the doctor’s office and the emergency room.

Here’s what Medicare Supplement Plan N covers in 2027, what you still pay, how it stacks up against Plan G, what it costs and how to buy it at the right time.

Get Plan N quotes in your area

Speak with a licensed insurance agent

1-888-891-0229

What Does Medicare Supplement Plan N Cover in 2027?

What you pay with Medicare Supplement Plan N in 2027: up to $20 office copay, up to $50 ER copay, the Part B deductible and Part B excess charges

Plan N is a standardized Medigap plan, so every company must offer the same benefits. According to Medicare.gov, Plan N covers:

Benefit Plan N What it means for you
Part A coinsurance and hospital costs 100% Covered up to an extra 365 days after Medicare benefits run out
Part A deductible 100% No hospital deductible ($1,736 per benefit period in 2026)
Part B coinsurance 100%, minus copays Up to $20 at some office visits, up to $50 at the ER
Skilled nursing and hospice coinsurance 100% No daily skilled nursing coinsurance
First 3 pints of blood 100% Covered
Foreign travel emergency 80% Up to plan limits
Part B deductible Not covered You pay it once a year
Part B excess charges Not covered You pay up to 15% over the Medicare-approved amount

See every plan letter side by side in our guide to Medicare Supplement plans.

Plan N Copays: How the $20 and $50 Work

Plan N pays all of your Part B coinsurance except for two copays. CMS guidance spells out how they work:

✔
Office visits: up to $20. Applies to Medicare-covered office visits with a doctor or specialist after you’ve met the Part B deductible. If the coinsurance is less than $20, you pay the lower amount.
✔
Emergency room: up to $50. Applies once per covered ER visit. It’s waived if you’re admitted as an inpatient and the visit is covered under Part A.
✔
No copay for most other services. Lab work, X-rays, medical equipment and telehealth visits don’t trigger the $20 copay. Once the Part B deductible is met, Plan N pays the 20% coinsurance on them in full.

Observation stays: If the hospital keeps you under observation instead of admitting you as an inpatient, you’re still an outpatient under Part B, so the $50 ER copay will likely apply. Confirm with your insurance company.

The Two Gaps: Part B Deductible and Excess Charges

Beyond the copays, Plan N leaves two costs to you:

Part B deductible

✔$283 in 2026; CMS usually announces the 2027 amount in November
✔Paid once a year before Plan N pays Part B costs
✔Plan G doesn’t cover it either

Part B excess charges

✔Doctors who don’t accept Medicare assignment can bill up to 15% more than the Medicare-approved amount
✔Plan N doesn’t pay this
✔A few states limit or ban excess charges

Good to know: Most doctors accept Medicare assignment, which means they can’t bill excess charges. Ask your doctors whether they accept assignment before you choose Plan N.

Medicare Supplement Plan N vs Plan G

Medicare Supplement Plan N vs Plan G: same hospital coverage, but Plan N has copays and no excess charge coverage in exchange for a lower premium

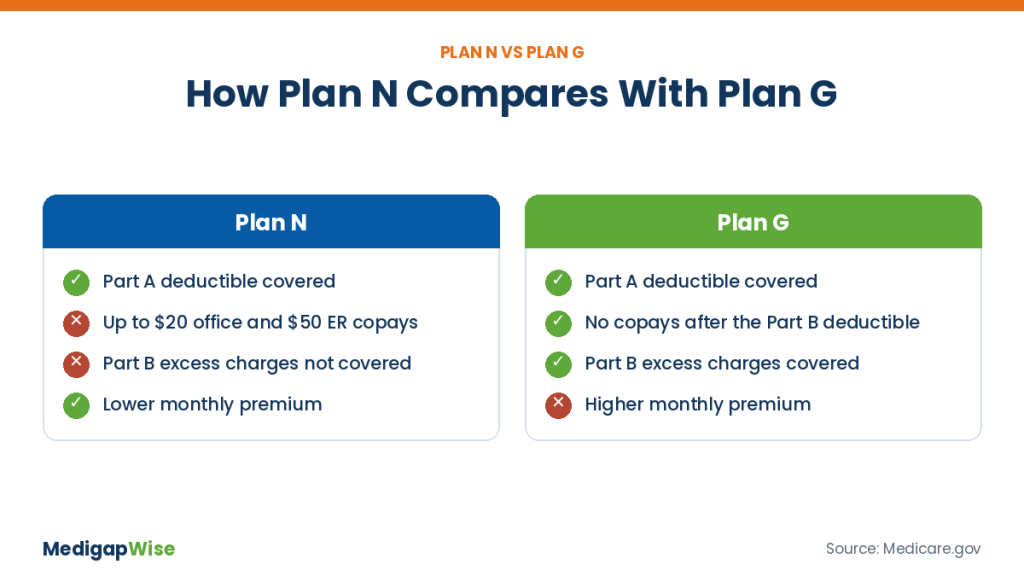
Plan G is Plan N’s closest rival. They cover the same hospital, skilled nursing, hospice and foreign travel benefits, and neither covers the Part B deductible. The differences are all on the Part B side:

✔
Copays: Plan N has up to $20 office and $50 ER copays. Plan G has none after the Part B deductible.
✔
Excess charges: Plan G covers them. Plan N doesn’t.
✔
Premium: Plan N usually costs less each month, often by enough to cover several copays.

If you already have Plan N and want Plan G later, you can usually switch, but most states let the company ask health questions. Read the rules in our guide on how to switch from Plan N to Plan G.

Compare Plan N and Plan G prices

Speak with a licensed insurance agent

1-888-891-0229

How Much Does Plan N Cost?

Illustrative yearly cost example for Medicare Supplement Plan N vs Plan G with eight doctor visits and one ER visit

Plan N premiums depend on your age, ZIP code, gender, tobacco use and the company. Because the benefits are identical, the same plan can cost very different amounts from one company to the next.

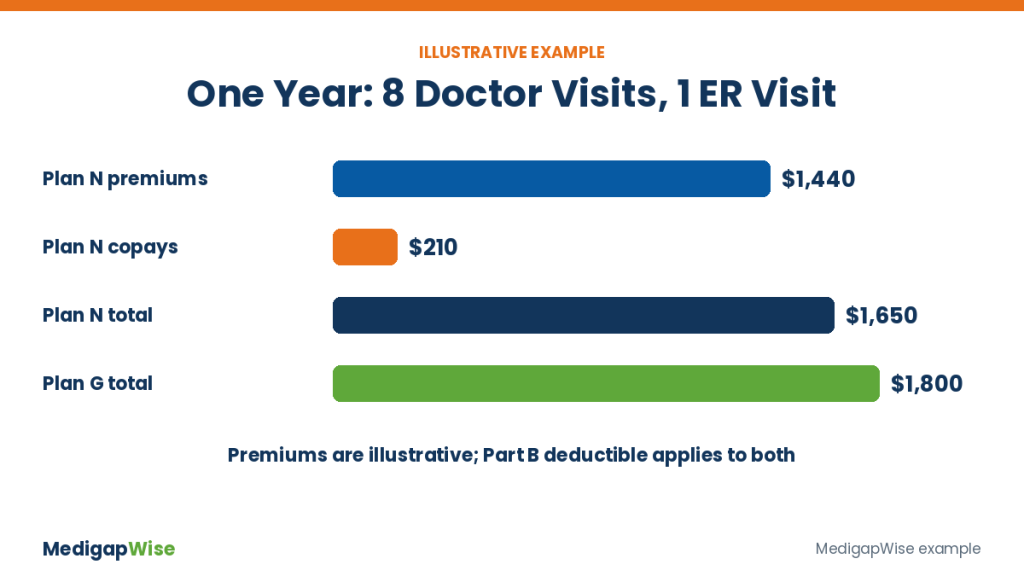
Worked example (illustrative premiums): say Plan N costs $120 a month and Plan G costs $150 a month in your area. You see the doctor 8 times in a year and make 1 ER visit that doesn’t lead to an admission. You’d pay the Part B deductible under either plan, so leave it out:

Yearly cost Plan N Plan G
Premiums (12 months) $1,440 $1,800
Office copays (8 visits) $160 $0
ER copay (1 visit) $50 $0
Total $1,650 $1,800

In this example Plan N saves $150 a year. With a $30 monthly gap, you’d need about 18 office visits a year before Plan G came out ahead, not counting excess charges. Your real numbers depend on quotes for your ZIP code. Learn more about pricing in our guide to Medicare Supplement plans cost.

Questions? Talk to a Licensed Agent

We compare Plan G, Plan N and more from several insurance companies at no cost to you.

☎ 1-888-891-0229

No cost, no obligation to enroll

Who Plan N Fits Best

Plan N tends to work well if you:

✔
Want strong protection from hospital bills but a lower monthly premium than Plan G
✔
See the doctor a handful of times a year and rarely go to the ER
✔
Use doctors who accept Medicare assignment, so excess charges aren’t a concern
✔
Don’t mind paying a small copay at the visit in exchange for lower premiums

Plan G may be the better fit if you see specialists often or use doctors who may charge excess charges.

How to Buy Medicare Supplement Plan N in 2027

1
Time it right. Your 6-month Medigap open enrollment period starts when you’re 65 or older and enrolled in Part B. During it, companies can’t turn you down or charge you more because of your health.
2
Compare the same plan letter. Get Plan N quotes from several companies in your ZIP code. The coverage is the same, so compare price, discounts and rate increase history.
3
Check the company’s track record. Look at financial strength ratings and how often rates have gone up. See our list of the best Medicare Supplement companies.
4
Apply and keep your current coverage. If you’re replacing another policy, don’t cancel it until Plan N is approved and active.

Outside open enrollment, most states let companies ask health questions. Learn the timing rules in our guide to Medicare Supplement open enrollment.

Talk to an agent about Plan N

Speak with a licensed insurance agent

1-888-891-0229

Can You Change From Plan N Later?

Yes. Medicare Supplement plans don’t lock you in, and you can apply for a different plan any time of year. The catch is underwriting: after open enrollment, most companies can review your health before approving a change, especially a move up to Plan G.

So if you think you’ll want fuller coverage as you age, compare Plan G now. Our guide to switching from Plan N to Plan G covers the details.

Keep Reading

High-Deductible Plan G 2027: the $3,050 deductible, what counts toward it, premiums and our break-even scenarios.

Medicare Supplement Plan N — Frequently Asked Questions

➤ What does Medicare Supplement Plan N cover?

Plan N covers Part A coinsurance and hospital costs, the Part A deductible, Part B coinsurance (minus copays), skilled nursing and hospice coinsurance, the first 3 pints of blood and 80% of foreign travel emergencies up to plan limits.

➤ What doesn’t Plan N cover?

Plan N doesn’t cover the Part B deductible or Part B excess charges. You also pay up to $20 for some office visits and up to $50 for ER visits that don’t lead to an inpatient admission.

➤ What are the Plan N copays in 2027?

Up to $20 for Medicare-covered office visits and up to $50 for emergency room visits. These amounts are set by federal rules and haven’t changed since Plan N was created.

➤ Is the Plan N ER copay waived if I’m admitted?

Yes. The $50 copay is waived if you’re admitted to the hospital as an inpatient and the visit is covered under Part A. If you’re kept under observation, you’re still an outpatient, so the copay likely applies.

➤ Is Plan N better than Plan G?

Neither is better for everyone. Plan G covers more, with no copays and excess charge coverage. Plan N usually has a lower premium. If you rarely see doctors and your doctors accept Medicare assignment, Plan N often costs less overall.

➤ Does Plan N cover the Part B deductible?

No. You pay the Part B deductible yourself, $283 in 2026. CMS usually announces the next year’s amount in November. Plan G doesn’t cover it either; only Plans C and F do, and they’re limited to people eligible for Medicare before 2020.

➤ Can I get Plan N if I’m new to Medicare?

Yes. Plan N is available to anyone with Medicare Parts A and B where the company sells it. The best time to buy is your 6-month Medigap open enrollment period, when your health can’t be used to decline you.

➤ Can I switch from Plan N to Plan G?

Yes, you can apply any time of year. Outside open enrollment, most states let the company ask health questions and decline you, so keep Plan N until Plan G is approved.

Free Medigap Price Comparison

Call a Licensed Agent Now

Compare Plan G, Plan N and more from several insurance companies in one call.

☎ 1-888-891-0229

No cost, no obligation to enroll