Speak with a licensed insurance agent

1-888-891-0229

Manhattan Life Medicare Supplement 2027: Company Review, Ownership, Ratings and Why New Sales Stopped

Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated November 12, 2026

Key Takeaway

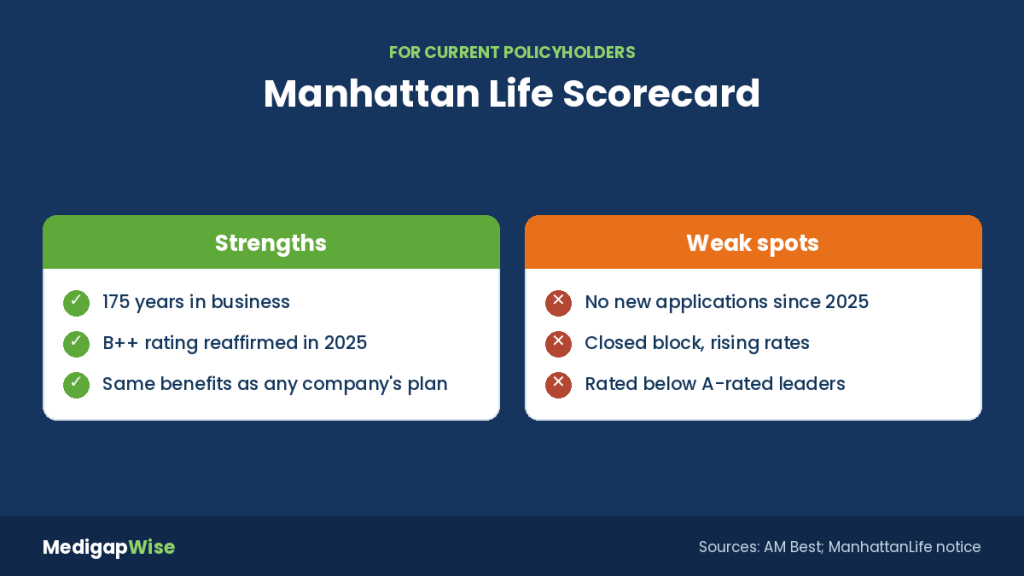
Manhattan Life is a New York insurer founded in 1850 and now run from Houston, rated B++ (Good) by AM Best, and it is a sound but mid-tier Medicare Supplement company that no longer takes new Medigap applications. It stopped new sales in every state on April 30, 2025; existing policies stay in force and are still serviced, so this review is mainly for current policyholders.

2027 by the Numbers

B++

AM Best financial strength for ManhattanLife’s insurers, affirmed Dec. 3, 2025 (AM Best)

0

States taking new ManhattanLife Medigap applications since April 30, 2025 (carrier notice to agents)

~13.1%

Policy-weighted rate change across its four Medigap insurers in Tennessee’s 2023–24 report (our math, TN SERFF data)

81.6%

Share of Manhattan Life Group owned by chairman David W. Harris (New York DFS exam, as of 2021)

Search for Manhattan Life Medicare Supplement reviews and most of what comes up still describes a low-priced Plan G you can buy today. That stopped being true in spring 2025, when the company closed its Medigap product to new applicants nationwide.

This review relies on regulator records instead: AM Best, New York’s financial exam, Tennessee’s rate report and Missouri’s complaint files.
Compare Medicare Supplement companies that are still enrolling

Speak with a licensed insurance agent

1-888-891-0229

Can You Still Buy a Manhattan Life Medicare Supplement Plan?

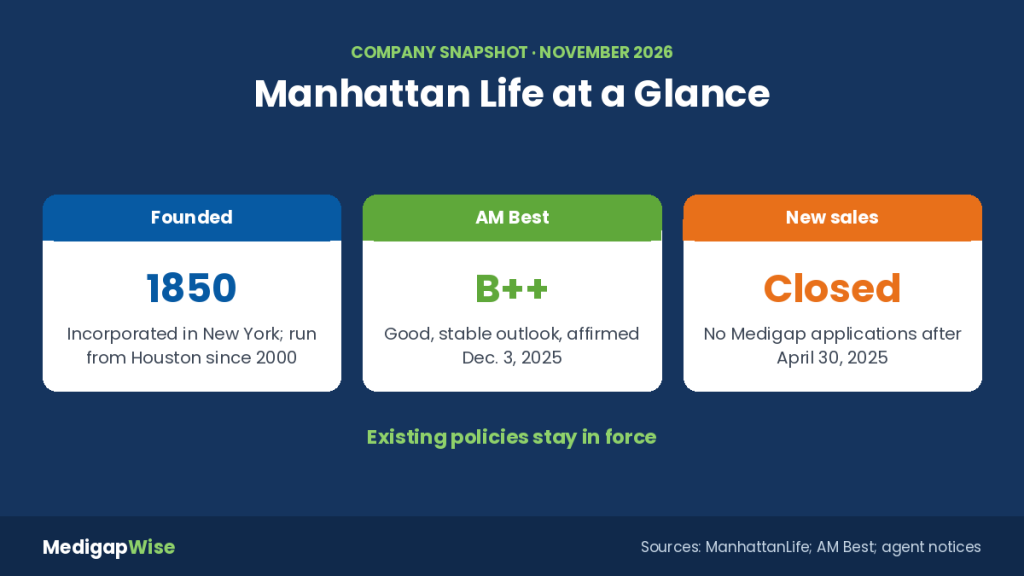
Manhattan Life Medicare Supplement at a glance: founded 1850, AM Best B++ affirmed December 2025, new Medigap sales ended April 30, 2025, four insurers in the group file Medigap rates

No. On April 4, 2025, ManhattanLife told its agents that it would stop accepting new Medicare Supplement business in all states, and that applications reaching its home office after April 30, 2025 would be withdrawn rather than processed.

The reason given in the carrier’s notice, as reprinted by several agencies, was that its reinsurer had decided to leave the Medigap market as of April 30, 2025, and ManhattanLife had not found a replacement. It said it was exploring a return, but as of November 2026 we found no announcement that it has resumed sales.

Stale listings: Comparison sites dated 2025 or 2026 may still show Manhattan Life Plan G and Plan N prices. Those figures predate the shutdown and can’t be bought.

From 66 Broadway to Houston: 175 Years in Brief

The Manhattan Life Insurance Company was incorporated in New York on May 29, 1850. In 1894 it finished its own headquarters at 66 Broadway, a tower billed as the world’s tallest building when it opened.

The modern company traces to a Texas insurer. Central United Life Insurance joined the Manhattan Life group in 1993, and in 2000 Central United’s owner, David Harris, bought Manhattan Life outright and moved the corporate office to Houston. Later deals added Western United Life Assurance of Spokane (2013), Humana’s workplace voluntary benefits lines (2018, the year the ManhattanLife brand was adopted) and Standard Life and Casualty of Salt Lake City (2020).

Medigap came through Family Life Insurance Company, which sold policies under its own name; New York’s examiners note The Manhattan Life Insurance Company took over writing that product in 2014. A newer Medigap product followed in 2020, sold exclusively through Integrity Marketing Group.

Who Owns ManhattanLife, and How Strong Is It?

ManhattanLife is privately held. New York’s Department of Financial Services examined The Manhattan Life Insurance Company as of December 31, 2021, and reported that its ultimate parent, Manhattan Life Group, Inc., was owned by eleven individuals, with David W. Harris holding 81.6%. It listed about $632.6 million in admitted assets for that insurer and one record-keeping violation.

AM Best rates the group’s insurers together as the Manhattan Insurance Group. Its most recent action, effective December 3, 2025, affirmed a financial strength rating of B++ (Good) and a long-term issuer credit rating of bbb, both with stable outlooks. That rating has held since a January 2022 upgrade from B+.

Rating in context: B++ is AM Best’s fifth-highest financial strength grade. It sits below the A and A+ ratings carried by the largest Medigap insurers, but it still describes a good ability to pay ongoing claims.

Four Insurers, One Brand: Our Carrier-Facts Table

Manhattan Life is a brand, not one company. Tennessee’s June 2023 to June 2024 rate report lists Medigap filings from four group insurers. We combined it with Missouri and New York records:

Insurer on the policy Base Medigap background TN rate change (policies)
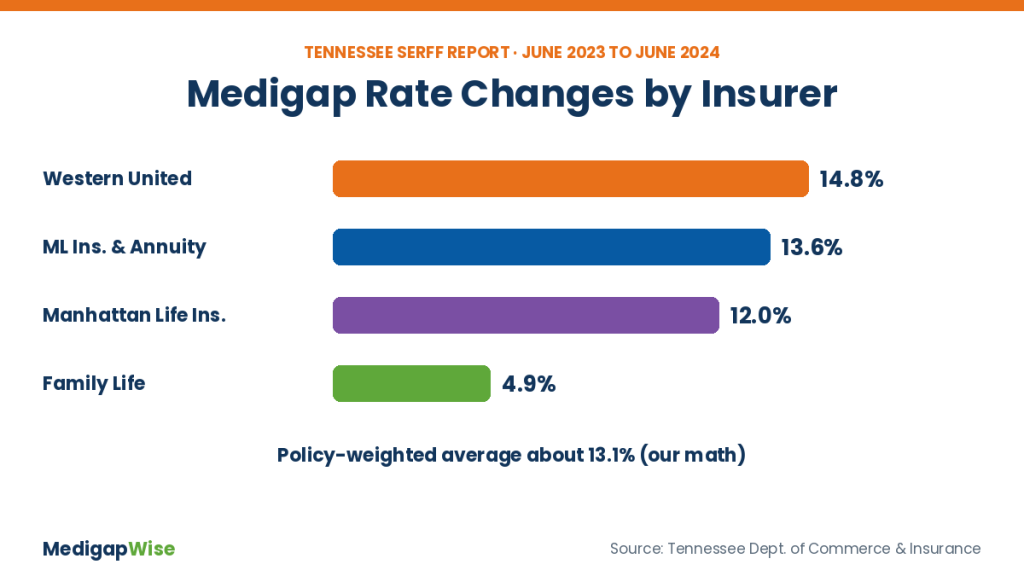
ManhattanLife Insurance and Annuity Co. Houston, TX (NAIC 61883) Formerly Central United Life; named in the 2025 discontinuance notice 13.6% (2,038)
The Manhattan Life Insurance Co. New York charter Began writing Medigap in 2014 12.0% (849)
Western United Life Assurance Co. Spokane, WA Acquired in 2013 14.8% (1,022)
Family Life Insurance Co. Houston, TX Sold the group’s Medigap under its own name 4.9% (236)
All four (our math) 4,145 Tennessee policies ~13.1% weighted

Missouri’s records show the Houston insurer was Central United Life until July 2017 and ManhattanLife Assurance Company of America until 2022, when it moved its domicile from Arkansas to Texas. Use the insurer named on page one of your policy when you look up filings.

Questions? Talk to a Licensed Agent

We compare Plan G, Plan N and more from several insurance companies at no cost to you.

☎ 1-888-891-0229

No cost, no obligation to enroll

Rate Filings and What a Closed Block Means for Premiums

Tennessee 2023 to 2024 Medicare Supplement rate changes for ManhattanLife insurers: Western United Life 14.8%, ManhattanLife Insurance and Annuity 13.6%, The Manhattan Life Insurance Company 12.0%, Family Life 4.9%

A Medigap product that stops taking new members becomes a closed block. With no new, younger members joining, average age and claims climb, and rate requests follow. Actuarial firm CSG Actuarial reports that average closed-block Medigap increases were 10.75% in 2025 and about 11% so far in 2026.

Manhattan Life’s Tennessee filings were already in that range before the shutdown. Here is the weighted 13.1% on a hypothetical premium, plus two years at CSG’s 11% average:

1
Starting premium. $160 a month.
2
After a 13.1% change. $160 times 1.131 is $180.96.
3
Two more years at 11%. $180.96 times 1.11 is $200.87, then $222.97.
4
Result. About $63 more a month than the start, or roughly $756 a year, before any age-based steps.

Rates are approved state by state, and we could not find a published 2027 figure for any ManhattanLife insurer. Our Medicare Supplement rate increases guide explains how these filings are reviewed.

Get 2027 quotes for the plan letter on your Manhattan Life policy

Speak with a licensed insurance agent

1-888-891-0229

Plans, Pricing and Discounts on Existing Policies

Review sites list Manhattan Life Medigap Plans A, C, F, G and N. We could not confirm a High-Deductible Plan G or any extra-benefit version; dental, vision and hearing were separate policies.

Benefits are fixed by federal law, so a Manhattan Life Plan G pays the same claims as anyone else’s. Coverage details are on our Manhattan Life Medicare Supplement Plan G page.

Policies generally use attained-age pricing, meaning the premium also steps up as you get older. Reviewers report a household or spousal discount of 7% to 12% depending on the state. An existing discount continues under your policy’s terms.

Review Scorecard: Complaints, Strengths and Weak Spots

Manhattan Life Medicare Supplement scorecard: strengths include 175 years in business, a stable B++ rating and standardized benefits; weak spots include no new sales, a closed block and a rating below the A-rated leaders

Missouri’s complaint index compares an insurer’s complaints with its share of the market; 100 is average. ManhattanLife Insurance and Annuity Company drew one Medicare Supplement complaint in Missouri in 2023, an index of 171, and three in 2024. Small counts swing the index a lot.

Its Missouri Medigap premiums grew from about $24,000 in 2021 to $15.4 million in 2023, with a 2023 loss ratio near 74%.

Who a policy still suits:

✔
Good fit to keep: you’re in good health, the premium is still competitive for your ZIP code and you value an insurer with a long history.
✔
Worth comparing: your latest increase was well above 10%, or you hold Plan F and a switch from Plan F to Plan G could lower the premium.
✔
Shop soon: your health is changing and you live in a state without a yearly switching window, since underwriting only gets harder later.

Staying With Manhattan Life or Shopping for 2027

Keeping your policy is a reasonable choice if the premium still fits your budget, because Medigap coverage renews automatically as long as you pay.

1
Read your renewal letter. Note the percentage and compare it with what other companies charge for the same plan letter in your ZIP code.
2
Check for a no-health-questions window. Leaving a carrier by choice isn’t a federal guaranteed issue event, but some states give yearly rights; see Medicare birthday rule states and guaranteed issue rights by state.
3
Prepare for underwriting. Most switchers answer Medigap underwriting questions, so apply while your health allows.
4
Keep the old policy until approved. Cancel Manhattan Life only after the new plan is issued, and use the Medicare Supplement free look period if needed.

For replacements, start with our ranking of the best Medicare Supplement companies, then compare reviews such as Mutual of Omaha Medicare Supplement and Allstate Medicare Supplement, another brand that closed Medigap to new buyers in 2025.

Keep Reading

Heartland National Medicare Supplement 2027: a small B++ insurer with 25% Iowa rate hikes in 2025 and 2026 and new investors approved in March 2026.

Manhattan Life Medicare Supplement Reviews: Your Questions Answered

➤ Why did Manhattan Life stop selling Medicare Supplement insurance?

The company’s April 2025 notice said its reinsurer was leaving the Medicare Supplement market on April 30, 2025, and it had not found a replacement, so it closed the product to new applications in every state.

➤ Is my Manhattan Life Medigap policy still valid?

Yes. The discontinuance notice said in-force policies continue to be serviced as usual. Your coverage stays active as long as premiums are paid.

➤ Are Family Life and Western United part of Manhattan Life?

Yes. Family Life Insurance Company, Western United Life Assurance Company, The Manhattan Life Insurance Company and ManhattanLife Insurance and Annuity Company all belong to Manhattan Life Group and all hold Medigap policies.

➤ What is Manhattan Life’s AM Best rating?

B++ (Good) with a stable outlook, affirmed by AM Best effective December 3, 2025, for the Manhattan Insurance Group companies.

➤ Who owns ManhattanLife?

It is privately held. New York regulators reported that its parent, Manhattan Life Group, Inc., was owned by eleven individuals, with chairman David W. Harris holding 81.6% as of 2021.

➤ How much have Manhattan Life Medicare Supplement rates gone up?

Tennessee’s 2023 to 2024 report shows changes of 4.9% to 14.8% across the four insurers, about 13.1% on a policy-weighted basis. Amounts differ by state and year.

➤ Are older online reviews of Manhattan Life Medigap still accurate?

Not fully. Reviews written before April 2025 describe a plan you could buy; ratings and company history still apply, but prices and enrollment advice do not.

➤ Does ManhattanLife still sell other coverage for seniors?

Yes. It continues to offer products such as hospital indemnity, dental and other supplemental health and life policies, though some products are being phased out.

Free Medigap Price Comparison

Call a Licensed Agent Now

Compare Plan G, Plan N and more from several insurance companies in one call.

☎ 1-888-891-0229

No cost, no obligation to enroll