Speak with a licensed insurance agent

1-888-891-0229

Medicare Supplement Plan G 2027: What It Covers, What It Costs and Who It Fits

Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated October 27, 2026

Key Takeaway

Medicare Supplement Plan G pays your share of every Medicare-approved hospital and medical bill except the yearly Part B deductible, so in 2027 your out-of-pocket costs for covered care are that one deductible plus your premiums. It’s the fullest plan people new to Medicare since 2020 can buy, and it works with any provider in the U.S. that accepts Medicare.

2027 by the Numbers

$283

2026 Part B deductible, the one gap Plan G leaves; CMS sets the 2027 amount in November (CMS)

$1,736

2026 Part A deductible per benefit period, paid in full by Plan G (CMS)

$202.90

2026 standard Part B premium, which you still pay on top of Plan G (CMS)

$3,050

2027 deductible for the high-deductible version of Plan G (CMS)

Plan G has become the default choice for many people joining Medicare, and the reason is simple: it leaves almost nothing to chance. Once you’ve met the Part B deductible, Medicare-approved care costs you nothing more for the rest of the year, whether that’s a hospital stay, rehab in a nursing facility or a long run of specialist visits.

Below: each Plan G benefit with CMS dollar amounts, a full year of costs with two hospital stays, and what Plan G leaves out.

Get Plan G quotes in your area

Speak with a licensed insurance agent

1-888-891-0229

Plan G in Plain Terms: One Deductible, Then Nothing

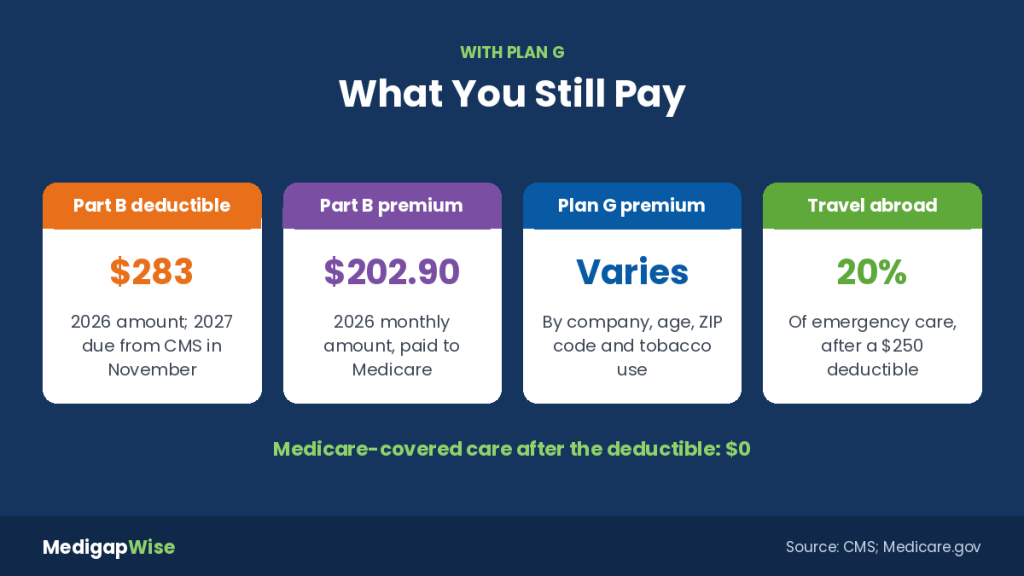
What you still pay with Medicare Supplement Plan G: the Part B deductible, the Part B premium, your Plan G premium and 20% of foreign travel emergencies after $250

Medigap Plan G is one of the standardized lettered plans, so its benefits are set by federal rules, not by the insurer. Only the price, discounts and rate history change from company to company.

Medicare pays its share of an approved claim first, then Plan G pays the rest of your share. The only Medicare cost it never picks up is the Part B deductible, paid once a calendar year.

Why it’s the top plan for new enrollees: Plans C and F, which also cover the Part B deductible, aren’t sold to anyone who became eligible for Medicare on or after January 1, 2020, according to Medicare’s official Medigap guide. That leaves Plan G as the most complete option for that group.

For the full lineup of plan letters, see our guide to Medicare Supplement plans.

Every Plan G Benefit, With the CMS Dollar Amounts

These are CMS’s 2026 amounts. CMS normally releases the 2027 Part A and Part B figures in November, and Plan G pays the same share of whatever they turn out to be.

Medicare gap 2026 amount (CMS) Plan G pays You pay
Part A hospital deductible $1,736 per benefit period 100% $0
Hospital days 61–90 $434 a day 100% $0
Lifetime reserve days $868 a day 100% $0
Hospital days after Medicare runs out Full cost 100%, up to 365 more days $0
Skilled nursing days 21–100 $217 a day 100% $0
Part B coinsurance Usually 20% of the approved amount 100% $0
Part B excess charges Up to 15% over the approved amount 100% $0
Hospice coinsurance and first 3 pints of blood Varies 100% $0
Foreign travel emergency Billed charges abroad 80% after $250 $250 + 20%
Part B deductible $283 a year 0% $283

Foreign travel coverage has limits: the emergency has to begin in the first 60 days of a trip, and there’s a $50,000 lifetime maximum, according to Indiana’s State Health Insurance Assistance Program.

Benefit Periods: Why the Hospital Deductible Can Come Due Twice

The Part A deductible isn’t a once-a-year charge. Medicare bills it once per benefit period, which starts the day you’re admitted as an inpatient and ends after you’ve gone 60 days in a row without inpatient hospital or skilled nursing care, as Wisconsin’s Board on Aging and Long Term Care explains. Go back into the hospital after that and a new benefit period, with a new deductible, begins.

So a person with a spring surgery and a fall readmission could owe the deductible twice in one year: $3,472 at 2026 rates. Plan G pays every one of them.

Inpatient vs observation: Under observation status you’re an outpatient billed under Part B, not Part A. Once the Part B deductible is met, Plan G pays your Part B coinsurance for covered services, so either way the plan picks up your share.

A Worked 2027 Example: Two Hospital Stays and a Year of Outpatient Care

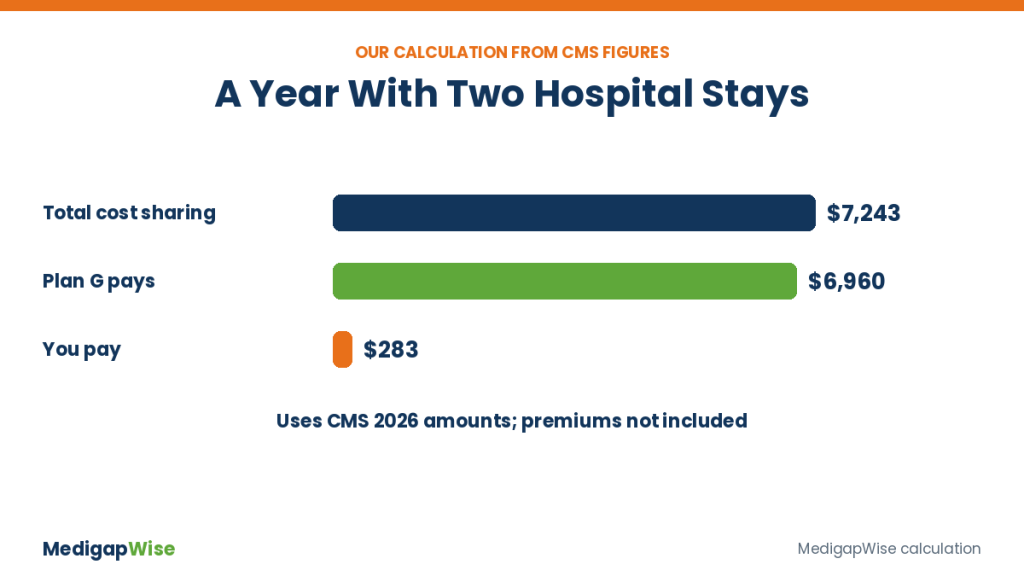
Our worked example: $7,243 of Medicare cost sharing in a year with two hospital stays, of which Plan G pays $6,960 and you pay $283

We built a hard year from CMS figures. Our assumptions: CMS’s 2026 amounts stand in for 2027; the person is admitted in March, spends 25 days in a skilled nursing facility afterward, then is readmitted in October after more than 60 days at home; and over the year they get $12,000 of Medicare-approved Part B care, including one specialist who doesn’t accept assignment and adds a $60 excess charge.

✔
Two Part A deductibles: 2 × $1,736 = $3,472
✔
Skilled nursing days 21–25: 5 × $217 = $1,085
✔
Part B deductible: $283
✔
Part B coinsurance: 20% of the $11,717 left after the deductible = $2,343
✔
Excess charge: $60

That’s $7,243 of Medicare cost sharing. With Plan G, the plan pays $6,960 and you pay $283, the Part B deductible, plus your premiums. Without any supplement, the whole $7,243 would be yours, and Original Medicare has no yearly out-of-pocket limit.

Compare Plan G prices from several companies

Speak with a licensed insurance agent

1-888-891-0229

What Plan G Won't Pay For

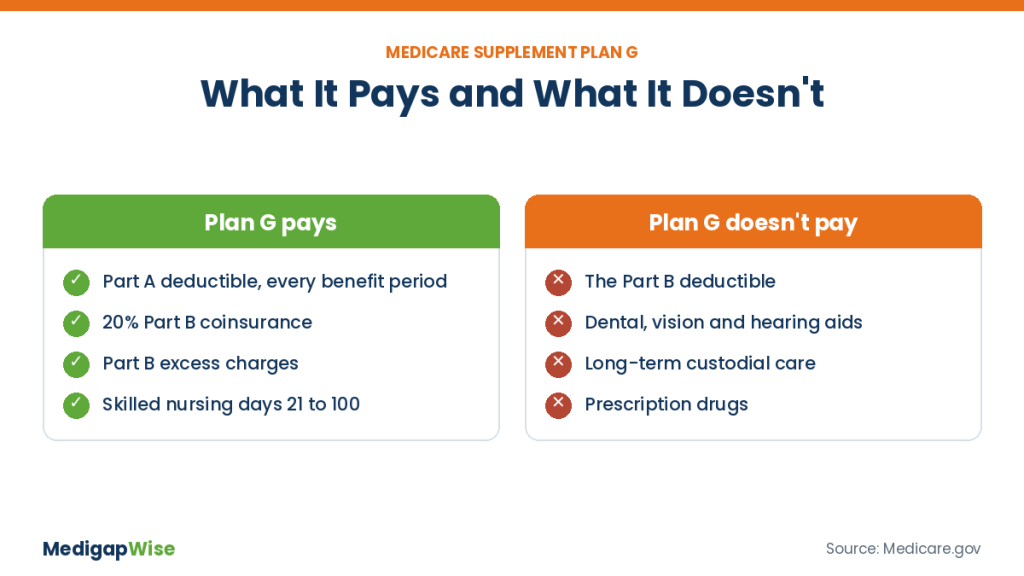
What Medicare Supplement Plan G pays, such as the Part A deductible and excess charges, versus what it doesn't, such as dental, hearing aids and drugs

Plan G only fills gaps in services Medicare covers. Medicare’s official guide to choosing a Medigap policy lists the things Medigap doesn’t cover, and Plan G is no exception:

Not covered

✔Long-term custodial care
✔Routine dental and vision care, and eyeglasses
✔Hearing aids
✔Private-duty nursing
✔Prescription drugs (you’d need a separate Part D plan)

Still your bill

✔The Part B deductible
✔Your Part B premium, $202.90 a month in 2026
✔Your Plan G premium
✔Care from providers who’ve opted out of Medicare

Medicare.gov says Medicare won’t pay opted-out providers except in emergencies, and since Plan G pays only after Medicare approves a claim, it generally won’t either. Doctors who just don’t accept assignment are different: Plan G covers their excess charges. For hearing care specifically, see does Medicare Plan G cover hearing aids.

Questions? Talk to a Licensed Agent

We compare Plan G, Plan N and more from several insurance companies at no cost to you.

☎ 1-888-891-0229

No cost, no obligation to enroll

Plan G Alongside Plan F, Plan N and High-Deductible G

Plan G is usually weighed against three neighbors, each with its own guide:

✔
Plan F adds the Part B deductible but is closed to anyone eligible for Medicare since 2020. If you already have it, compare the premium gap in our Medicare Supplement Plan F cost guide or see how to switch from Plan F to Plan G.
✔
Plan N trades office and ER copays and no excess charge coverage for a lower premium. Its copay math is in our Medicare Supplement Plan N guide, and moving up later is covered in switching from Plan N to Plan G.
✔
High-Deductible Plan G has the same benefits, but only after you pay $3,050 of covered costs in 2027. Our High-Deductible Plan G guide runs the break-even numbers.

What Sets the Price of a Plan G Policy

With identical coverage, the premium is the real difference between companies. Rates depend on your age, the company’s rating method (attained-age, issue-age or community), your ZIP code, gender and tobacco use.

Also weigh how a company’s rates have moved over time (see Medicare Supplement rate increases) and discounts, such as a household discount.

We don’t list sample premiums because they vary too much by state and age. For pricing across plan letters, read Medicare Supplement plans cost, or get real Plan G quotes for your ZIP code.

Talk to an agent about Plan G

Speak with a licensed insurance agent

1-888-891-0229

When to Apply for Plan G, and Rules That Catch People Out

1
Use your 6-month open enrollment window. It starts the first month you have Part B and are 65 or older, and it happens only once. During it, a company can’t turn you down or charge more because of your health. Details are in our guide to Medicare Supplement open enrollment.
2
Expect health questions after that. Outside open enrollment or a guaranteed issue right, most states let insurers review your health first. Know what they ask with our list of Medigap underwriting questions. A few states have birthday-type rules that loosen this.
3
Buy one policy per person. A Medigap policy covers only one person, so spouses each need their own Plan G.
4
Check your state’s plan names. Massachusetts, Minnesota and Wisconsin standardize Medigap differently, so their plans don’t follow the usual Plan G label; ask what the closest equivalent is.

Plan G works only with Original Medicare, not with a Medicare Advantage plan. Our list of the best Medicare Supplement companies is a good place to start.

Keep Reading

Medigap vs Medicare Advantage 2027: what each path costs in a quiet year and a hospital year, how networks and prior approval differ, and why the first choice is hard to reverse.

Medicare Supplement Plan G — Frequently Asked Questions

➤ Is Plan G identical no matter which company sells it?

Yes. Plan G’s benefits are standardized by federal rules, so every insurer pays the same things. Companies differ only on price, discounts and service.

➤ What will I pay out of pocket with Plan G in 2027?

For Medicare-covered care, just the Part B deductible, which was $283 in 2026; CMS announces the 2027 amount in November. You also pay your Plan G and Part B premiums, plus $250 and 20% of any foreign travel emergency.

➤ Can Plan G pay the Part A deductible more than once in a year?

Yes. Medicare charges the Part A deductible per benefit period, not per year, and Plan G pays it each time. With two separate hospital stays at 2026 rates, that’s $3,472 Plan G covers.

➤ Can I see any doctor with Plan G?

You can see any doctor or hospital in the U.S. that accepts Medicare, with no network and no referrals. The exception is providers who have opted out of Medicare.

➤ What does Plan G pay for emergencies outside the U.S.?

80% of emergency care abroad after a $250 yearly deductible, if the emergency starts in the first 60 days of your trip, up to a $50,000 lifetime limit.

➤ Is Plan G sold in Massachusetts, Minnesota and Wisconsin?

Generally not under that name. Medicare.gov notes those three states standardize Medigap in a different way, so you’d compare their state-specific plans instead.

➤ Do spouses need separate Plan G policies?

Yes. A Medigap policy covers one person. Some companies offer a household discount when both spouses buy, depending on the state.

➤ Does Plan G pay my Part B premium?

No. You keep paying the Part B premium to Medicare, $202.90 a month in 2026, and pay your Plan G premium separately to the insurance company.

Free Medigap Price Comparison

Call a Licensed Agent Now

Compare Plan G, Plan N and more from several insurance companies in one call.

☎ 1-888-891-0229

No cost, no obligation to enroll