Speak with a licensed insurance agent

1-888-891-0229

Free Medicare Supplement Plans 2027: Why No Policy Is $0, and the Programs That Pay Your Medicare Costs Instead

Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated November 14, 2026

Key Takeaway

There are no free Medicare Supplement plans. Every Medigap policy carries a monthly premium set by the insurer; the lowest Plan G quote we pulled for a 65-year-old man in Austin, Texas was $157.70 a month. What can be free is help with the same bills: Medicare Savings Programs, Medicaid, retiree coverage and free SHIP counseling.

2027 by the Numbers

$3,050

2027 deductible for High-Deductible Plan G (CMS, Oct. 2026)

$202.90

2026 Part B premium that QMB, SLMB and QI pay for you; CMS hadn’t posted 2027’s on Nov. 14

$9,950

2026 Medicare Savings Program resource limit, one person (SSA)

75%

of 2026 Medicare Advantage drug-plan enrollees pay no premium beyond Part B (KFF)

Insurers don’t sell a no-cost Medicare Supplement, and Medicare doesn’t hand one out. But several public programs pay the very costs a supplement exists to cover. Below we line up those programs with our own yearly math and flag which 2027 numbers are final.
Check what a Medicare Supplement costs in your ZIP code

Speak with a licensed insurance agent

1-888-891-0229

Is Any Medicare Supplement Plan Actually $0?

No. A Medigap policy is private insurance, and each company files its own premiums with the state. Even the cheapest letter costs something every month. In our November 12, 2026 quote run for a 65-year-old non-smoking man in Austin (ZIP 78701), the four lowest Plan G prices ran from $157.70 to $194.72 a month, and the four lowest High-Deductible Plan G prices from $50.78 to $58.73.

Those premiums sit on top of the Part B premium, which was $202.90 a month in 2026. The real question is whether someone else can pay part of these bills.

Ads that say “free”: They usually mean a $0-premium Medicare Advantage plan or a free quote, not a free policy.

The 2027 Numbers a Supplement Would Normally Cover

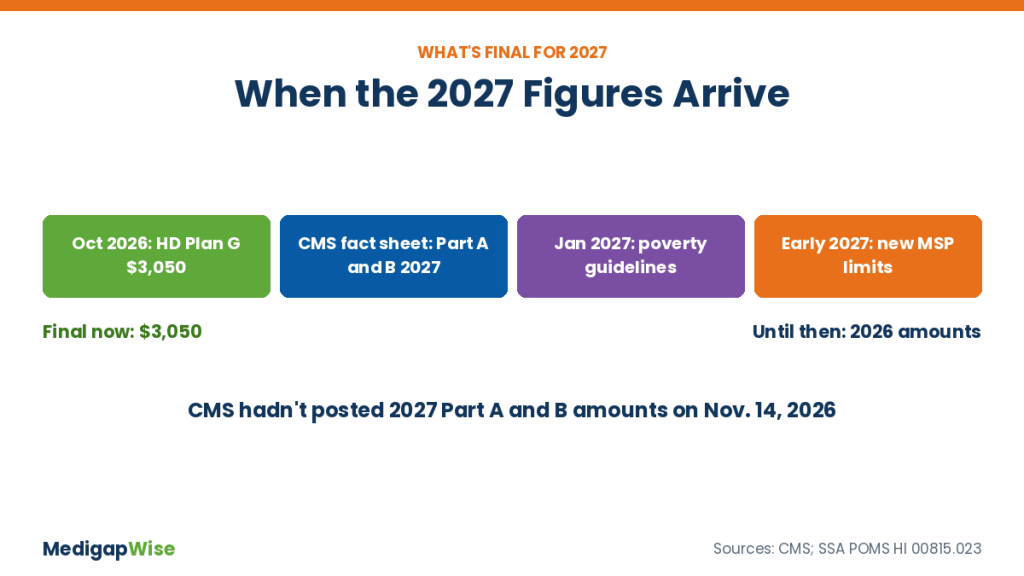
When the 2027 Medicare figures arrive: CMS set the High-Deductible Plan G deductible at $3,050 in October 2026, Part A and B amounts come with the CMS fact sheet, and new Medicare Savings Program limits follow the January poverty guidelines

As of November 14, 2026, CMS had fixed the 2027 deductible for High-Deductible Plans F and G at $3,050 in an October 2026 notice. The 2027 Part A and B amounts were still unpublished, and Medicare.gov listed 2026 figures.

✔
Part B premium: $202.90 a month in 2026. The 2026 Medicare Trustees Report projected $209.50 for 2027, which is an estimate, not the official figure.
✔
Part B deductible: $283 in 2026, projected at $292 for 2027. It’s the one deductible regular Plan G leaves to you, explained on our Medicare Supplement Plan G deductible page.
✔
Part A deductible: $1,736 per benefit period in 2026; CMS publishes 2027’s with the Part B amounts.

QMB pays every one of these for an eligible person, making it the closest real match to a free supplement.

Medicare Savings Programs Side by Side, With Our Yearly Math

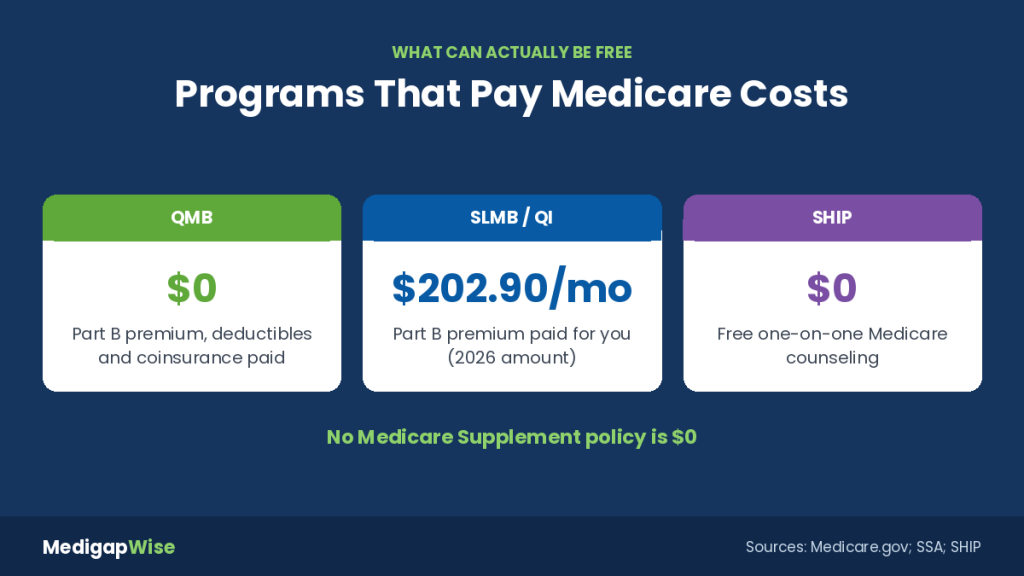
Programs that pay Medicare costs instead of a free Medicare Supplement plan: QMB pays Part B premium, deductibles and coinsurance; SLMB and QI pay the $202.90 monthly Part B premium in 2026; SHIP counseling costs $0

These are Social Security’s 2026 limits for every state except Alaska and Hawaii, which allow higher incomes. The yearly value column is our own math at 2026 Medicare amounts.

Program Monthly income limit (single / couple) Resource limit (single / couple) What it pays Yearly value, our math Is Medigap still worth buying?
QMB $1,350 / $1,824 $9,950 / $14,910 Part B premium, Part A and B deductibles, coinsurance $2,434.80 premium + $283 deductible + 20% coinsurance Rarely: QMB already covers the cost sharing
SLMB $1,616 / $2,184 $9,950 / $14,910 Part B premium only $2,434.80 Can be; CMS allows a sale when Medicaid pays only premiums
QI $1,816 / $2,455 $9,950 / $14,910 Part B premium only; reapply yearly, first come, first served $2,434.80 Can be, same exception as SLMB

All three also bring Extra Help with Part D drug costs, according to Medicare.gov. See the current thresholds on our Extra Help income limits page.

Why QMB beats a supplement for those who qualify: Providers can’t bill a QMB member for Medicare-covered services, so the gaps Plan G fills are already closed. Medigap sales to Medicaid enrollees are generally barred; see our Medicare Supplement eligibility page for details.

Compare Plan G and High-Deductible G prices

Speak with a licensed insurance agent

1-888-891-0229

The Asset Test Gap: States That Don't Count Your Savings

The federal $9,950 resource limit doesn’t apply everywhere. Medicare Interactive lists these places as having no Medicare Savings Program asset limit as of January 2026: Alabama, Arizona, Connecticut, Delaware, Louisiana, Massachusetts, Mississippi, New Mexico, New York, Oregon, Vermont and the District of Columbia.

There, savings don’t block approval if income qualifies. Elsewhere, Medicare.gov notes some states ignore certain income or resources, so apply even if you’re slightly over.

Our math: at the 2026 QMB income line of $1,350 a month, the $202.90 Part B premium alone eats 15.0% of income, and the cheapest Austin Plan G quote would take another 11.7%. At the QI line of $1,816, that Plan G premium is still 8.7% of income.

2027 limits: They follow January’s poverty guidelines; the 2026 table took effect February 26, 2026.

Questions? Talk to a Licensed Agent

We compare Plan G, Plan N and more from several insurance companies at no cost to you.

☎ 1-888-891-0229

No cost, no obligation to enroll

Worked Example: QMB vs. Paying for Plan G Yourself

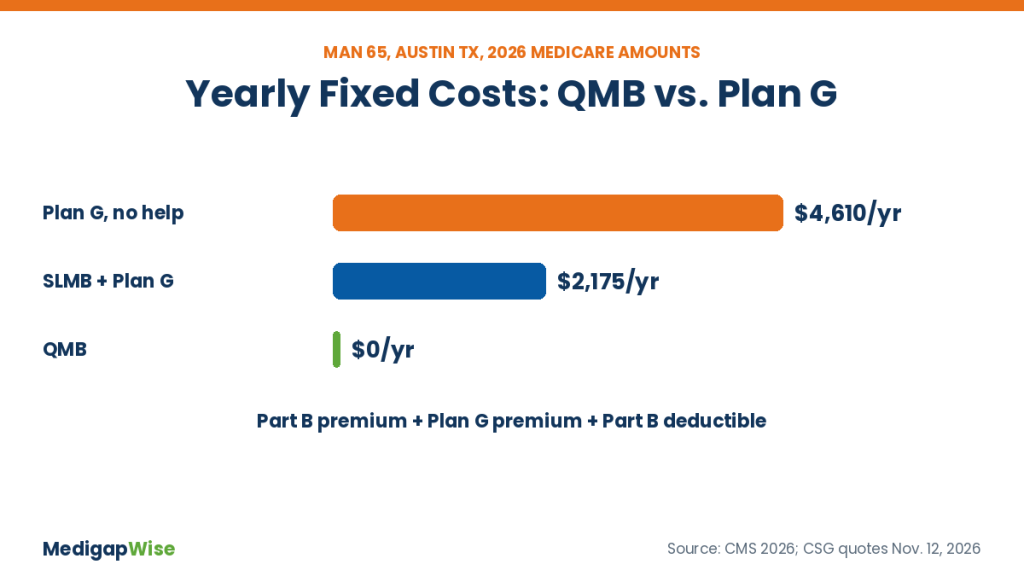
Yearly fixed Medicare costs at 2026 amounts for a 65-year-old man in Austin, Texas: $4,610 paying for Plan G with no help, $2,175 with SLMB plus Plan G, and $0 with QMB

Take a 65-year-old man in Austin, Texas, using 2026 Medicare amounts and the lowest Plan G quote in our November 12, 2026 run. Fixed yearly costs only:

Paying for Plan G

✔Part B premium: $202.90 × 12 = $2,434.80
✔Plan G premium: $157.70 × 12 = $1,892.40
✔Part B deductible: $283
✔Total: $4,610.20 a year

SLMB plus Plan G

✔Part B premium: paid by the state
✔Plan G premium: $1,892.40
✔Part B deductible: $283
✔Total: $2,175.40 a year

QMB

✔Part B premium: paid
✔Part B deductible and 20% coinsurance: covered
✔No supplement needed
✔Total: $0 for Medicare-covered care

Texas keeps the federal asset test, so this person would also need resources under $9,950. That $4,610 gap is the only “free supplement” that really exists.

$0-Premium Medicare Advantage Is a Different Product

The plans advertised as costing nothing are Medicare Advantage plans. KFF reports that 75% of people in individual Advantage plans with drug coverage paid no premium beyond Part B in 2026. These plans replace Original Medicare rather than supplement it, so you can’t hold one and a Medigap policy together.

A $0 premium doesn’t mean $0 spending. Advantage plans charge copays as you use care, up to a yearly in-network out-of-pocket limit that averaged $5,421 in 2026, per KFF, and most use provider networks. A supplement works the other way: a steady premium with little cost sharing at any provider that takes Medicare. Our Medigap vs. Medicare Advantage guide walks through both in detail.

Retiree and Union Coverage: A Supplement Someone Else Funds

Some former employers and unions offer group retiree plans that pay after Medicare, much like a supplement. Depending on the plan, the retiree may pay nothing toward it. If your retiree coverage already pays the Part A and Part B gaps, buying a Medigap policy too would mostly duplicate benefits.

Keep your plan documents handy. If your former employer ends retiree coverage that paid after Medicare, federal rules give you a guaranteed issue right to buy certain Medigap plans without health questions. Our guaranteed issue rights by state page lists which plans qualify and how long the window lasts.

Free Help and Real Ways to Shrink a Medigap Premium

The 54 State Health Insurance Assistance Programs (SHIPs) are funded by the Administration for Community Living and charge nothing for counseling. A licensed agent can also compare supplement prices at no charge.

1
Pick the lowest-premium letter that fits. In our Austin run, High-Deductible G started at $50.78 a month versus $157.70 for Plan G. See High-Deductible Plan G.
2
Ask about household savings. Some insurers cut the price when another adult at home is covered; see our household discount guide.
3
Pay by bank draft. Highmark’s 2026-27 Pennsylvania rate charts list a $2-a-month discount for EFT or paperless enrollment, $24 a year.
4
Compare the same letter across companies. Benefits are identical by law, so the lowest price is the best deal.

For what drives premiums, see our guide to Medicare Supplement plans cost.

Ask a licensed agent whether a supplement still makes sense for you

Speak with a licensed insurance agent

1-888-891-0229

Free Medicare Supplement Plans: Your Questions Answered

➤ Is there a Medicare Supplement plan with no monthly premium?

No. Every Medigap policy has a premium set by the insurance company. The lowest-priced letter, usually High-Deductible Plan G, started at $50.78 a month for a 65-year-old man in our Austin, Texas quotes.

➤ Does QMB work like a Medicare Supplement?

For Medicare-covered care, it does more. QMB pays the Part B premium, deductibles and coinsurance, so a supplement adds little.

➤ Can the state pay my Medigap premium?

Rarely. CMS allows it when a state Medicaid program chooses to pay a Medigap premium. Ask your state Medicaid office.

➤ What are the 2026 income limits for help paying the Part B premium?

For one person outside Alaska and Hawaii: $1,350 a month for QMB, $1,616 for SLMB and $1,816 for QI. The resource limit is $9,950 for one person and $14,910 for a couple.

➤ Which states have no asset test for Medicare Savings Programs?

As of January 2026, Medicare Interactive lists Alabama, Arizona, Connecticut, Delaware, Louisiana, Massachusetts, Mississippi, New Mexico, New York, Oregon, Vermont and D.C.

➤ Is a $0-premium Medicare Advantage plan the same as a free supplement?

No. It replaces Original Medicare, usually uses a network and charges copays. You can’t combine it with Medigap.

➤ When will the 2027 Medicare Savings Program limits come out?

Early in 2027, after January’s federal poverty guidelines. The 2026 limits took effect February 26, 2026.

➤ Where can I get free help with Medicare Supplement decisions?

Your State Health Insurance Assistance Program offers counseling at no cost. A licensed agent can compare Medigap prices for free.

Free Medigap Price Comparison

Call a Licensed Agent Now

Compare Plan G, Plan N and more from several insurance companies in one call.

☎ 1-888-891-0229

No cost, no obligation to enroll